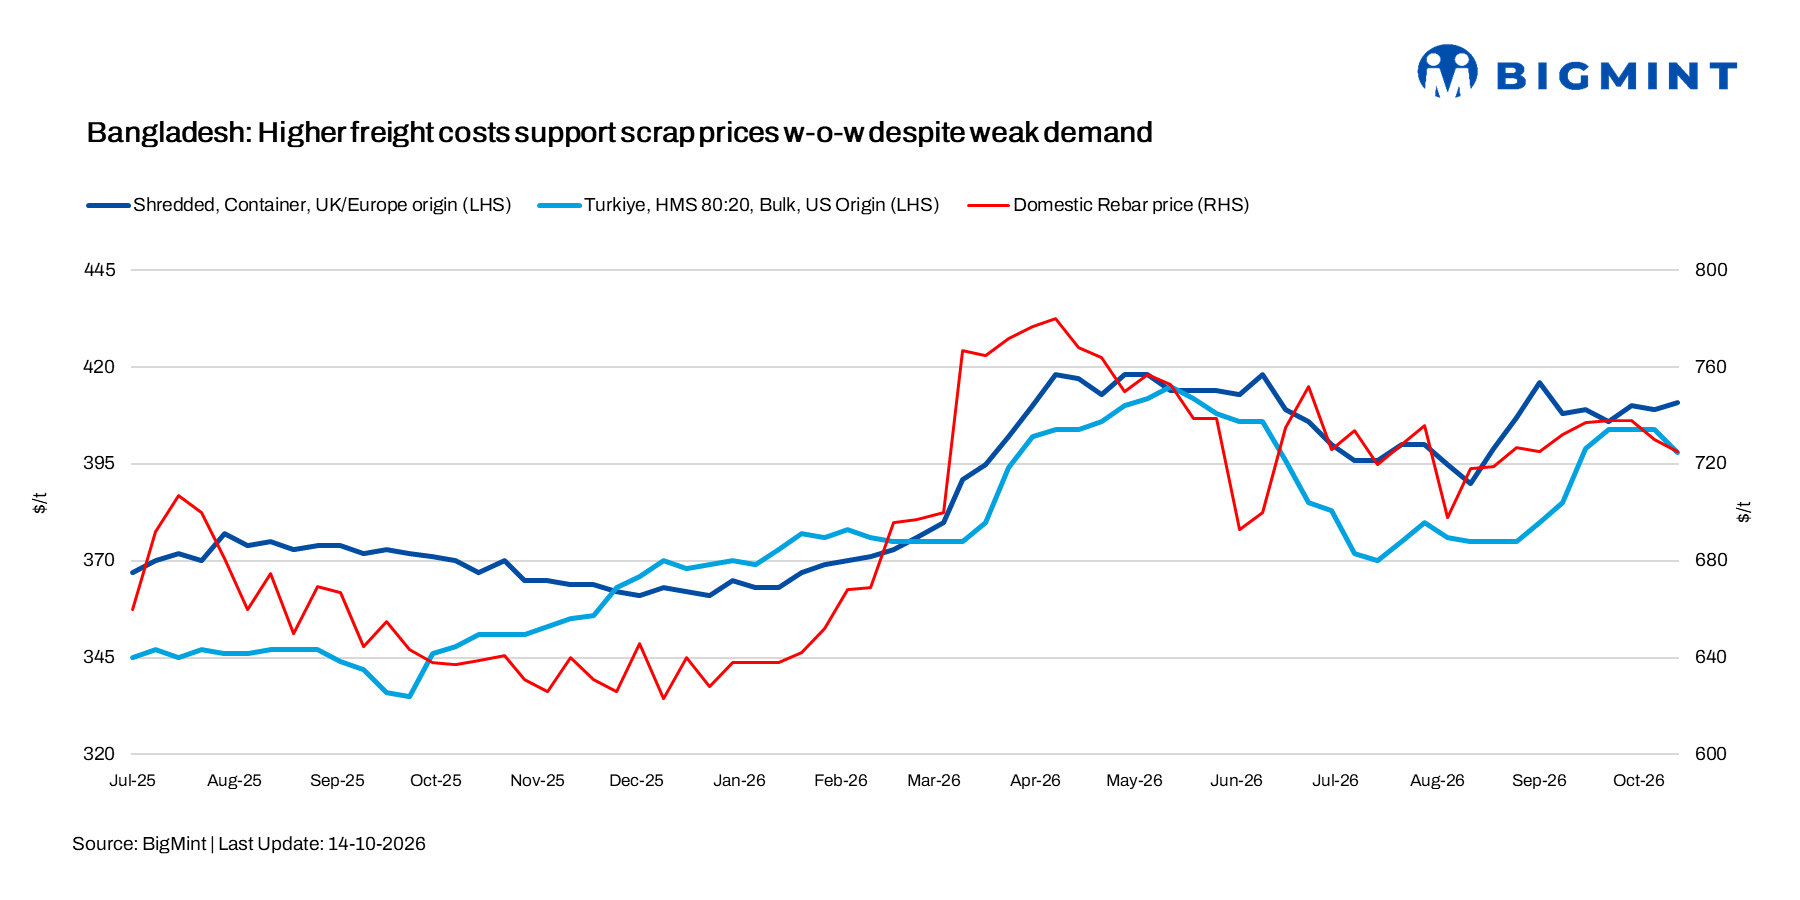
- Higher freight costs keep scrap buyers cautious
- Limited transactions reflect cautious mill procurement
Bangladesh’s imported ferrous scrap market remained subdued during the week ended 14 October, as weak finished steel demand and cautious mill procurement limited trading activity. Firm freight rates and rising landed costs kept buyers selective, while suppliers continued negotiating to secure deals.
BigMint’s weekly assessments, CFR Chattogram
- European-origin containerised HMS 80:20: $376/t, up $1/t w-o-w
- European-origin containerised shredded scrap: $411/t, up $2/t w-o-w
- Japanese-origin bulk H2: $399/t, up $3/t w-o-w
- US-origin bulk HMS 80:20: $407/t, up $3/t w-o-w
Market scenario
A Chattogram-based trader said, “Hong Kong-origin PNS was offered at $415-420/t CFR Chattogram, while Malaysian bundle mix was quoted at $345-350/t and busheling at $415/t CFR.”
A steel mill source reported Brazilian HMS offers at $370-380/t, Malaysian GI bundles at $335/t, LMS bundles at $345/t and busheling at $410/t.
Containerised scrap trading remained sluggish. Malaysian PNS scrap was offered at $415-420/t CFR, compared with around $415/t CFR in late September. Malaysian HMS 90:10 offers stood at $390-395/t CFR, while Australian-origin material was available at $400-405/t CFR. Australian shredded scrap was offered at $415/t CFR, but buyer interest remained weak.
A Malaysian-origin shredded scrap cargo was reportedly offered at around $420/t CFR Chattogram. Freight estimates ranged from $65-75/t, with some sources indicating $75-80/t. These costs implied a delivered price of around $400-410/t CFR, up by approximately $15-25/t from the previous month’s reported range of $384-385/t CFR.
The bulk scrap market remained quiet as mills resisted higher prices. US-origin HMS 80:20 offers were reported at $410-412/t CFR, compared with $400-405/t CFR two weeks earlier, supported by firm transportation costs. Japanese suppliers largely adopted a wait-and-see approach ahead of the Kanto Tetsugen tender.

Domestic market
Bangladesh’s domestic steel market remained weak amid subdued demand and cautious buying. Billet prices were at BDT 70,000-71,000/t ($568-576/t) and local scrap at BDT 55,000-57,000/t ($446-463/t). Rebar prices stood at BDT 83,000-85,000/t ($674-690/t) in Dhaka and BDT 89,000-91,000/t ($723-739/t) in Chattogram.
As per industry reports, steel consumption has been affected by rising costs, financial constraints and the slowdown in public construction and infrastructure projects following the political changeover in August 2024. Industry representatives said sluggish economic and construction activity had weighed on the sector for nearly two and a half years.
The resumption of public infrastructure projects has raised hopes of a recovery. However, stronger construction activity must translate into higher steel sales before mills are likely to increase scrap procurement significantly.
Outlook
Bangladesh’s imported scrap market is expected to remain cautious in the upcoming days, as weak finished steel demand and firm freight rates continue to limit buying. Higher landed costs may widen the gap between buyers’ bids and sellers’ offers, particularly for imported bulk cargoes.
A sustained recovery will depend on stronger construction activity, improved steel consumption and better financial conditions for domestic producers.
Leave a Reply