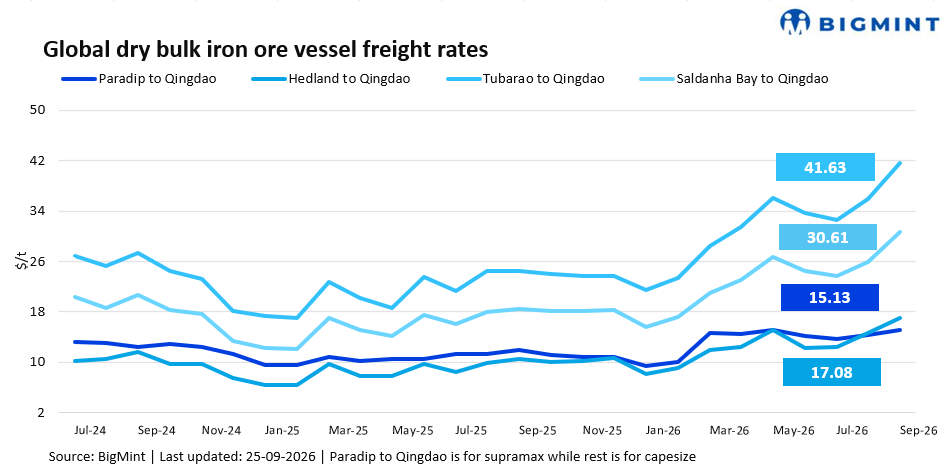
- Atlantic rates firm on stronger enquiries, high bunker costs
- Pacific sentiment remains subdued amid cautious Chinese buying
Dry bulk iron ore freight sentiment strengthened in the week ended 24 September, with Atlantic Capesize routes outperforming the Pacific. Brazil-China and South Africa-China rates increased on firmer cargo enquiries, tighter prompt tonnage and higher bunker costs, while Australia-China rates softened amid ample vessel availability and subdued fresh enquiries. Supramax sentiment remained relatively firm, supported by pre-holiday Chinese restocking and improved cargo enquiries.
A shipbroker stated, “Pacific Capesize rates remained under pressure as prompt tonnage availability outpaced fresh cargo demand.”
“Higher bunker prices are supporting owners’ rate ideas, although softer Chinese demand and weak steel margins could limit further upside”, another source highlighted.
Route-wise update

Factors influencing freight rates
- Baltic Dry Index rises 4% w-o-w on broad-based gains: The Baltic Dry Index (BDI) increased by 137 points, or 4% w-o-w, to 3,473 on 24 September from 3,336 on 17 September, led by a strong recovery in the Capesize segment. The BCI rose 283 points, or 5%, to 5,939, supported by firmer iron ore enquiries and improved Atlantic activity. Meanwhile, the BSI edged up 20 points, or 1%, to 1,782, with steady demand but relatively ample tonnage limiting gains.
- Brent crude futures rise w-o-w: Brent crude futures increased by $1.50/barrel (bbl) (1.4%) w-o-w to $104.94/bbl, from $103.44/bbl. Prices remained elevated as renewed attacks on Saudi Arabia revived Middle East supply concerns, while reports of potential US-Iran talks and a possible reopening of the Strait of Hormuz limited further upside.
- Bunker prices rise w-o-w: Singapore Very Low Sulphur Fuel Oil (VLSFO) bunker prices increased by $24/tonne (t) (2.7%) w-o-w to $904/t, from $880/t. The rise tracked firmer crude prices and renewed concerns over Middle East supply and shipping disruptions. However, improving Saudi export flows and diplomatic efforts to ease tensions provided some downside pressure.
- DCE iron ore futures decline w-o-w: The benchmark DCE iron ore contract fell by RMB 2/t (0.3%) w-o-w to RMB 713.5/t, from RMB 715.5/t. Prices remained under pressure from weak steel margins and subdued downstream demand, while expectations of improved mill restocking and China’s upcoming holiday-related buying provided some downside support.

Outlook
Near-term iron ore freight rates are expected to remain firm but rangebound, supported by healthy Atlantic cargo flows and relatively tight vessel availability. Stronger Brazil-China activity could lend support to Atlantic Capesize rates.
However, softer Pacific demand and cautious Chinese steel-market sentiment may limit further gains, keeping the overall market mixed with some volatility.
Leave a Reply