- Buying interest improves amid a narrow bid-offer gap
- Weak billet prices limit market recovery
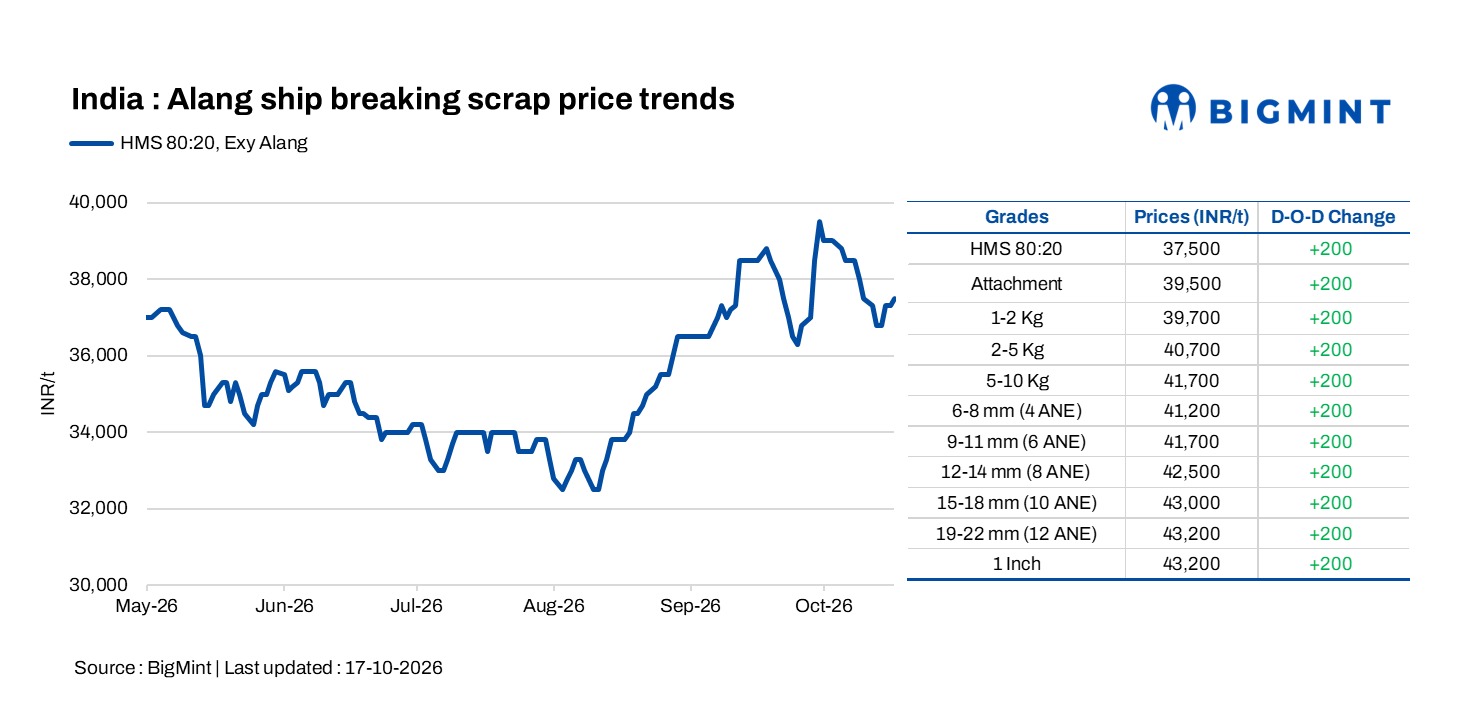
Alang’s ship-breaking melting scrap prices (HMS 80:20) declined by INR 1,000/tonne (t) w-o-w to INR 37,500/t ($394/t) ex-yard on 17 October 2026, despite a marginal d-o-d recovery of INR 200/t. Prices had risen in the previous week amid firmer rates in other consuming regions and supply constraints but subsequently corrected as demand for finished and semi-finished steel weakened.
Prices have stabilised within the INR 37,300-37,500/t range within this week, with buying interest improving over the past three days on better finished-steel demand. A shipbreaker told BigMint that daily sales from Alang were estimated at 5,000-7,000 tonnes. The gap between bids and offers remained narrow, indicating broadly aligned price expectations despite cautious market sentiment.
Gujarat market update

In Gujarat, Bhavnagar billet prices fell by INR 1,500/t w-o-w to INR 45,700/t delivered-at-plant (DAP) on 16 October, including a d-o-d decline of INR 500/t. Ahmedabad rebar prices decreased by INR 500/t w-o-w to INR 52,900/t ex-works, remaining unchanged d-o-d. Weak downstream demand continues to limit support for regional steel and scrap prices.
Mandi market update
In Mandi Gobindgarh, billet prices declined by INR 200/t d-o-d to INR 46,400/t DAP on 16 October. HMS scrap prices fell by INR 400/t to INR 37,100/t DAP, while rebar prices eased by INR 100/t to INR 52,100/t ex-works.
Continued weakness in regional steel benchmarks reflects subdued demand across the value chain. Alang’s modest d-o-d recovery has failed to offset the w-o-w decline, with further price direction dependent on sustained finished-steel demand and improved mill procurement.
Leave a Reply