- OMC auction sees strong participation amid supply constraints
- Weak pellet and steel prices limit broader market upside
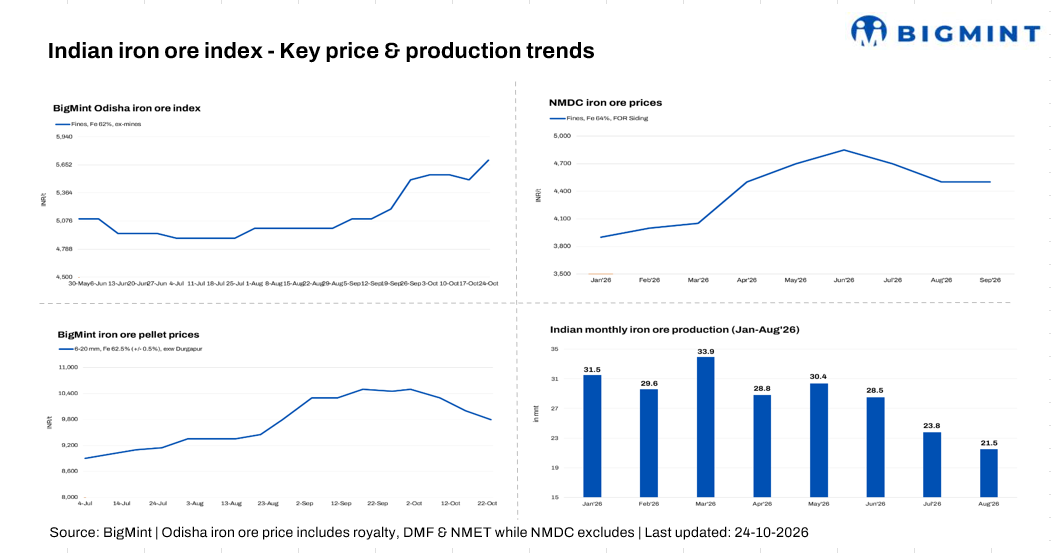
BigMint’s Odisha Fe 62% iron ore fines assessment rose by INR 150/tonne (t) ($1.5/t) w-o-w to around INR 5,650/t ($60/t) ex-mines in the week ended 24 October 2026. The increase followed a strong response to OMC’s fines auction on 22 October, with bids received for 1.41 million tonnes (mnt) out of 1.44 mnt offered.
Bids for fines increased by INR 50-350/t ($0.5-3.7/t) m-o-m despite lower base prices, supported by supply constraints following monsoon-related disruptions and action against illegal mining in Odisha. However, lower pellet prices capped further upside in bidding.
In contrast, OMC’s calibrated lump ore (CLO) auction saw the entire 0.731 mnt offered booked, although prices declined by INR 100-750/t ($1-7.9/t) m-o-m across most mines and grades. Daitri and Gandhamardhan prices fell by INR 550/t ($5.8/t) and INR 50/t ($), respectively, while Guali and Jilling’s 5-18 mm grades gained INR 1,050/t ($11/t) and INR 350/t ($3.7/t). Improved post-monsoon supply prospects and weaker sponge iron and billet prices weighed on the broader market, despite continued demand for select grades, BigMint noted.
As reported earlier by BigMint, OMC has lowered the base prices for both iron ore fines and calibrated lump ore (CLO). The revision comes amid continued weakness in eastern India’s steel market, with sponge iron and billet prices declining over the past week.
Base prices for fines have been reduced by around INR 150/t ($1.6/t) m-o-m, while cuts for calibrated lumps range from INR 50-450/t, depending on the grade and mine of origin.
“We will open the offers next week. Please note that previous offers will no longer be considered,” said a major iron ore miner.
A few market participants indicated that clearer price direction is likely to emerge after OMC’s auction, with other miners expected to open their offers next week. Meanwhile, market offers remain on hold as buyers and sellers await further price signals.
Rationale:
T1: Zero (0) deal for Fe 62% fines was recorded during the publishing window and assigned 0% weightage in the index calculation.
T2: BigMint received eighteen (18) offers and indicative prices under the T2 category (offers, indicative, and bids) in this publishing window. Sixteen (16) were taken into consideration and given 100% weightage. To check BigMint’s iron ore assessment, pricing methodology, document, click here.
Eastern India steel market remains subdued as pellet and C-DRI prices ease, rebar holds steady
- Pellet prices diverge as Durgapur hits near two-month low: Odisha’s Barbil Fe 62.5% (6-20 mm) pellet prices remained stable at INR 9,600/t ($101/t) LTW, while Durgapur prices declined by INR 200/t ($2/t) w-o-w to INR 9,800/t ($103/t) ex-works, hitting a nearly two-month low on 23 October. Weakness in Durgapur reflects subdued downstream demand and declining sponge iron and billet prices in eastern India, weighing on pellet realisations.
- Rourkela C-DRI prices edge lower amid subdued market sentiment: Rourkela C-DRI prices declined marginally by INR 50/t ($0.5/t) w-o-w to INR 29,500/t ($310.7/t) on 23 October, from INR 29,550/t ($311/t) a week earlier. The slight correction indicates a subdued market amid weak downstream steel demand and pressure on finished steel and billet prices. Buyers are likely to remain cautious with procurement, while further price movements will depend on steel market trends and changes in raw material costs.
- Rourkela rebar prices remain stable amid subdued market activity: Rourkela induction furnace (IF)-route rebar (12-25 mm) prices remained unchanged w-o-w at INR 56,000/t ($590/t) on 23 October 2026. Prices held steady amid cautious buying and subdued downstream demand, as market participants remained watchful of finished steel price movements and procurement trends.

Outlook
Odisha’s iron ore market is likely to witness mixed price trends in the near term, with improved post-monsoon availability expected to ease supply constraints, while recent action against illegal mining may limit the pace of recovery in dispatches. OMC’s latest auction indicated firm buying interest in fines, with bids received for nearly the entire volume offered, while lump prices remained mixed despite full booking. Market participants are likely to monitor upcoming miner offers and auction results for clearer price direction.
However, subdued downstream demand and recent declines in sponge iron, billet and pellet prices are expected to cap further upside in iron ore prices. Fines may find support from limited availability of select grades, while lump prices could remain under pressure if steel-sector demand stays weak. Overall, prices are likely to remain range-bound in the near term, with subsequent movements depending on mining activity, fresh supply, and changes in mill procurement demand.
Leave a Reply