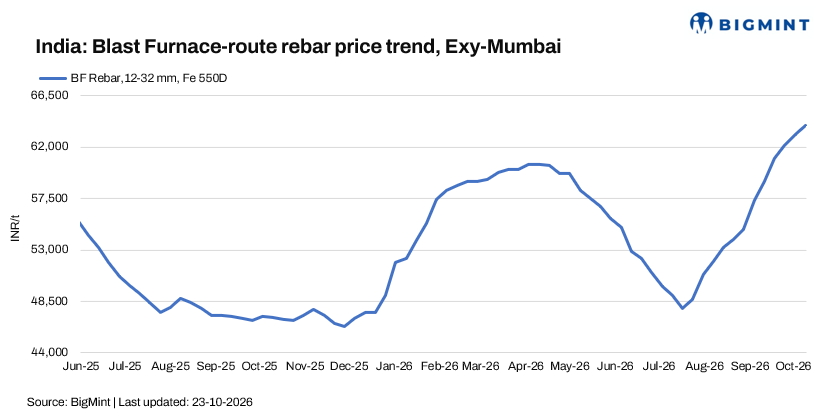
- Trade level rebar prices climbed by INR 700/t w-o-w in Mumbai.
- Improved supplies pressured on prices in South and Central India.
BigMint’s trade-level assessment of blast furnace (BF)-route rebar, covering distributor-to-dealer transactions, rose by INR 700/t ($7/t) week-on-week (w-o-w) to INR 65,000/t ($685/t) ex-Mumbai on 23 October 2026, amid a clear regional divergence. While South and Central India recorded declines of INR 500-1,000/t on improved supplies and festive-season liquidity concerns, tight material availability and steady project demand kept prices firm in select markets.
The market continued to draw strength from sustained project demand and limited material availability. However, the resumption of operations by a public sector steelmaker has improved rebar availability in South India, putting downward pressure on prices in the region. In contrast, limited prompt availability continued to support prices across western and northern India.
Distributors are bracing for liquidity constraints ahead of the upcoming holidays, which could trigger some price corrections at the trade level. Buyers are also turning cautious after successive price hikes, although project-related procurement continues to cushion the market.
In the project segment, workable prices were reported at INR 65,000-66,000/t ($663-673/t) landed. Procurement held up despite elevated prices, as several buyers moved to secure material ahead of the festive period.
With the latest increase, BF-route rebar prices have touched their highest levels in several years, driven by constrained supplies, project-related buying and successive mill price hikes. However, improving availability in South India and mounting liquidity pressures could limit further gains in the near term.
Key market developments
- 1. IF-route rebar: Mixed trend amid thin buying
IF-route rebar prices moved in a mixed pattern across major markets w-o-w, as regional sentiment and festival-related holidays shaped trading activity. Prices fluctuated within a narrow INR 100-600/t band, with both gains and losses recorded across regions but no decisive directional move. Buying remained subdued, with need-based procurement prevailing amid little improvement in ground-level demand. Mill inventories are hovering at 7-10 days, while order-booking visibility remains limited to 3-5 days.
The outlook remains positive but range-bound, as higher price levels continue to meet buyer resistance. Market participants are largely in wait-and-watch mode, restricting purchases to immediate requirements. Further price direction will hinge on raw material trends, regional sentiment and any recovery in underlying steel demand.
Meanwhile, the BF-IF rebar price spread in Mumbai widened further w-o-w to around INR 11,650/t ($123/t). IF-route rebar continues to dominate the Indian market, accounting for an estimated 65-70% share.
- 2. BF-route raw materials: Iron ore weakens, coking coal edges higher
Input costs for BF-route steelmakers remained mixed during the week, with softer domestic iron ore prices partly offset by firmer imported coking coal.
BigMint’s Odisha iron ore fines (Fe 62%) index declined by INR 200/t w-o-w to INR 5,300/t ($54/t) ex-mines as of 22 October.Meanwhile, premium hard coking coal (PHCC) prices rose by $2/t w-o-w to $292/t CNF Paradip.
The dip in iron ore prices offered some relief on the domestic raw material front, while the marginal uptick in coking coal costs provided an offset. Overall, raw material costs remain a secondary influence on near-term rebar pricing, with supply availability, project demand and distributor liquidity set to play a more immediate role.
India infrastructure: Major project awards
L&T secured INR 2,500-5,000 crore in building orders, while KPIL won INR 2,349 crore in domestic EPC contracts. Essar Ports bagged an INR 2,276 crore cargo terminal contract at Kandla, and NHAI received approval for INR 880.78 crore in highway and bridge works in Himachal Pradesh. Ceigall India’s subsidiary received a completion certificate for an INR 684 crore Haryana highway project. Other awards included civil construction, water supply and railway signalling contracts worth INR 47.40-200.02 crore each.
Outlook
BF-route rebar prices are likely to stay firm but could face near-term corrections as South Indian supplies improve, festive-season liquidity tightens and buyers remain cautious. Limited prompt availability and project demand will provide a floor, while weak retail offtake may cap further upside.
Leave a Reply