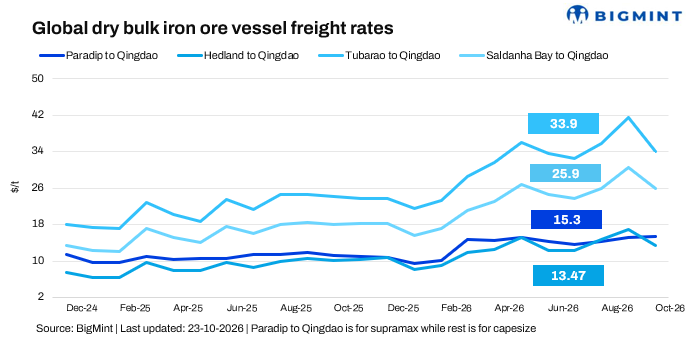
- Capesize rates rise across Pacific and Atlantic, while forward contracts weaken
- Rising brent and bunker prices lift vessel costs amid uncertain Chinese steel demand
Dry bulk iron ore freight sentiment strengthened across key Capesize routes in the week ended 22 October, supported by improved spot market activity and firmer cargo demand. Higher freight indications reflected better physical market conditions, with vessel owners maintaining firmer offers amid increased enquiries.
However, declining forward freight agreements (FFAs) indicated continued caution over the sustainability of the recovery. The divergence between spot and forward markets highlighted uncertainty over near-term demand and freight rate direction.
In contrast, India-China Supramax freight rates edged lower amid subdued buying interest and limited fresh enquiries. The mixed performance across vessel segments reflected stronger momentum in the Capesize market, while Supramax rates remained under pressure from weak cargo demand.
Route-wise update

Freight and commodity indicators
- Baltic Dry Index rises: The Baltic Dry Index (BDI) increased by 148 points, or 5.82%, to 2,693 on 22 October from 2,545 on 15 October, supported by a strong recovery in the Capesize segment. The Baltic Capesize Index (BCI) rose by 526 points, or 15.83%, to 3,848, while the Supramax Index (BSI) gained 34 points, or 1.83%, to 1,890. The sharp rise in Capesize rates supported by stronger iron ore shipping activity or tighter vessel availability.
- DCE iron ore futures edge lower: The benchmark DCE iron ore contract declined by RMB 7.5/tonne (t), or 1.10% w-o-w, to RMB 675/t on 23 October from RMB 682.5/t on 16 October. Prices remained under pressure from weak steel margins, subdued downstream demand and cautious mill buying, while uncertainty over China’s steel demand recovery continued to weigh on market sentiment.
- Bunker prices rise further w-o-w: Singapore Very Low Sulfur Fuel Oil (VLSFO) increased by $42.5/tonne (t), or 4.7% w-o-w, to $952.5/t on 23 October from $910/t on 16 October. The continued rise reflects higher crude oil prices and persistent supply concerns, adding to fuel-cost pressures for vessel operators and potentially supporting higher freight rates.
- Brent crude futures rise further w-o-w: December Brent crude futures climbed by $8.23/barrel (bbl), or 7.7%, to $114.71/bbl on 23 October from $106.48/bbl on 16 October. The increase reflects persistent geopolitical tensions and concerns over potential supply disruptions, which could push marine fuel costs higher, raise vessel operating expenses and add to dry bulk freight market volatility.

Outlook
Dry bulk freight sentiment has improved across key Capesize routes, supported by stronger physical assessments and a recovery in the Baltic Dry Index. However, declining Panamax rates, softer Capesize forward contracts and continued pressure on iron ore prices point to an uneven recovery. Supramax remains comparatively resilient, although gains are concentrated in specific trades.
Looking ahead, sustained improvement will depend on stronger Chinese steel demand, fresh iron ore cargo enquiries and tighter vessel availability. Rising bunker prices and geopolitical uncertainty are likely to keep operating costs and freight-market volatility elevated.
Leave a Reply