- Ample stocks, festive season slowdown limit fresh buying
- High mill offers make buyers unwilling to purchase large volumes
India’s coated flat steel prices declined week-on-week (w-o-w) during the week ended 22 October 2026, with galvanised plain (GP), pre-painted galvanised iron (PPGI), and bare galvalume (BGL) prices falling by INR 200-500/t, as per BigMint’s assessment. The decline was mainly due to weak demand, festive-season slowdown, and sufficient stocks available with traders and distributors.
Buyers remained cautious about fresh purchases as existing inventory was enough to meet immediate requirements. In addition, high price offers from major mills made buyers reluctant to purchase larger quantities, putting further pressure on market prices.
Price updates

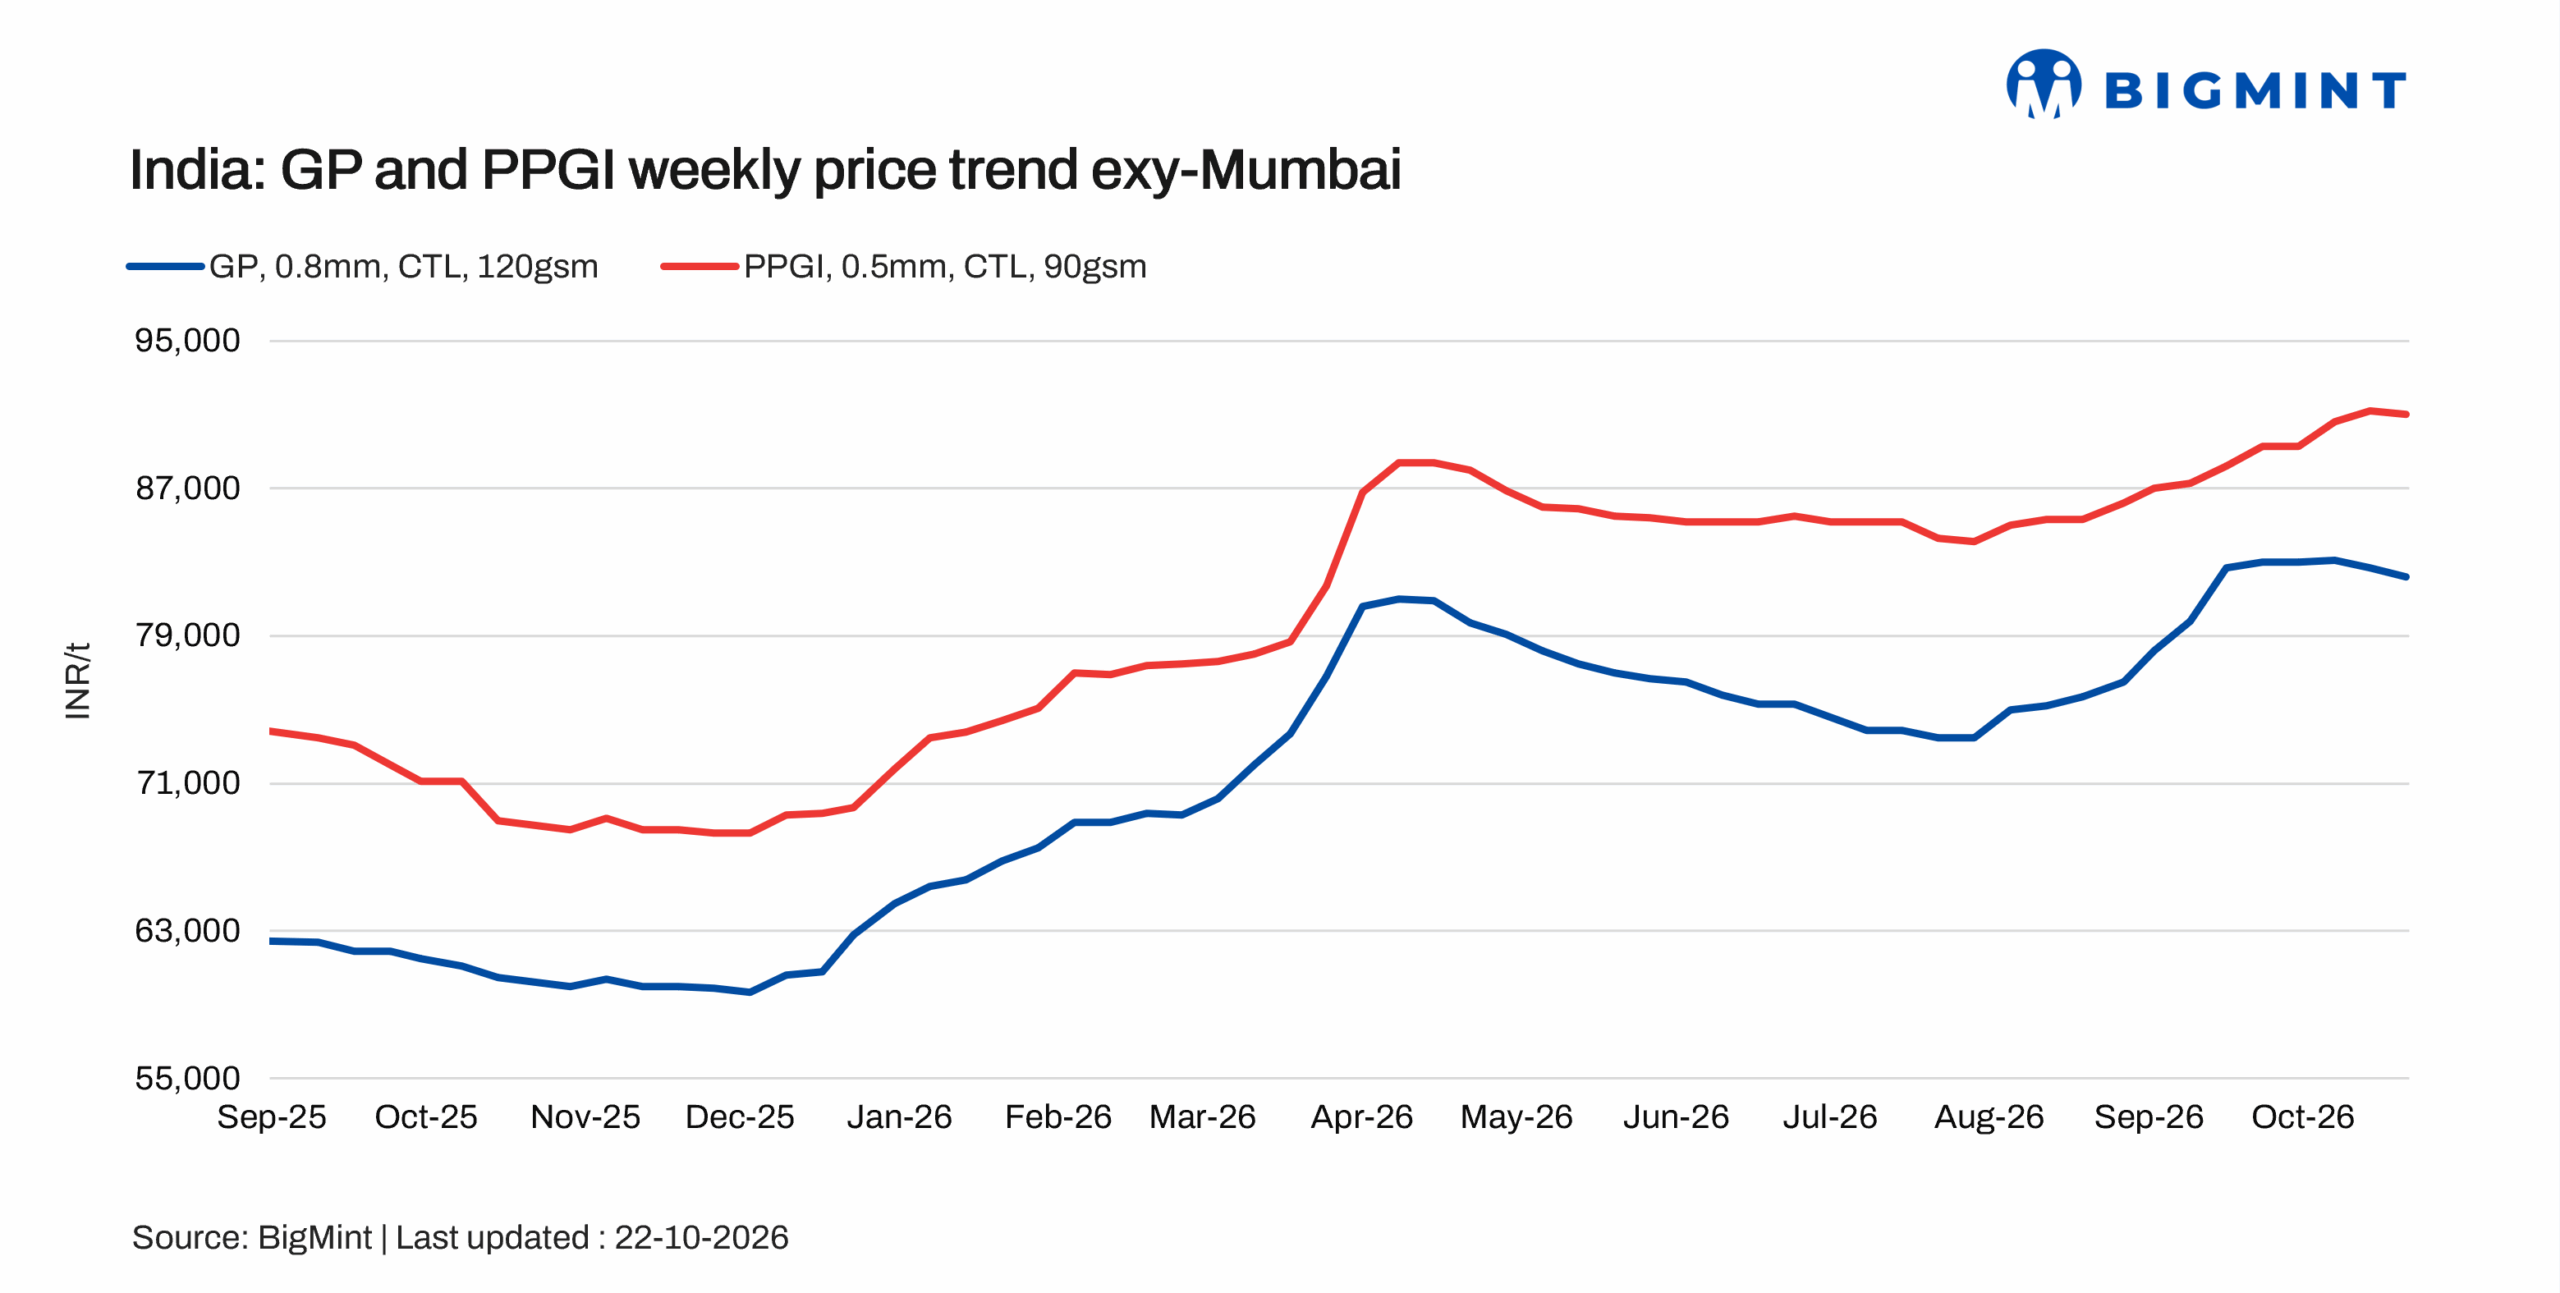
BigMint’s benchmark assessment for galvanised plain (GP) coil (0.8 mm/CTL, 120 GSM, IS 277) declined by INR 500/t w-o-w to INR 82,200/t ex-Mumbai as of 22 October 2026, from INR 82,700/t on 15 October 2026.
Pre-painted galvanised iron (PPGI) (0.5 mm/CTL, 90 GSM, IS 14246) prices decreased by INR 200/t w-o-w to INR 91,000/t ex-Mumbai, compared with INR 91,200/t in the previous assessment.
Bare galvalume (BGL) (0.5 mm/CTL, 1220 mm, AZ150, IS 15961) prices fell by INR 400/t w-o-w to INR 93,500/t ex-Mumbai, from INR 93,900/t on 15 October 2026.
Raw material prices

India’s zinc ingot (99.99%) prices increased by INR 500/t week-on-week (w-o-w) to INR 436,500/t ex-Delhi as of 22 October 2026, compared with INR 436,000/t in the previous assessment. The increase was marginal, with zinc prices remaining largely stable during the week.
Meanwhile, BigMint’s benchmark assessment for hot-rolled coil (HRC) (2.5-8 mm/CTL, IS 2062, Grade E250 BR) declined by INR 300/t w-o-w to INR 63,700/t ex-Mumbai as of 22 October 2026, from INR 64,000/t in the previous assessment.
Cold-rolled coil (CRC) (0.5 mm/CTL, IS 513, CR1) prices also decreased by INR 400/t w-o-w to INR 74,900/t ex-Mumbai, compared with INR 75,300/t previously.
Market updates
The coated flat steel market remained slow during the week, as festive-season activity and weak demand limited fresh buying. Traders and distributors were already holding sufficient stocks, so there was little need to purchase additional material. This kept trading activity low and put pressure on sellers to offer more competitive prices.
High offers from major mills also affected buying decisions. Many buyers were unwilling to purchase material at current price levels, particularly when they already had enough inventory to meet immediate demand. As a result, purchases were mostly limited to urgent requirements, while larger orders remained on hold.
GP prices recorded the sharpest decline among the three products, falling by INR 500/t, while PPGI and BGL prices decreased by INR 200/t and INR 400/t, respectively. This shows that weak demand and sufficient stock availability affected the broader coated steel market, rather than being limited to a single product.
On the raw material side, HRC and CRC prices declined by INR 300/t and INR 400/t, respectively, while zinc prices remained stable. However, the main reasons for the decline in coated steel prices continued to be weak demand, high inventory levels and limited buying interest.
Outlook
Coated flat steel prices may remain under pressure in the near term if demand stays weak and traders continue to hold sufficient stocks. Sellers may need to adjust prices to attract buyers, especially while high mill offers discourage fresh purchases.
A recovery in prices will largely depend on an improvement in demand after the festive period and the reduction of existing inventories. Until buying activity improves, market participants are likely to continue purchasing only as needed, limiting the scope for a sustained price increase.
Leave a Reply