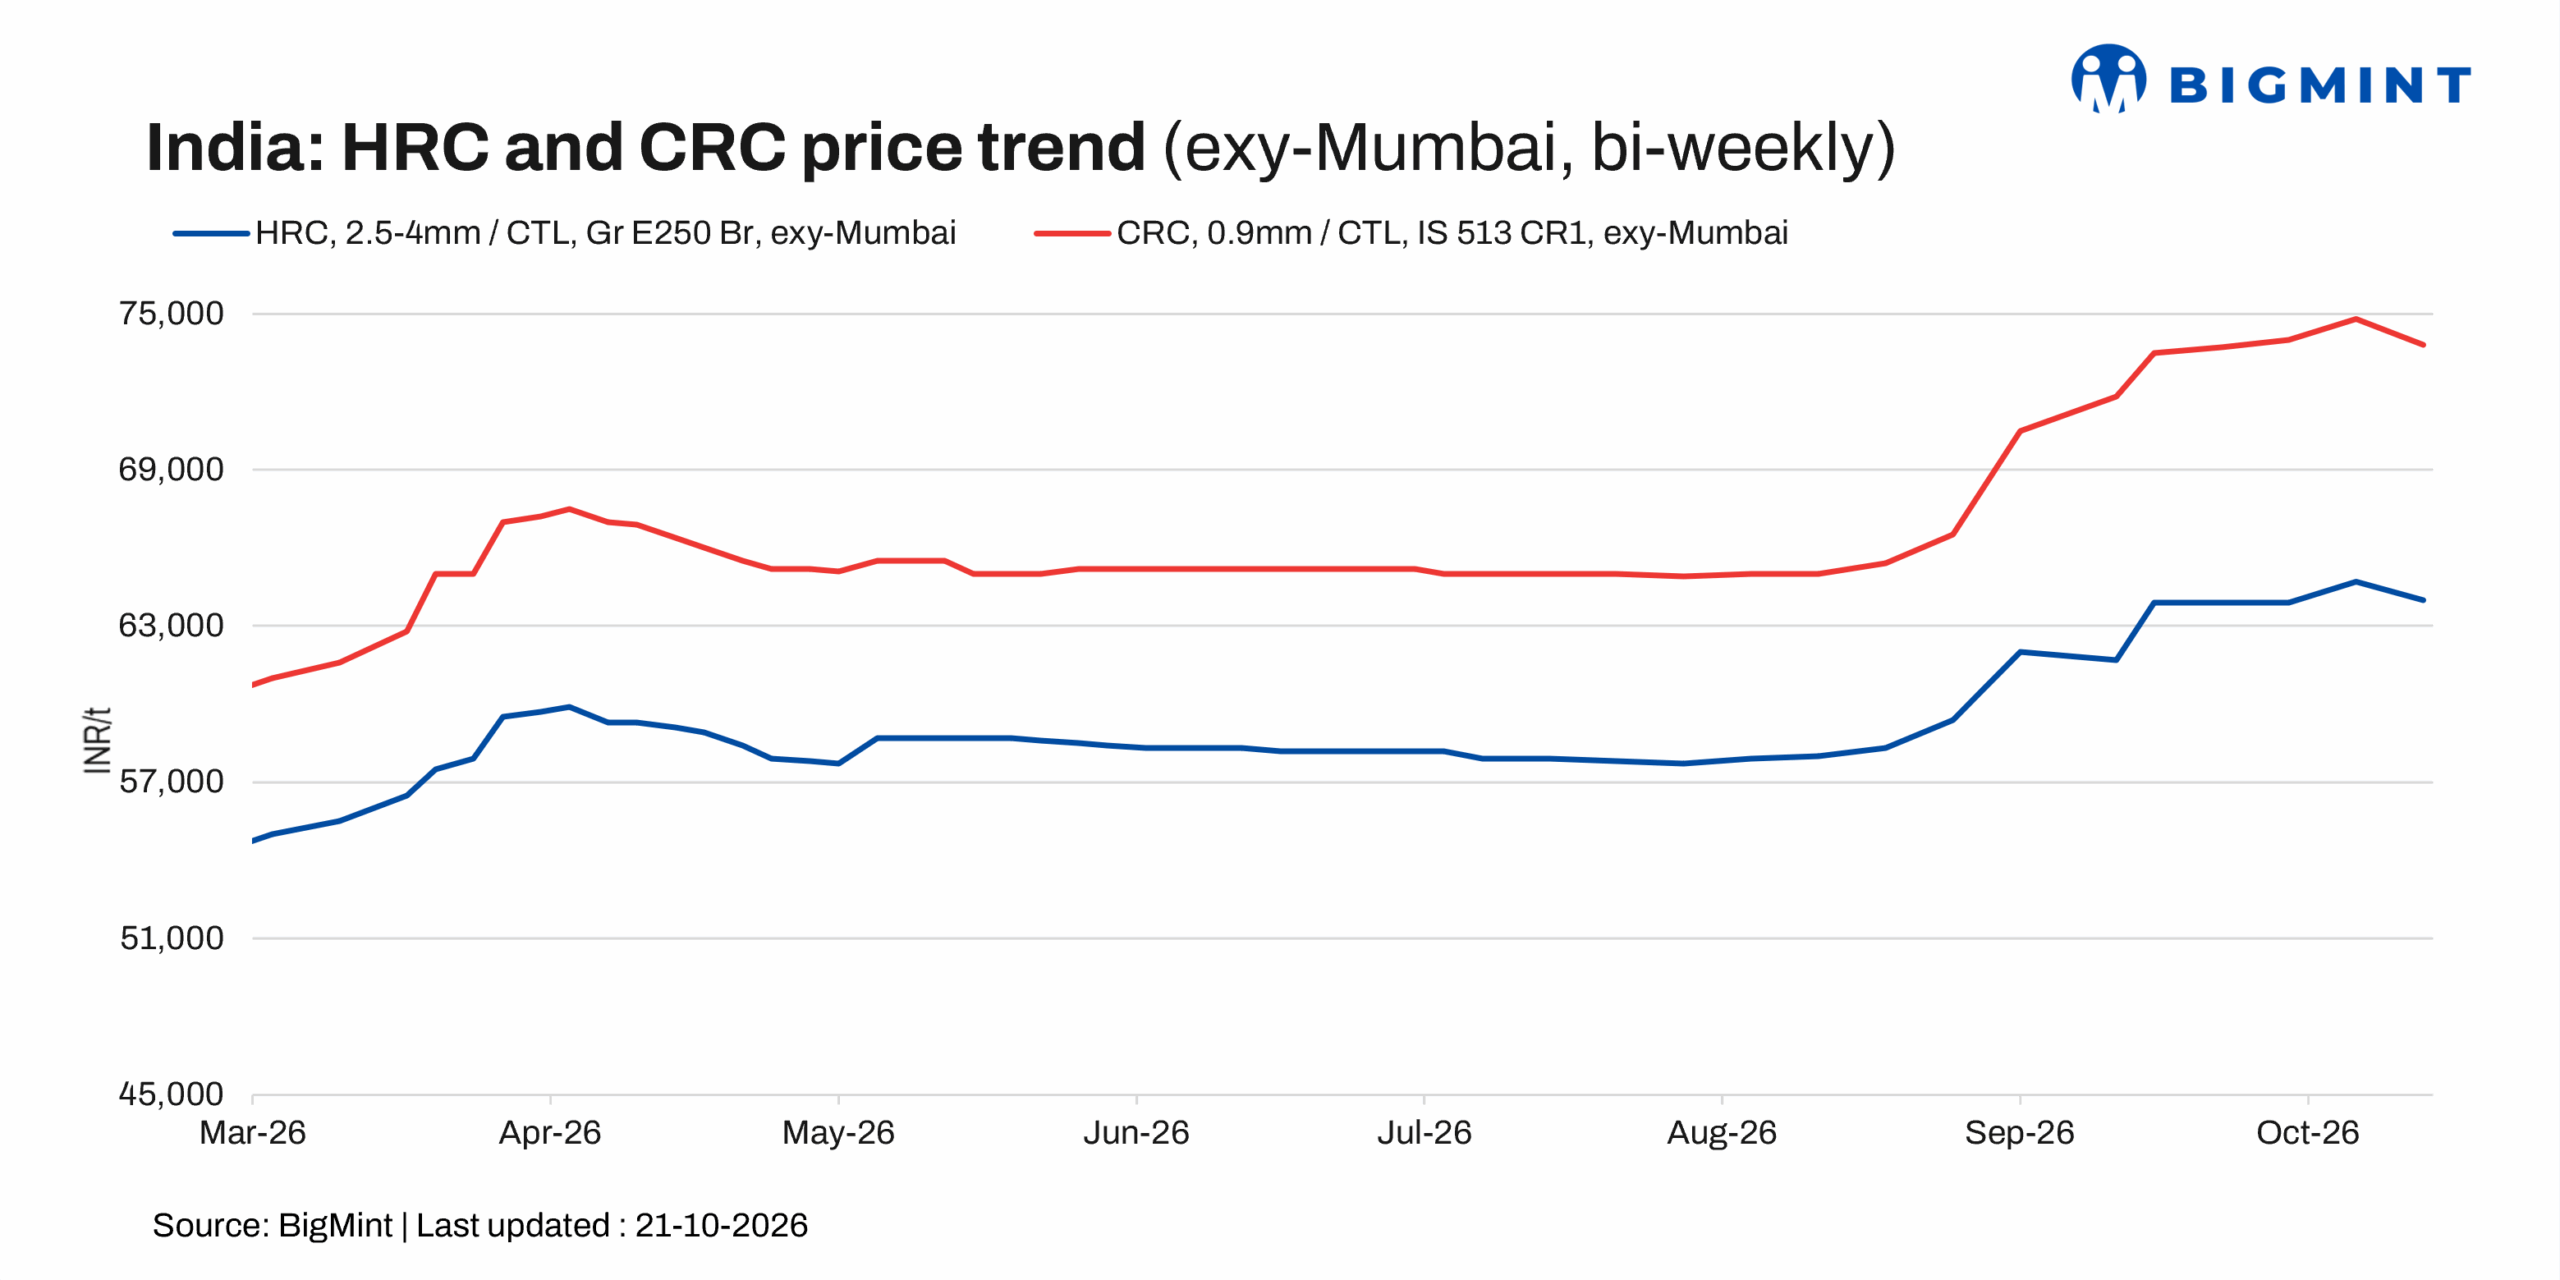
- Festive slowdown, liquidity constraints curb trading activity
- Moderate inventory levels limit restocking across key markets
India’s trade-level hot-rolled coil (HRC) prices declined by INR 200-700/t w-o-w, as per BigMint’s latest assessment on 19 October 2026, amid relatively slow demand and cautious buying activity across major markets.
Trade-level cold-rolled coil (CRC) prices also witnessed a decline of INR 300-900/t w-o-w across major markets, reflecting subdued market sentiment and limited buying interest.
BigMint’s bi-weekly benchmark assessment for Mumbai HRC (2.5-8 mm/CTL, IS 2062, Grade E250 BR) decreased by INR 300/t w-o-w to INR 63,700/t ex-Mumbai as of 19 October 2026, from INR 64,000/t in the previous assessment on 13 October.
Meanwhile, Mumbai CRC (0.90 mm/CTL, IS 513, CR1) was assessed at INR 73,400/t ex-Mumbai as of 19 October 2026, down INR 400/t w-o-w from INR 73,800/t on 13 October.

Market updates
HRC and CRC trade-level prices declined across major markets amid sluggish demand and a slowdown in buying activity ahead of the festive period. Market participants reported that purchases remained largely need-based, with buyers procuring material mainly to meet immediate requirements rather than building inventory.
Liquidity constraints and limited cash flow continued to weigh on market sentiment, as subdued sales and cautious procurement affected working capital availability among traders and distributors. As a result, sellers offered discounts in some markets to liquidate stocks and generate cash flow, putting downward pressure on prices.
Inventory levels remained moderate across most markets, with buyers and traders maintaining cautious stocking strategies amid uncertain demand. The combination of festive-season slowdown, need-based purchasing and liquidity pressures continued to limit trading activity and weigh on HRC and CRC prices.
Trade activity
Import volumes : India’s bulk HRC imports stood at 105,163 tonnes (t) as on 16 October 2026, with a further 101,118 t expected to arrive by the end of October. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.

Export volumes: India’s bulk HRC exports stood at 45,530 t as of 16 October 2026. Another 65,000 t are expected to be shipped by next week.
Outlook
HRC and CRC prices are expected to receive support from anticipated price increases by major domestic mills in the coming week. One of the major domestic mills has already increased prices amid production disruptions caused by scheduled maintenance, which may tighten supply and provide further support to market prices. However, sluggish demand, need-based buying and liquidity constraints in the trade may limit the extent to which mill price hikes are reflected in spot-market transactions. Market participants are likely to monitor further mill announcements, supply conditions and post-festive demand trends to assess the sustainability of any price increase.
Leave a Reply