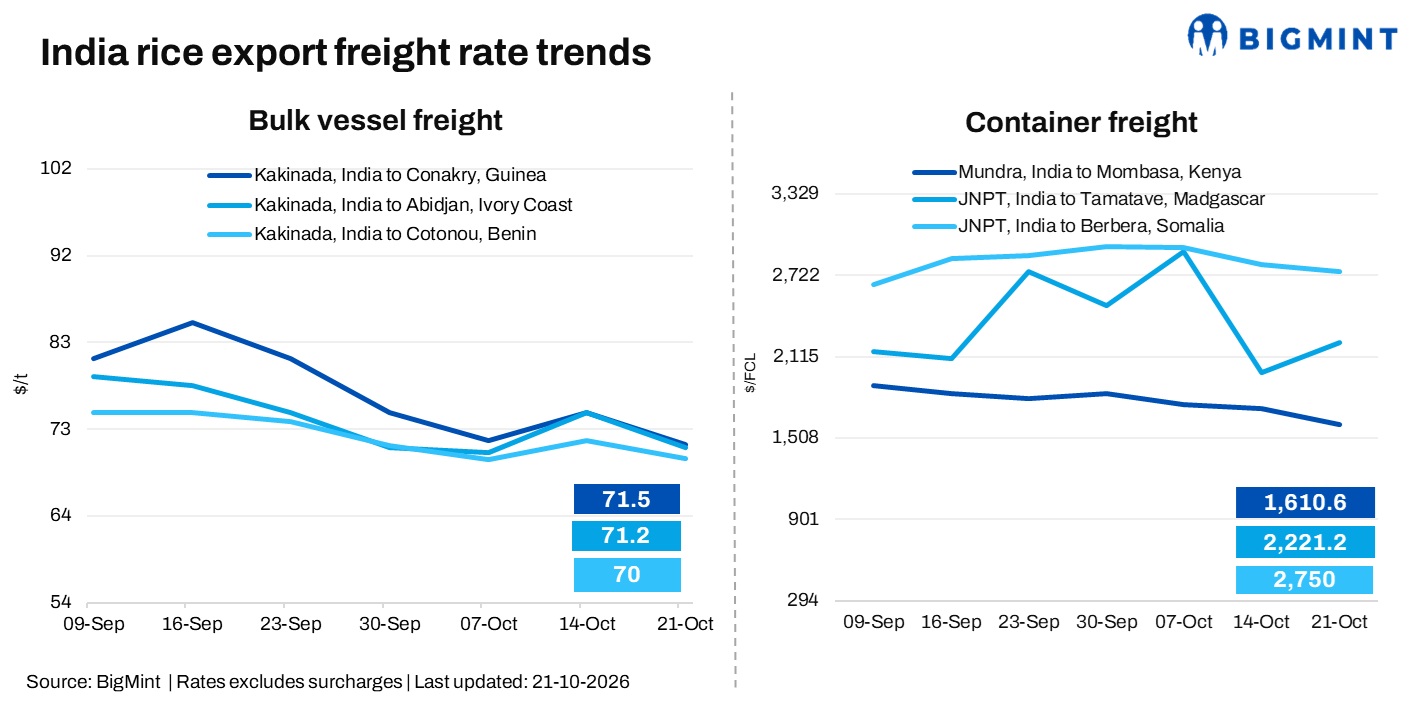
- West African bulk freights ease despite persistent port congestion
- East African container rates remain firm amid selective bookings
India’s rice freight market showed mixed trends in the week ended 21 October, as slower rice sales weighed on West African bulk freight sentiment, while East African container rates remained largely stable at elevated levels. Port congestion and higher vessel operating costs continued to support bulk freight offers, but cautious chartering limited market momentum. In the container segment, exchange-rate volatility and selective buying kept booking activity subdued.
A shipbroker told BigMint, “Exchange-rate volatility and persistent freight costs are making it difficult for exporters to maintain margins. Buyers are taking longer to confirm shipments, keeping booking activity selective.”

West African bulk market faces near-term pressure
Freight rates to West Africa remained in the $70-75/t range, with the market broadly stable despite softer buying interest. Congestion at key destinations continued to prolong vessel turnaround times, while firm vessel offers and higher operating costs limited the scope for significant rate corrections.
A shipbroker said, “Port congestion continues to support freight offers, but slower cargo enquiries and cautious chartering are limiting fresh fixing activity.”
A charterer said, “The market remains stable, and we expect activity to improve after Diwali as rising rice production in India and stronger demand encourage fresh cargo enquiries.”
East African containers remain largely stable but bookings lag
Container sentiment remained firm across East African destinations, although actual booking activity was limited. Market participants continued to exchange rate enquiries and offers, while selective buying and fluctuating exchange rates delayed some decisions.
A shipbroker said, “East African container rates remain at elevated levels, but most activity is limited to rate enquiries and negotiations. Buyers are cautious, and fresh bookings remain selective.”
Route-specific constraints also shaped market conditions. Empty-container imbalances and port delays continued to affect Mombasa, while limited direct mainline services and trucking constraints supported freight offers to Madagascar. Berbera remained exposed to Red Sea-related security and war-risk concerns, adding uncertainty to shipping decisions.
Rice prices increase as buyers await new-crop arrivals
BigMint’s assessment for non-basmati parboiled rice (IR-64 5% PB), FOB Kakinada, increased w-o-w to $376-378/tonne (t) as on 21 October 2026 from $375/t on 14 October. Delayed new-crop arrivals continued to support prices, while buyers remained cautious about crop availability and overall shipment costs.
A rice trader said, “Non-basmati prices remain firm amid delayed new-crop arrivals. The basmati market remains subdued, but strong demand against limited supply could support a recovery in the coming weeks.”

Outlook
West African bulk freight sentiment could strengthen after Diwali if fresh cargo enquiries translate into actual fixtures, with port congestion and firm vessel offers providing underlying support. East African container rates are likely to remain elevated but route-specific, as space availability, exchange-rate volatility and cautious booking decisions continue to shape the market.
Leave a Reply