- Court stay on electricity tax reforms clouds import incentives
- Subdued construction activity weighs on domestic steel demand
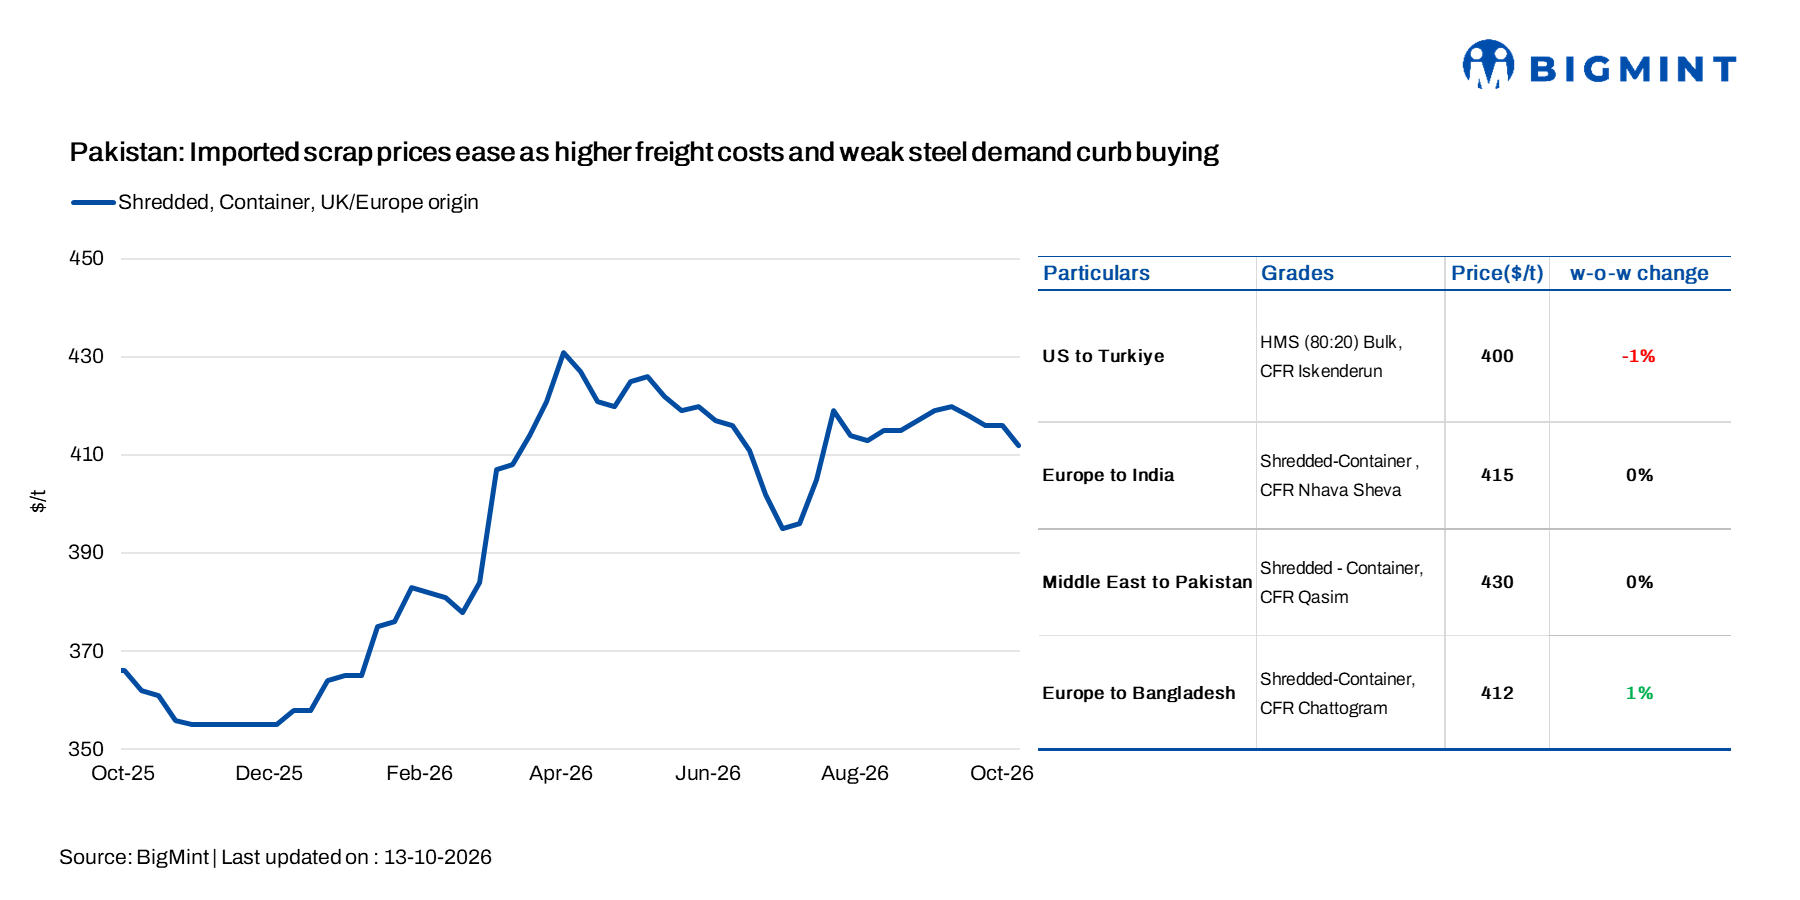
Pakistan’s imported ferrous scrap market remained subdued during the week ended 13 October, with higher freight rates, vessel delays and limited port space discouraging sellers from offering material. Import demand remained moderate as weak finished steel consumption and low construction activity kept buyers cautious. Market participants reported few fresh offers, while suppliers increasingly considered alternative destinations offering better returns.
BigMint assessed Europe-origin shredded scrap at $412/t CFR Qasim, down by $4/t w-o-w.
Market scenario
A UAE-based trader said European-origin shredded scrap offers fell to $413-415/t CFR Qasim from $420-425/t earlier, while bids stood at $410-412/t. HMS 80:20 offers were reported at $385-395/t CFR against bids of $380-385/t. However, sellers have shown little fresh interest in the Pakistani market as higher freight costs and shipping constraints weigh on trade.

A Peshawar-based mill participant said the revised energy-linked tax system, which offers a lower electricity tax of PKR 5/unit to manufacturers using more than 70% imported scrap compared with PKR 30/unit for those using local scrap, could support imported scrap demand. However, the new tax rule is currently stayed by the court, with the next hearing scheduled for 20 October. The participant said a final decision could take another six to eight months. Meanwhile, elevated freight costs and logistical challenges continue to constrain import activity.
Domestic market
Pakistan’s domestic steel market remained weak, with limited construction activity and subdued finished steel demand weighing on trading sentiment. Domestic scrap prices stood at PKR 132,000-134,000/t ($477-484/t), while billet prices were reported at PKR 214,000-215,000/t ($773-777/t) and rebar at PKR 234,000-236,000/t ($845-853/t). These levels were slightly below the previously reported ranges.

Mill utilisation remained low at around 30-35%, weak finished steel demand and limited production activity. Low utilisation continued to constrain mills’ scrap procurement appetite.
Outlook
Pakistan’s imported scrap market is expected to remain cautious in the upcoming days. Higher freight rates, vessel delays and port-space constraints are likely to restrict fresh offers, while weak finished steel demand may limit buyers’ willingness to accept higher prices. Although market participants believe prices may be approaching a bottom, a sustained recovery will depend on improved steel demand, smoother logistics and more competitive import offers.
Leave a Reply