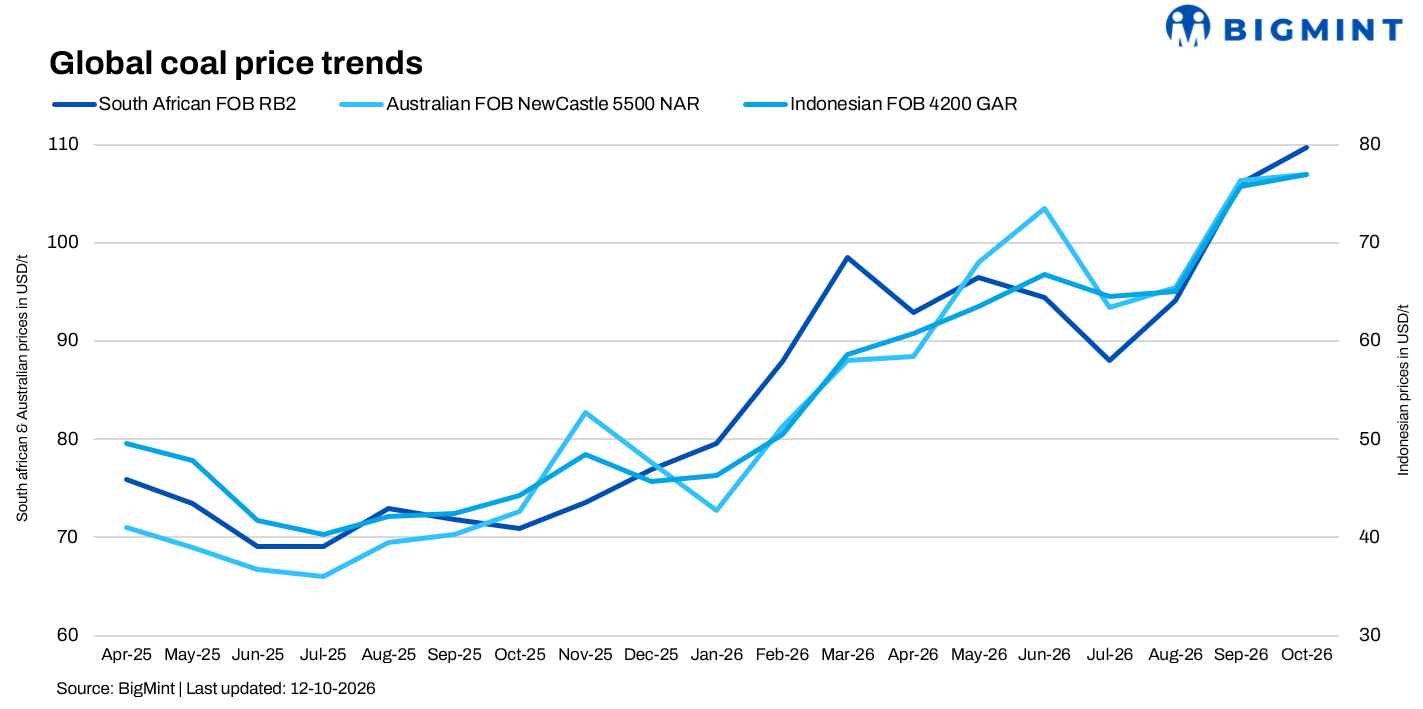
- Australian mid-CV trades rise; Indonesian export prices edge higher
- Indian buying remains selective despite depleted power plant stocks
Asian thermal coal markets showed selective firmness in the week ending 10 October 2026. Australian 5,500 NAR transactions strengthened, Indonesian 4,200 GAR cargoes traded marginally higher, and Chinese domestic markers recovered from the previous week’s dip.
However, the market remained uneven. Indian portside Indonesian prices softened, while South African coal retained support from limited prompt availability and higher replacement costs. Buyers continued to balance fuel security against weak downstream margins and expensive replenishment.
Weekly price comparison

Source: BigMint Market Assessments *The preceding week’s Australian transaction was unconfirmed. Indonesian observations cover October and/or November cargoes and are not an exact shipment-period match. The South African rows use the later 10 October roundup; the separate 8 October assessment reported South African 5500 NAR at INR 14,300/t at both ports.
Australia: Mid-CV trades provide clearest price signal
Newcastle 5,500 NAR coal recorded confirmed November Panamax transactions at $111/t and $112/t FOB, against a $110/t bid and $113/t offer.
The transactions were also above confirmed November deals at $109/t in the week ending 25 September, providing evidence of firmer traded prices.
For 6,000 NAR coal, buying indications strengthened, but no confirmed fixed-price transaction was reported in the latest weekly observations. January bids reached $150.50/t against offers starting at $154.50/t. December bids reached $146.25/t against a $147.25/t offer.
These indications suggest closer buyer-seller expectations for selected delivery periods. They do not establish a common clearing price across November, December and January cargoes.
Indonesia: Export firmness contrasts with Indian buying resistance
Confirmed 4,200 GAR transactions were reported at $80.50/t for October and $80.75/t for November Panamax cargoes. A November offer of $83/t was unconfirmed.
The directly labelled comparison with the preceding week’s $80/t transaction indicates modest firmness. For 3,800 GAR coal, a November offer stood at $70/t, compared with a preceding-week transaction stated as 3,400 NAR at $68/t.
Early-week market commentary described low river levels restricting Indonesian logistics. This supports the possibility of constrained cargo availability, but does not quantify export losses or establish an improvement timetable.
Indian buyers nevertheless remained cautious. Expensive Indonesian replacement cargoes did not translate into stronger portside purchasing, demonstrating that export-market firmness and local demand can diverge.
China: Domestic prices recover, post-holiday demand remains a watchpoint
The Qinhuangdao (QHD) 5,500 NAR marker increased $0.78/t to $148.05/t on 9 October, while its RMB equivalent rose from RMB 992/t to RMB 997/t.
The dollar marker reached its highest level in the supplied six-week series. The movement was modest, however, compared with the sharp early-September increase.
Domestic coastal freight eased. QHD-Shanghai fell from $3.58/t to $3.43/t w-o-w, while QHD-Guangzhou declined from $6.30/t to $6.02/t. Lower freight partially cushioned higher origin prices for buyers.
Post-holiday restocking remains a potential source of support, rather than a confirmed demand surge. The supplied 9 October observations contain no Chinese tender offers, so tender activity cannot validate that expectation.
India: South African coal stays firm, Indonesian grades soften
South African coal retained support from scarce prompt grades. Reportedly, there were no RB2 stocks at Vizag, while selected RB3 cargoes were in limited availability. Import offers were around $135-136/t for 5500 NAR and $115-116/t for 4800 NAR.
Indonesian portside prices moved differently. Besides Kandla, 4,200 GAR coal declined INR 50/t to INR 9,750/t at Vizag. The 5,000 GAR grade remained stable at INR 11,800/t at Kandla and INR 11,700/t at Vizag.
Covered Indian port inventories rose marginally to 18.44 mnt during 27 September-3 October, including 13.07 mnt of non-coking coal. The increase was concentrated at Mundra, while other covered ports collectively drew down stocks.
Consequently, national inventory totals offered limited reassurance about the availability of a specific grade at a particular port.
Fuel security needs support Indian demand, but margins constrain purchases
Indian power-plant stocks stood at approximately 20.62 mnt on 8 October, with 87 plants classified as critical. This creates potential replenishment demand, but does not automatically translate into imported-coal orders.
Domestic auction premiums remained elevated, while washed coal reached INR 10,100/t FOR Raipur. Weak sponge iron markets limited consumers’ ability to absorb higher fuel costs.
Cement producers also examined alternative blends as petcoke and US high-CV coal remained expensive. Substitution depended on ash, sulphur, heat value and plant requirements.
Freight signals were mixed: Australia-Paradip Panamax rates rose to $24.60/t, while Richards Bay-Paradip declined to $24.10/t. Higher bunker costs maintained pressure on voyage economics.
BigMint assessment: Selected export grades remain firm, but buying is far from uniformly strong. Indonesian cargo availability, Chinese post-holiday procurement, and Indian grade-specific stocks will determine whether supply pressure generates sustained fresh orders. For Indian consumers, delivery certainty and fuel suitability remain as important as headline prices.
Leave a Reply