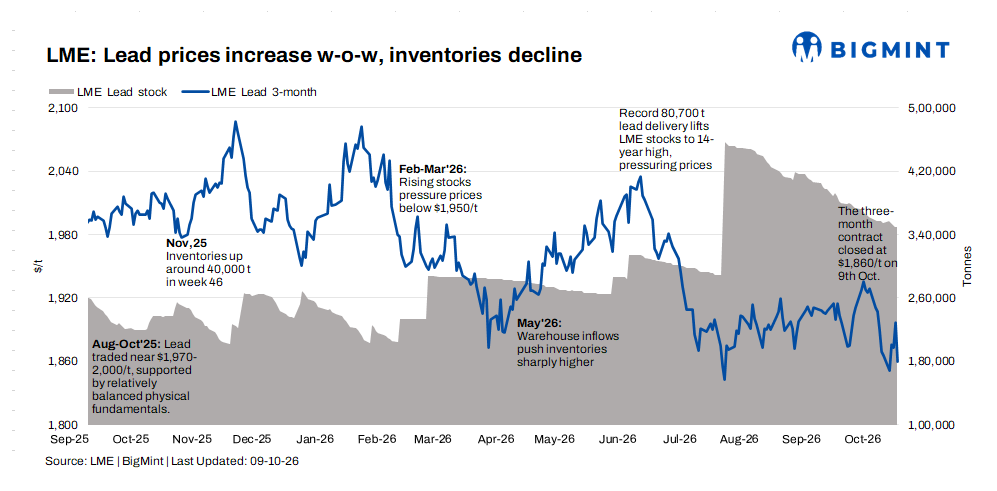
- LME lead rises 1% w-o-w as stocks fall 7,050 t
- MCX lead gains as HZL revises benchmark higher
London Metal Exchange (LME) lead prices recovered during the week ended 9 October, supported by continued inventory drawdowns. Domestic MCX lead prices also increased, while Hindustan Zinc Ltd (HZL) raised its lead benchmark in the latest revision.
LME lead cash-settlement prices increased 1.1% to $1,847/t on 9 October from $1,827/t on 2 October. The three-month contract rose 1% to $1,883.50/t from $1,865/t.
Meanwhile, LME lead inventories declined by 7,050 t, or 2%, to 347,125 t from 354,175 t over the same period.
LME inventories continue to decline
LME lead stocks continued their downward trend, falling from 354,175 t on 2 October to 347,125 t on 9 October. Inventories also declined by 10,225 t from 357,350 t on 30 September.
Despite the continued drawdown, stocks remained above 340,000 t, indicating that exchange inventories were still substantial. The decline provided support to prices, although its impact remained moderated by the availability of stocks.
The cash-to-three-month spread stood at $36.50/t on 9 October, compared with $38/t on 2 October, with the three-month contract trading above cash settlement.
MCX lead gains as open interest rises
MCX lead prices increased during the week. The 30 October contract closed at INR 195.20/kg on 9 October, compared with INR 192.20/kg on 1 October, gaining 1.6%.
Open interest rose from 520 lots on 1 October to 582 lots on 9 October, an increase of 11.9%, indicating higher market participation alongside the price recovery. However, open interest eased from 608 lots on 8 October, suggesting some reduction in outstanding positions on the final trading day.
HZL lead benchmark recovers
Hindustan Zinc Ltd (HZL) raised its lead benchmark by INR 1,100/t on 8 October to INR 212,600/t.
The increase followed a INR 4,000/t reduction on 5 October, when the benchmark was cut to INR 211,500/t from INR 215,200/t on 1 October. The latest revision partially reversed the earlier reduction.
Outlook
BigMint expects LME lead prices to remain range-bound in the near term, with declining inventories providing support, while the continued availability of exchange stocks and uncertainty over downstream demand could limit the upside.
LME lead prices gained around 1% during the week, while inventories fell by 7,050 t to 347,125 t. However, the cash-to-three-month spread remained in contango, indicating that the nearby market was not showing the backwardation seen during periods of more immediate supply tightness.
In India, MCX lead prices strengthened alongside higher open interest, while HZL’s latest benchmark increase followed a sharp reduction earlier in the week.
Market participants will monitor LME inventory movements, Chinese battery-sector demand, lead-ingot procurement, and domestic benchmark revisions for further direction.
Leave a Reply