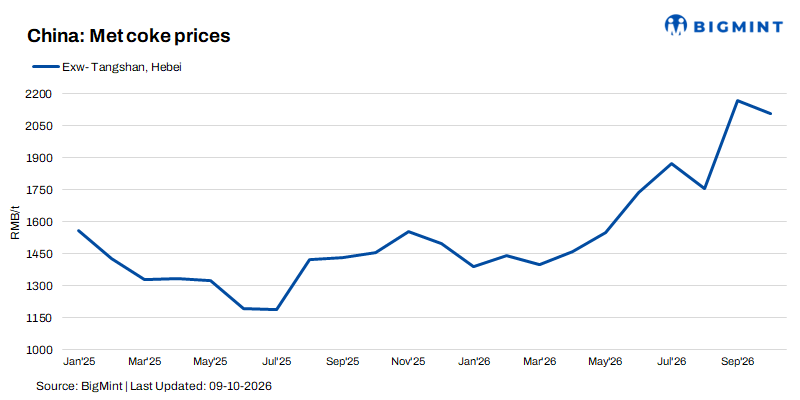
- China’s met coke prices fell by Yuan 100-110/t amid weak steel margins and subdued demand
- Normal production and rising inventories may trigger further price cuts
China’s first round of metallurgical coke price cuts officially took effect on October 1, after two leading steel mills announced they would lower their purchase prices. This snapped the uptrend lasting since mid-August, indicating more downside room after the country’s National Day holiday over October 1-7.
The Mysteel Coke Index (MCI) CDQ, which tracks China’s national prices for dry-quenched quasi-first-grade met coke, stayed unchanged from the previous session at Yuan 2,323.3/tonne ($346.5/t) on September 30, the last workday before the holiday. The MCI CWQ, tracking wet-quenched quasi-first-grade met coke, also held steady at Yuan 2,131.6/t, with both prices including VAT.
On September 30, Hebei Iron and Steel Group (HBIS) and Rizhao Steel Holding Group (Rizhao Steel) — the country’s two leading steel groups — announced they would cut their met coke purchase prices by Yuan 100-110/t, effective October 1. The moves, widely seen as a key signal for the direction of China’s coke market, set the stage for the first round of nationwide met coke price cuts.
Following the latest adjustments, HBIS is paying Yuan 2,230/t and Yuan 2,655/t for stamp-charged wet-quenched first-grade met coke (CSR≥65%) and top-charged dry-quenched first-grade met coke, respectively, on a DDP basis, inclusive of VAT.
Rizhao Steel’s met coke purchasing prices now stand at Yuan 2,045/t and Yuan 2,355/t for wet- and dry-quenched quasi-first-grade met coke (CSR≥60%), respectively, while the price of second-grade product (CSR≥58%) stands at Yuan 1,985/t. All three prices are for stamp-charged coke on a DDP basis, inclusive of VAT.
In parallel, the latest prevailing offers for dry-quenched quasi-first-grade met coke in Lvliang, North China’s Shanxi province, fell to Yuan 2,180-2,190/t on October 8, while those for dry-quenched first-grade material stood at Yuan 2,290-2,300/t, both on an EXW basis, inclusive of VAT, Mysteel learned.
The downturn came amid severe losses among steelmakers, prompting them to step up cost-cutting efforts. Although lower raw material prices helped narrow their losses somewhat from pre-holiday levels, mills remained under substantial financial pressure and continued to buy coke mainly on an as-needed basis.
Coking plants largely maintained normal production during the holiday, with operating rates showing no significant changes and stocks rising slightly in some regions, Mysteel learned. Market sources indicated that the met coke market is likely to see another one to two rounds of price cuts in the near term.
Coke futures moved higher on September 30. On the Dalian Commodity Exchange (DCE), the most-traded coke contract for next January delivery closed the daytime trading session at Yuan 1,958.5/t, up 0.56% from the previous session.
Portside met coke prices were stable on September 30, although trading activity remained subdued. Mysteel assessed wet-quenched quasi-first-grade coke (CSR 60%) and first-grade coke (CSR 65%) at Yuan 1,930/t and Yuan 2,030/t ex-stock Rizhao port, respectively, both unchanged from the previous session and inclusive of VAT. Meanwhile, the price of dry-quenched quasi-first-grade coke also stood flat at Yuan 2,070/t.
Note: The article is published as part of a content sharing agreement between Mysteel Global and BigMint.
Leave a Reply