- Weak steel demand weighs on raw material purchases
- Low-grade demand remains weak amid ample availability
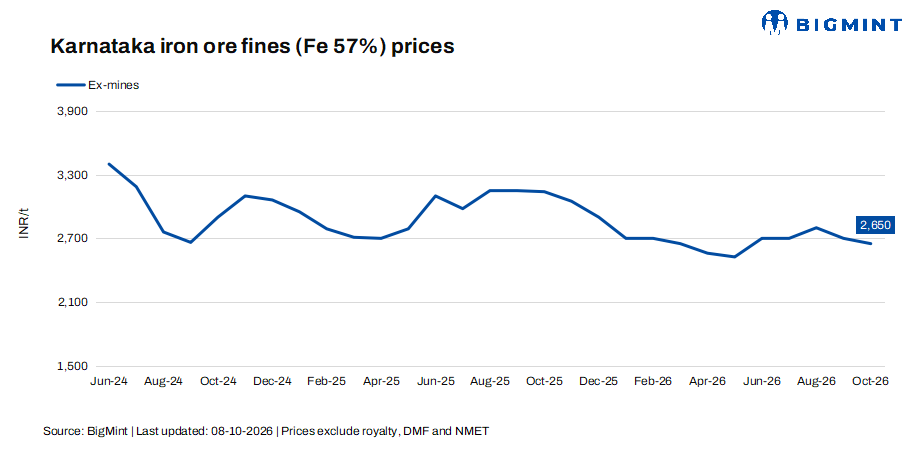
Karnataka iron ore prices remained largely stable this week despite weakening sponge iron and finished steel prices. The decline in downstream demand has reduced fresh raw material buying, with several market participants holding sufficient inventories. However, tight availability of suitable high-grade iron ore continues to support prices, keeping the market divided between weak low-grade demand and firm high-grade demand.
According to BigMint’s latest assessment, Fe 57% iron ore fines prices remained unchanged w-o-w at INR 2,650/t ($28/t) ex-mines. Demand for low-grade ore remained weak amid ample availability, while its lower economic viability has further reduced buying interest. Market participants indicated that the weakness is not limited to Fe 57% fines, with demand for low-grade material remaining subdued across the region.
In contrast, Fe 62% fines prices remained stable at INR 5,250/t ($55/t) ex-mines. Availability of suitable high-grade material remains relatively tight, supporting prices despite weaker downstream market conditions. Good-quality high-grade ore continues to attract interest as buyers face difficulty in sourcing material that meets their requirements.
Sponge iron prices weakened during the week as finished steel demand remained subdued. Lower finished steel realisations have prompted buyers to adopt a cautious approach towards billet and sponge iron procurement, consequently reducing the urgency for fresh iron ore purchases.
However, the weaker downstream market has so far had a limited impact on iron ore prices, as several players are already carrying sufficient inventories. This has reduced spot buying activity but has not resulted in significant price pressure on high-grade material due to its limited availability.
Low-grade iron ore continued to face pressure in Karnataka due to both weak demand and ample availability. Market participants indicated that lower-grade material has become less attractive from an economic perspective, particularly when downstream realisations are under pressure.
As a result, buyers are showing limited interest in accumulating low-grade material, while sellers are facing difficulty in generating sufficient buying interest despite competitive price levels.
The high-grade segment continued to perform relatively better, primarily due to limited availability of suitable-quality material. Buyers are reportedly finding it difficult to secure the required grade, prompting some to explore alternative sourcing options.
A Bellary-based buyer said that “the shortage of required high-grade material has prompted the company to consider sourcing from beneficiation plants to meet its raw material requirements.”
Auction activity during the week reflected the divergent market sentiment. Low-grade auctions received a weak response, while even some high-grade material offered at elevated prices struggled to attract sufficient buying interest as higher procurement costs have reduced viability for buyers.
With NMDC also scheduled to offer predominantly sub-62% material in its upcoming auction, market participants are closely monitoring the response from buyers, particularly amid weak downstream demand.
A Bellary-based seller told BigMint, “Fines fetched a weak response in our auction, while lumps were almost sold.”
Rationale
- One (1) trade via e-auction was recorded for Fe 57% in this publishing window and was taken into consideration. Hence, the T1 trade category was accorded 50% weightage.
- Fourteen (14) offers and indicative prices were reported, out of which ten (12) were considered as T2. These were accorded 50% weightage.
Influencing factors
- P-DRI prices fall by INR 700/t ($7/t) w-o-w in Bellary: Bellary pellet-based sponge iron (P-DRI) prices declined by INR 700/t ($7/t) w-o-w to INR 30,600/t ($316/t) amid weaker buying interest over the past few days. Weak finished steel demand has reduced procurement appetite for billets and sponge iron, prompting buyers to remain cautious. The softer downstream market is expected to keep sponge iron prices volatile in the near term.
- Imported coal prices remain elevated: South African thermal coal prices at Indian ports remained firm despite subdued market activity and softer bids. Ex-Paradip RB2 (5,500 NAR) increased by INR 200/t w-o-w to INR 13,500/t, while RB3 declined by INR 100/t to INR 11,500/t. Ex-Vizag RB2 rose by INR 150/t to INR 13,400/t, whereas RB3 declined by INR 50/t to INR 11,500/t. Elevated imported coal costs, combined with weaker sponge iron demand, are limiting the willingness of producers to aggressively replenish raw materials.
- Imported ore gains buying interest: Import inquiries for iron ore have increased as softer global prices have improved the economics of imported material amid tightening domestic availability of higher-grade ore. South African 65% Fe lumps are currently being offered at around $118-120/t CFR India, with increased interest reported from buyers. Lower global prices have made imported material more competitive, particularly for consumers facing difficulty in securing suitable domestic grades. Iron ore fines import bookings have also continued in Karnataka.
Karnataka iron ore sales scenario (2- 08 October 2026)

Outlook
Karnataka iron ore prices are expected to remain under pressure in the near term, particularly in the low-grade segment, as weak finished steel and sponge iron demand limits fresh buying interest. High-grade prices may remain relatively resilient initially due to tight availability, although a prolonged decline in downstream prices could eventually exert broader pressure on iron ore prices.
Leave a Reply