- Atlantic cargo activity strengthens as Pacific flows remain mixed
- Capesize freight sentiment stays subdued as holiday lull weighs on activity
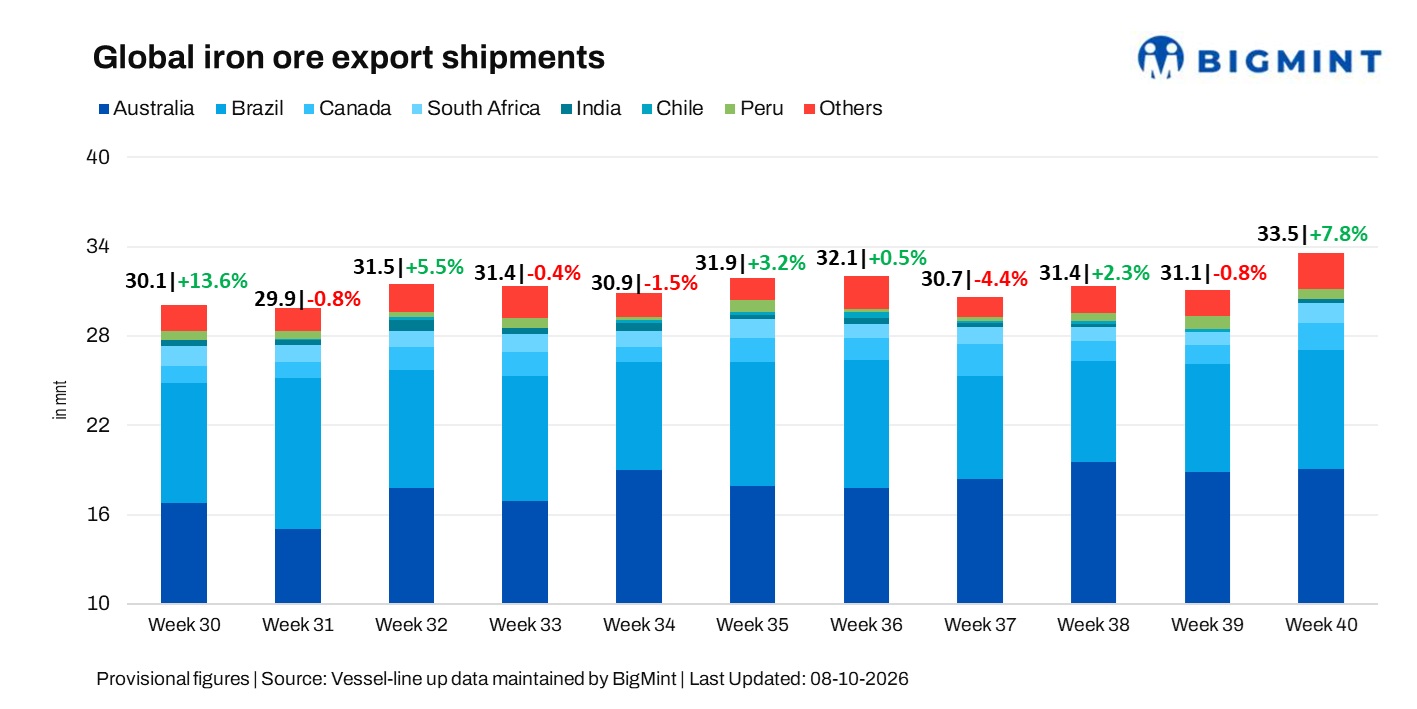
Global seaborne iron ore shipments rose 7.8% w-o-w to 33.5 million tonnes (mnt) in the week ended 2 October, from 31.1 mnt a week earlier. Stronger flows from Brazil, Canada, South Africa, Guinea, Liberia and Sierra Leone more than offset softer volumes from Peru, Chile and Mauritania, while Australia and Sweden remained broadly stable.
The weekly market saw a stronger contribution from Atlantic and West African origins, while China’s Golden Week holiday kept near-term buying and fixture activity subdued. Softer steel margins, cautious mill buying and elevated port inventories continued to weigh on Chinese demand, although post-holiday restocking could provide some support once market activity resumes.
Country-wise exports

Port & shipper-wise trends
- Australia: Hedland led at 11.5 mnt, followed by Walcott at 4.1 mnt and Dampier at 3.1 mnt. Rio Tinto was the largest shipper at 7.2 mnt, followed by BHP at 5.4 mnt and Fortescue Metals at 4.7 mnt. China remained the key destination at 14.8 mnt, followed by Japan at 1.8 mnt and South Korea at 1.4 mnt.
- Brazil: Ponta da Madeira led at 3.1 mnt, followed by Tubarao at 2.3 mnt and Itaguai at 1.4 mnt. CSN & Vale together accounted for 3.8 mnt, while Vale contributed 3.5 mnt. China received 2.5 mnt, followed by Oman and India at 0.4 mnt each.
- Canada: Sept-Iles led at 1.0 mnt, followed by Port-Cartier at 0.6 mnt. The Netherlands received 0.5 mnt, followed by Egypt at 0.3 mnt. IOC and ArcelorMittal each accounted for 0.6 mnt.
- South Africa: Saldanha led at 1.2 mnt, followed by Richards Bay at 0.2 mnt. Vietnam, the Netherlands and China each received 0.2 mnt.
- India: Kandla led at 0.07 mnt, followed by Dhamra, Mormugao and Krishnapatnam at 0.06 mnt each. Rungta Mines, Vedanta and A-One Steels each accounted for 0.06 mnt.
- Chile: No seaborne activity was recorded during the week.
- Peru: San Nicolas handled 0.6 mnt, with China receiving 0.7 mnt. Shougang Hierro accounted for 0.6 mnt.
- Guinea: Morebaya handled 0.9 mnt, with China receiving 0.7 mnt.
- Liberia: Buchanan handled 0.3 mnt, with China receiving 0.06 mnt and Germany 0.05 mnt.
- Sierra Leone: Freetown handled 0.5 mnt, with China receiving 0.2 mnt.
- Norway: Mo i Rana handled 0.07 mnt, entirely destined for the Netherlands.
- Mauritania: Nouadhibou handled 0.2 mnt during the week.
- Sweden: Narvik handled 0.4 mnt, with Turkey receiving 0.2 mnt.
Capesize freight sentiment subdued amid holiday lull
Capesize freight markets remained under pressure as China’s Golden Week holiday curtailed fresh cargo enquiries and fixture activity. Prompt tonnage remained ample, particularly in the Pacific, weighing on Australia-China rates, while limited Brazil-China cargo activity kept Atlantic sentiment soft.
The Pacific market saw some late-week recovery as chartering activity picked up for second-half October Australian cargoes, with the West Australia-Qingdao C5 route strengthening. However, Brazil-Qingdao C3 remained under pressure amid limited fresh cargo and a longer tonnage list. Overall, cautious Chinese buying and ample vessel availability kept freight sentiment subdued, although post-holiday restocking could provide some support.
Outlook
Global iron ore flows are likely to remain supported by stronger Atlantic and West African availability, particularly as Guinea’s Simandou ramp-up progresses. Meanwhile, Australian loadings are expected to remain relatively steady, while smaller origins could continue to see week-to-week volatility.
Freight rates are likely to remain under pressure in the near term as Golden Week weighs on Chinese buying and prompt tonnage remains ample. A pickup in post-holiday restocking, second-half October cargoes and West African chartering could provide support, particularly if vessel availability tightens.
Leave a Reply