- Firm reductant costs, stable export offers support prices
- Vedanta-FACOR’s auction postponed to 9 Oct’26
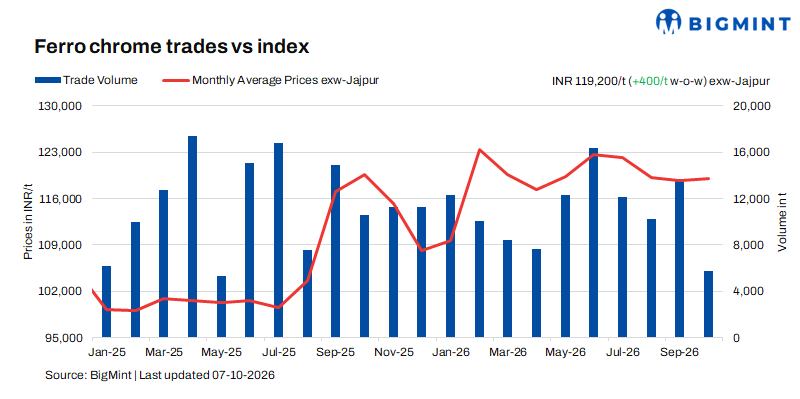
Indian high-carbon ferro chrome (HC 60%, Si: 4%) prices inched up by INR 400/t ($4/t) w-o-w to INR 119,200/t ($1,232/t) exw-Jajpur, as per BigMint’s assessment on 7 October. Firm reductant costs, improved domestic buying, and stable export offers kept domestic prices supported.
Deals for around 5,700 t were heard during the week ended 8 October 2026 within the price range of INR 118,000-120,000/t ($1,220-1,240/t) ex-Jajpur.
Low phosphorus and low silicon ferro chrome prices were unchanged as well. However, low carbon ferro chrome prices slipped slightly by INR 600/t ($6/t) w-o-w to INR 238,400/t ($2,464/t) exw-Durgapur.
Market summary (1-7 October)
Stronger domestic buying supports prices: Domestic demand remained supportive last week, keeping seller offers firm. This was also reflected in trading activity, with trades captured by BigMint for the week ended 7 October rising by around 150% w-o-w to 5,700 t.
Vedanta-Ferro Alloys Corporation Ltd (FACOR) has also rescheduled its ferro chrome auction from 7 October to 9 October. The auction will comprise four lots of HC ferro chrome: two lots of Cr:57% min (10-50 mm and 10-70 mm), one lot of Cr:54% min (10-20 mm), and one lot of Cr:55% min (0-10 mm). Size material lots will attract an additional sizing cost of INR 1,500/t ($16/t).
Firm reductant prices support production costs: Reductant costs remained supported, with met coke sentiment firm amid higher imports and increased procurement by steelmakers. Met coke imports rose by around 0.8 mnt to 2.7 mnt during April-August. Imports also increased to 1.5 mnt during July-September from 1.2 mnt in April-June. Subdued domestic coking coal production and continued reliance on imports kept met coke procurement and prices firm, supporting ferro chrome production costs.
Export prices remain stable amid limited buying: Export prices to China, Japan and South Korea remained largely stable last week. Buying activity was limited amid the market closure in China and the absence of fresh tenders from Japan and South Korea. However, the recent depreciation of the Indian rupee supported seller realisations in these markets, which in turn provided support to domestic ferro chrome prices.
Festive demand expected to support stainless steel sentiment: Indian stainless steel 304 grade HRC prices edged down by INR 2,000/t ($21/t) w-o-w to INR 218,000/t ($2,253/t) exw-Mumbai. Flats demand was relatively steady, while longs saw weaker buying amid cautious sentiment. Tight scrap availability, volatile nickel prices, and higher molybdenum costs continued to influence the market. 316-grade prices remained supported due to tight scrap availability and higher molybdenum costs, while 304 prices were relatively stable.
Buying activity is expected to improve gradually in October as downstream users replenish stocks ahead of Diwali, although buyers remain focused on immediate requirements due to uncertainty over raw material and freight costs.
Globally, stainless steel prices remained firm across key Asian markets, supported by higher raw material costs and supply concerns. Taiwan’s export prices reached a 17-month high, while Japanese and Nagoya markets also remained firm. Overall, India’s stainless steel market is expected to remain firm, with festive restocking providing support but cautious buying limiting significant price gains.
Outlook
Indian ferro chrome prices are expected to remain firm in the coming week, supported by stronger domestic buying, firm reductant costs, and pre-festive season restocking. The upcoming Vedanta-FACOR auction on 9 October is expected to provide further clarity on market price direction.
Leave a Reply