- Sponge iron prices decrease INR 400/t d-o-d
- Power outages, liquidity constraints weigh on trading
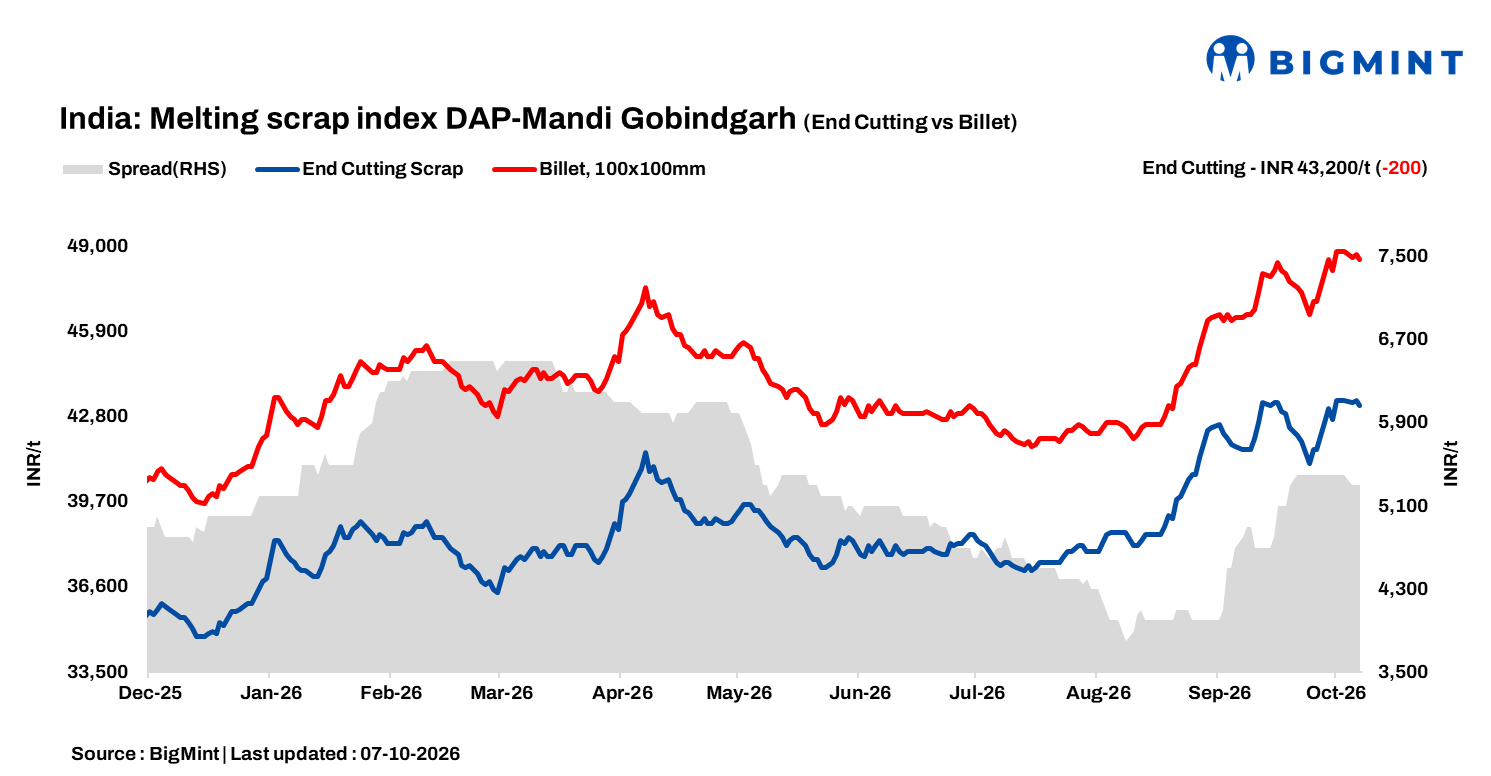
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, declined by INR 200/t d-o-d to INR 43,200/t DAP on 7 October 2026. Scrap prices in the region edged down by INR 200/t today, amid thin trading activity. Mandi Gobindgarh market remained sluggish in both halves of the trading session, with negligible buying activity observed across the raw-to-finished steel segments. The subdued sentiment was exacerbated by persistent power outages affecting the northern cluster, while scrap arrivals continued to exceed demand in the Mandi Gobindgarh-Ludhiana region.
Amid weak offtake, scrap suppliers scaled back offers, and semi-finished steel prices declined by approximately INR 200/t. The downturn was further compounded by a liquidity crunch among traders and processors in the Mandi, dampening overall market participation.
Raw material
Sponge iron prices fell by INR 400/t d-o-d to INR 35,200/t DAP, reflecting sluggish buying activity today. In contrast, steel-grade pig iron prices in Ludhiana held steady d-o-d at INR 44,000/t DAP, as demand for alternative raw materials remained muted across the northern region.
Steel market
Steel ingot prices in Mandi Gobindgarh declined by INR 200/t d-o-d to INR 48,500/t DAP, reflecting cautious sentiment across the secondary steel segment. Broader market weakness was evident, with other key trading hubs recording declines of INR 100-500/t. Jaipur registered the sharpest correction, as ingot prices fell by approximately INR 500 per tonne in a single session.
In contrast, rebar prices in Mandi Gobindgarh edged up by INR 100/t d-o-d to INR 53,700/t ex-works. However, HR strip (patra) prices softened by INR 200/t day-on-day to INR 53,000/t ex-works, underscoring divergent demand trends across finished steel products.
Upcoming scrap auctions

Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,300-5,700/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva port were assessed at $373-375/t, equivalent to approximately INR 38,400/t (inclusive of freight). HMS (80:20) prices in Mumbai remained stable day-on-day at INR 37,000/t DAP, while HMS (90:10) prices also held steady at the INR 38,000/t level. Indicative prices for shredded scrap from Europe stood at $415/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,600/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply