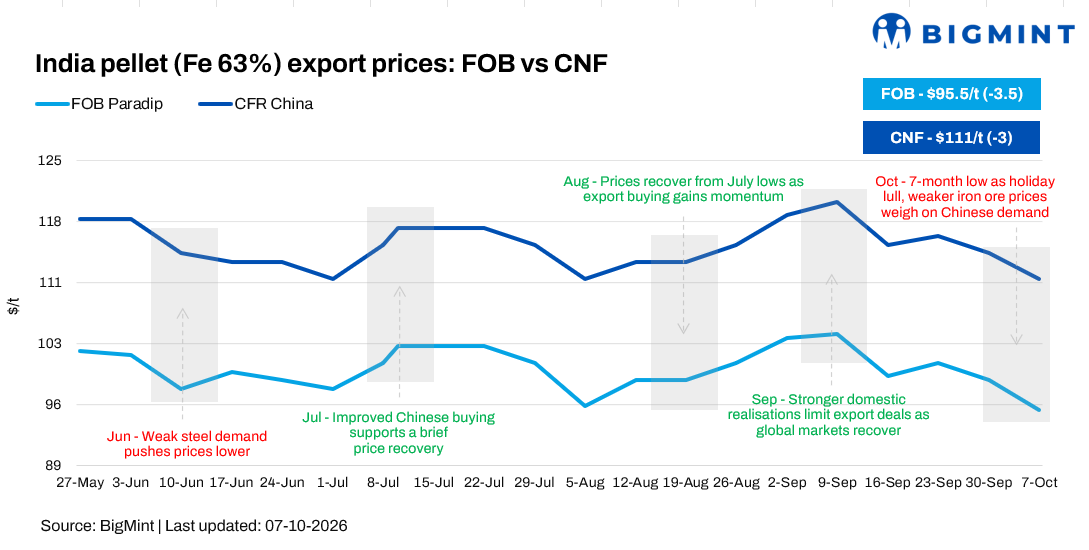
- Holiday-related market lull, lower iron ore prices weigh on sentiment
- India pellet export prices decline as Chinese demand remains weak
BigMint’s India pellet export index declined by around $3.5/tonne (t) w-o-w to $95.5/t FOB East Coast in the week ending 7 October 2026, equivalent to around $111/t CFR China, falling to a seven-month low as the same levels were last seen in February 2026. The decline reflects weak export sentiment and limited buying interest, with China’s ongoing holiday keeping the market largely inactive.
Market participants said current export prices are not workable for Indian pellet producers, particularly given prevailing iron ore costs. Several producers are therefore unwilling to commit cargoes at current levels, while buyers remain cautious ahead of the reopening of the Chinese market.
A seller told BigMint, “Market conditions have weakened, and exports are currently not feasible at prevailing price levels. At these levels, export realisations would not be sufficient to recover the cost of ore production. Therefore, we currently have no plans to export.”
Rationale
- Zero (0) deals from India’s east coast were recorded for T1 trade during the publishing window; therefore, this category was assigned a 0% weightage in today’s price calculation.
- Seven (7) bids, offers, and indicative prices were heard, of which all were considered for the calculation of the index and given the balance 100% weightage.
“Most producers are not willing to sell at current levels. Yesterday a major pellet producers’ tender did not conclude. We heard that material was sold domestically at around INR 11,300/t ($117/t), which is much higher than what is achievable in the export market today,” a trader said.
The disparity between domestic and export realisations is consequently limiting sellers’ willingness to participate in the seaborne market.

Export realisations weaken further as domestic market maintains premium
Pellet export realisations for Fe 63% declined by INR 300/t ($3.4/t) w-o-w to INR 7,000/t ($72.6/t) exw this week, reflecting continued pressure from weak seaborne demand and subdued buying interest. In contrast, domestic Fe 62.5% pellet realisations remained firm at INR 9,250/t ($95.6/t) ex-works, supported by comparatively better domestic demand and stronger price realisations.
As a result, the gap between domestic and export realisations widened by INR 200/t ($2.2/t) w-o-w to INR 2,150/t ($22/t). The widening spread further reduces the incentive for producers to pursue exports, keeping seller sentiment cautious and highlighting the growing disparity between domestic and international pellet markets.
China holiday limits market activity
China’s ongoing holiday has further reduced spot market activity and price visibility. With Chinese buyers largely absent from the market, fresh indications and firm offers have remained limited.
Market participants expect greater clarity once China resumes trading on 8 October, as buying interest from Chinese mills and traders will provide a better indication of near-term demand and achievable import prices.
“China opens tomorrow. No one will export at this level,” another trader said, highlighting the current disconnect between Indian producers’ price expectations and export market levels.
However, during the current week (26 September-2 October), iron ore pellet dispatches rose sharply to 130,520 t, compared with nil volumes in the previous week, driven by 62,700 t from Dhamra (Rungta Mines) and 67,820 t from Kandla.
- Cautious Chinese demand drives decline in iron ore prices: The benchmark iron ore fines (Fe 61%) index declined by $2/dmt w-o-w to $91/dmt CFR China on 6 October, from $93/dmt on 29 September, amid bearish market sentiment. Prices came under pressure as Chinese mills remained cautious in spot procurement following the Golden Week holidays, while weak steel margins and subdued downstream demand limited restocking activity. Ample spot availability and limited buying urgency further weighed on prices, keeping near-term market sentiment cautious-to-bearish.
- DCE futures stable amid cautious market sentiment: Iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract remained unchanged at RMB 702.5/t ($104.8/t) on 7 October, indicating a largely stable futures market despite continued weakness in the physical market. Sentiment remained cautious, with limited upside momentum as Chinese steelmakers maintained restrained procurement following the holiday period, while weak steel margins and uncertain downstream demand capped buying interest. However, the futures market’s stability suggests that downside expectations may be moderating, with participants awaiting clearer signals on post-holiday restocking and steel demand.
Outlook
The near-term direction of India’s pellet export market is likely to depend heavily on China’s return after the holiday. If Chinese buyers resume activity and restocking interest emerges, the market could gain better price visibility and potentially narrow the gap between buyer and seller expectations.
However, unless export prices improve sufficiently to make shipments economically viable, Indian pellet producers are expected to remain reluctant sellers. For now, the market remains characterised by weak buying interest, limited offers and firm seller price expectations, with participants closely watching Chinese market activity after the holiday.
Leave a Reply