- Alunorte disruption raises aluminium availability concerns
- Codelco review adds uncertainty to copper supply outlook
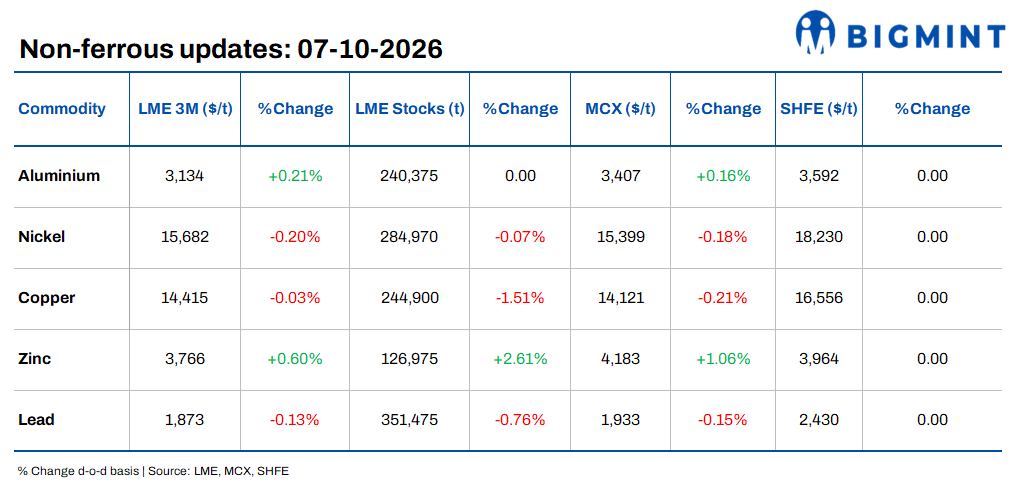
LME base metals traded mixed on 06 October. Zinc recorded the strongest gain, rising 0.60% d-o-d to $3,766/t, followed by aluminium, up 0.21% to $3,134/t. On the other hand, Lead fell 0.13% to $1,873/t, nickel declined 0.20% to $15,682/t, while copper edged lower by 0.03% to $14,415/t.
LME inventories showed a mixed trend, with copper stocks posting the largest decline, falling 1.51% to 244,900 tonnes amid tight concentrate availability and ongoing mine disruptions. Lead inventories also fell 0.76% to 351,475 tonnes, while nickel edged down 0.07% to 284,970 tonnes. In contrast, zinc stocks rose 2.61% to 126,975 tonnes, while aluminium inventories were unchanged at 240,375 tonnes.
Domestic market overview
India’s non-ferrous scrap market witnessed largely stable trends d-o-d. Aluminium scrap prices were unchanged, while copper armature scrap moved higher.
Aluminium tense scrap (loose) remained unchanged at INR 244,000/t ex-Delhi and INR 246,000/t ex-Chennai. Meanwhile, aluminium P1020 also held steady at INR 344,000/t. Despite the stagnation in domestic price MCX aluminium gained 0.16%, rising to $3,407/t.
Meanwhile, copper armature scrap (Cu 99%), ex-Delhi, rose by INR 6,000/t, or 0.45% d-o-d, to INR 1,349,000/t from INR 1,343,000/t. The move contrasted with the MCX copper benchmark, which declined 0.21% to $14,121/t.

Other updates
Alunorte disruption raises aluminium availability concerns
Norsk Hydro’s Alunorte refinery in Brazil continues to source natural gas at spot prices after contracted deliveries were disrupted in August. Hydro expects a $75–100 million financial impact in the third quarter, including 100,000–120,000 t of lost alumina production. Meanwhile, fourth-quarter gas arbitrage costs could add another $90–110 million. The immediate outage risk has eased, although higher costs and reduced Atlantic alumina availability remain relevant for aluminium markets.
Oil prices rise as disruptions intensify
Brent crude rose 1.04% to $101.62/bbl on 07 October as a Gulf of Mexico storm threatened US energy infrastructure, while renewed Houthi attacks on Saudi targets added to geopolitical supply risks. The storm could affect facilities accounting for about 15% of US crude output and 5% of natural-gas production, while US crude inventories fell by 2.09 million barrels. Chevron reportedly evacuated non-essential personnel from some Gulf of Mexico platforms ahead of the storm.
Codelco review raises uncertainty over reported copper production
Codelco has provided Chilean authorities with evidence of possible double-counting of copper production between its Ministro Hales and Salvador divisions during 2024–25. The company has appointed EY to quantify the latest discrepancy, while KPMG continues a broader review. Any downward revision could tighten expectations for future copper supply and add pressure to an already constrained concentrate market.
Peru’s stronger copper output provides limited supply relief
Peru produced 1.6 mnt of copper during January-July 2026, up 2.2% year on year, while July production rose 3.7% to 236,515 t. Antamina was a key contributor, with output increasing 54% to 297,145 t, while Las Bambas produced 245,610 t. The recovery provides some additional concentrate supply. However, the increase remains modest relative to broader supply constraints, leaving its impact as a partial counterweight to copper price strength.
Leave a Reply