- South African thermal coal rises as tight supply lifts import costs
- Domestic coal climbs as shortages continue, demand strengthens
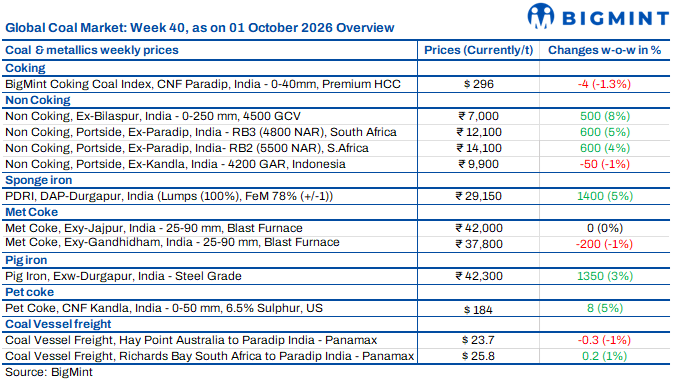
Coal market sentiment remained firm but mixed in the week ended 3 October 2026. South African thermal coal prices strengthened on tight availability and higher replacement costs, while domestic coal prices rose as supply remained constrained and expensive imports shifted some demand towards local material. Indonesian coal softened slightly on cautious industrial buying, while met coke stayed firm despite weaker raw material costs. Petcoke also remained elevated, increasing fuel-cost pressure for consumers.
Indonesian coal prices ease on cautious buying
Indian portside Indonesian thermal coal prices softened slightly during the week ended 3 October 2026 as industrial buying remained cautious. 5,000 GAR stayed at INR 11,800/t at Kandla and INR 11,700/t at Vizag, while 4,200 GAR fell INR 50/t to INR 9,900/t and INR 9,850/t, respectively. 3,400 GAR at Navlakhi also declined INR 50/t to INR 7,900/t. Power plant stocks fell around 9% w-o-w to 21.06 mnt as of 1 October, covering about seven days of consumption, limiting the downside. However, adequate non-coking coal stocks at ports and weak spot demand prevented gains. Pre-festive buying and post-Golden Week Chinese demand could provide support, while softer Indonesian benchmarks kept sentiment cautious.
South African coal prices surge
South African thermal coal prices at Indian ports strengthened sharply as of 1 October 2026, supported by limited availability, higher international replacement costs and firm industrial demand. Ex-Paradip RB2 (5,500 NAR) rose INR 600/t w-o-w to INR 14,100/t, while RB3 (4,800 NAR) increased INR 600/t to INR 12,100/t. Ex-Vizag, RB2 climbed INR 600/t to INR 14,000/t, and RB3 rose INR 500/t to INR 12,000/t. Around 45,000 t of RB2 was reportedly sold at INR 14,000/t, while another 10,000 t deal was concluded at INR 13,800/t. Limited prompt availability and higher replacement costs kept offers elevated, while enquiries remained firm. Port stocks also remained uneven, particularly at Vizag, supporting the bullish sentiment.
Domestic coal prices rise on stronger demand
Domestic coal prices strengthened as consumers increased reliance on local material amid elevated imported coal replacement costs. Ex-Bilaspur 4,500 GCV coal rose INR 500/t w-o-w to INR 7,000/t, while 5,000 GCV increased INR 700/t to INR 9,000/t as of 1 October. Recent SECL auctions also recorded premiums above 200% for selected G8 sources, reflecting strong competition for preferred grades. Higher import costs encouraged some users to shift towards domestic coal, while ECL material was also being used to meet requirements.
Washed coal prices rise on raw coal constraints
Washed coal prices moved higher as washeries continued to face difficulty securing suitable ROM coal. 38-39% FC (5,000 GCV) washed coal FOR Raipur rose INR 850/t w-o-w to INR 10,000/t as of 30 September. Limited raw material availability restricted production and reduced market offers, keeping sellers firm. The shortage also encouraged some suppliers to explore material from alternative regions, although higher sourcing costs limited room for lower offers. Despite cautious buying, tight physical availability remained the main support for washed coal prices.
Met coke prices remain weak amid softer inputs
India’s met coke market remained stable to slightly weak during the week ended 30 September, with BF-grade coke unchanged at INR 42,000/t ex-Jajpur, while western India declined INR 200/t to INR 37,800/t ex-Gandhidham. Foundry-grade coke at Rajkot fell INR 100/t to INR 39,400/t. High prices and cautious buying limited fresh demand, while Australian PHCC declined $3/t w-o-w to $272/t FOB. Softer Chinese and Australian coking coal reduced coke replacement costs. Chinese Golden Week was expected to temporarily slow global activity, while post-holiday buying could influence the next price direction. Pig iron prices rose INR 1,100/t to INR 42,100/t ex-works Durgapur, providing limited support amid supply disruptions.
US thermal coal prices hold firm
Indian US NAPP coal markets remained firm as October cargoes were offered at around $190/t CFR WCI, against bids near $175/t. Retail portside offers increased to INR 19,000-19,300/t, with some reaching INR 19,400/t, while spot transactions were around INR 18,000-18,200/t. Kandla and Tuna stocks stood at 71,092 t on 28 September, with most inventory at Kandla. Core Natural Resources had no fresh availability for January-February 2027 and offered later cargoes at $125/t FOB Baltimore. Buyers remained cautious, and purchases stayed mainly need-based. Around 1.46 mnt of NAPP cargoes were scheduled for October arrival, which could ease prompt supply if deliveries remained on schedule.
Petcoke prices rise even as buyers resist
Imported petcoke prices strengthened further as US Gulf Coast values increased. USGC 6.5% sulphur petcoke rose $9/t to $107/t FOB, while 4.5% sulphur material also increased $9/t to $114/t in the week ended 30 September. Indian offers reached around $185-190/t by 1 October, compared with $153-160/t earlier in September. Cement sector buyers remained cautious at these levels, with some producers relying on existing inventories, domestic refinery supplies and coal. One producer indicated imported petcoke buying interest at only $131-135/t, highlighting strong price resistance. Elevated replacement costs therefore kept fresh imported petcoke procurement selective.
Domestic petcoke prices rise sharply
India’s domestic petcoke prices increased sharply in October, with Nayara Energy raising its price by INR 2,180/t to INR 20,960/t and MRPL increasing its rake price by INR 2,000/t to INR 17,370/t and road price to INR 19,300/t. Nayara’s price rose 11.6% m-o-m and 41% y-o-y, while MRPL’s increase was 13% m-o-m and its rake price was 46.7% higher y-o-y. Higher international petcoke costs, with US-origin material around $174-175/t CFR west coast India, along with elevated freight, supported the increases. Higher domestic prices also encouraged buyers to compare refinery supplies with imported petcoke and alternative fuels.
BPCL petcoke prices rise in Oct
BPCL raised petcoke prices by INR 1,500/t at both Bina and Kochi, effective 1 October 2026. Bina road and rake prices increased to INR 19,500/t, while Kochi rail price also rose to INR 19,500/t. The increase represented an 8.3% m-o-m rise, while Bina and Kochi prices were 32% and 55.4% higher y-o-y, respectively. Both refineries had maintained the same price since August. Bina availability was around 20,000-25,000 t, with much of the supply consumed by its captive power plant, while Kochi availability was 75,000-80,000 t/month. Both prices remained INR 1,460/t below Nayara’s October price of INR 20,960/t.
Coal freight markets remain mixed
India-bound coal freight markets remained mixed in the week ended 1 October 2026, with Panamax rates supported by tight prompt tonnage and steady India-bound enquiries, while Supramax rates edged higher despite limited spot activity. Hay Point-Paradip Panamax freight fell $0.3/t w-o-w to $23.7/t, while RBCT-Paradip increased $0.2/t to $25.8/t. East Kalimantan-Navlakhi Supramax rose $0.7/t to $23.7/t, while South Kalimantan-Navlakhi increased $0.5/t to $22.7/t. Quiet Pacific activity and limited Indonesian cargo enquiries kept fixing subdued, while firm owner rate ideas supported freight. The BDI declined 10.4% w-o-w to 3,113, although Panamax and Supramax remained relatively stable. Singapore VLSFO fell 6.5% to $845/t, easing voyage cost pressure.
Leave a Reply