- Demand improves in western, southern India
- Thinner gauge availability remains tight in South
India’s HRC trade-level prices increased by around INR 100-700/t across key markets. Market demand has improved, with buying activity picking up across regions.
CRC trade-level prices also increased by around INR 200-1,300/t across key markets, supported by improved buying interest and higher market prices.
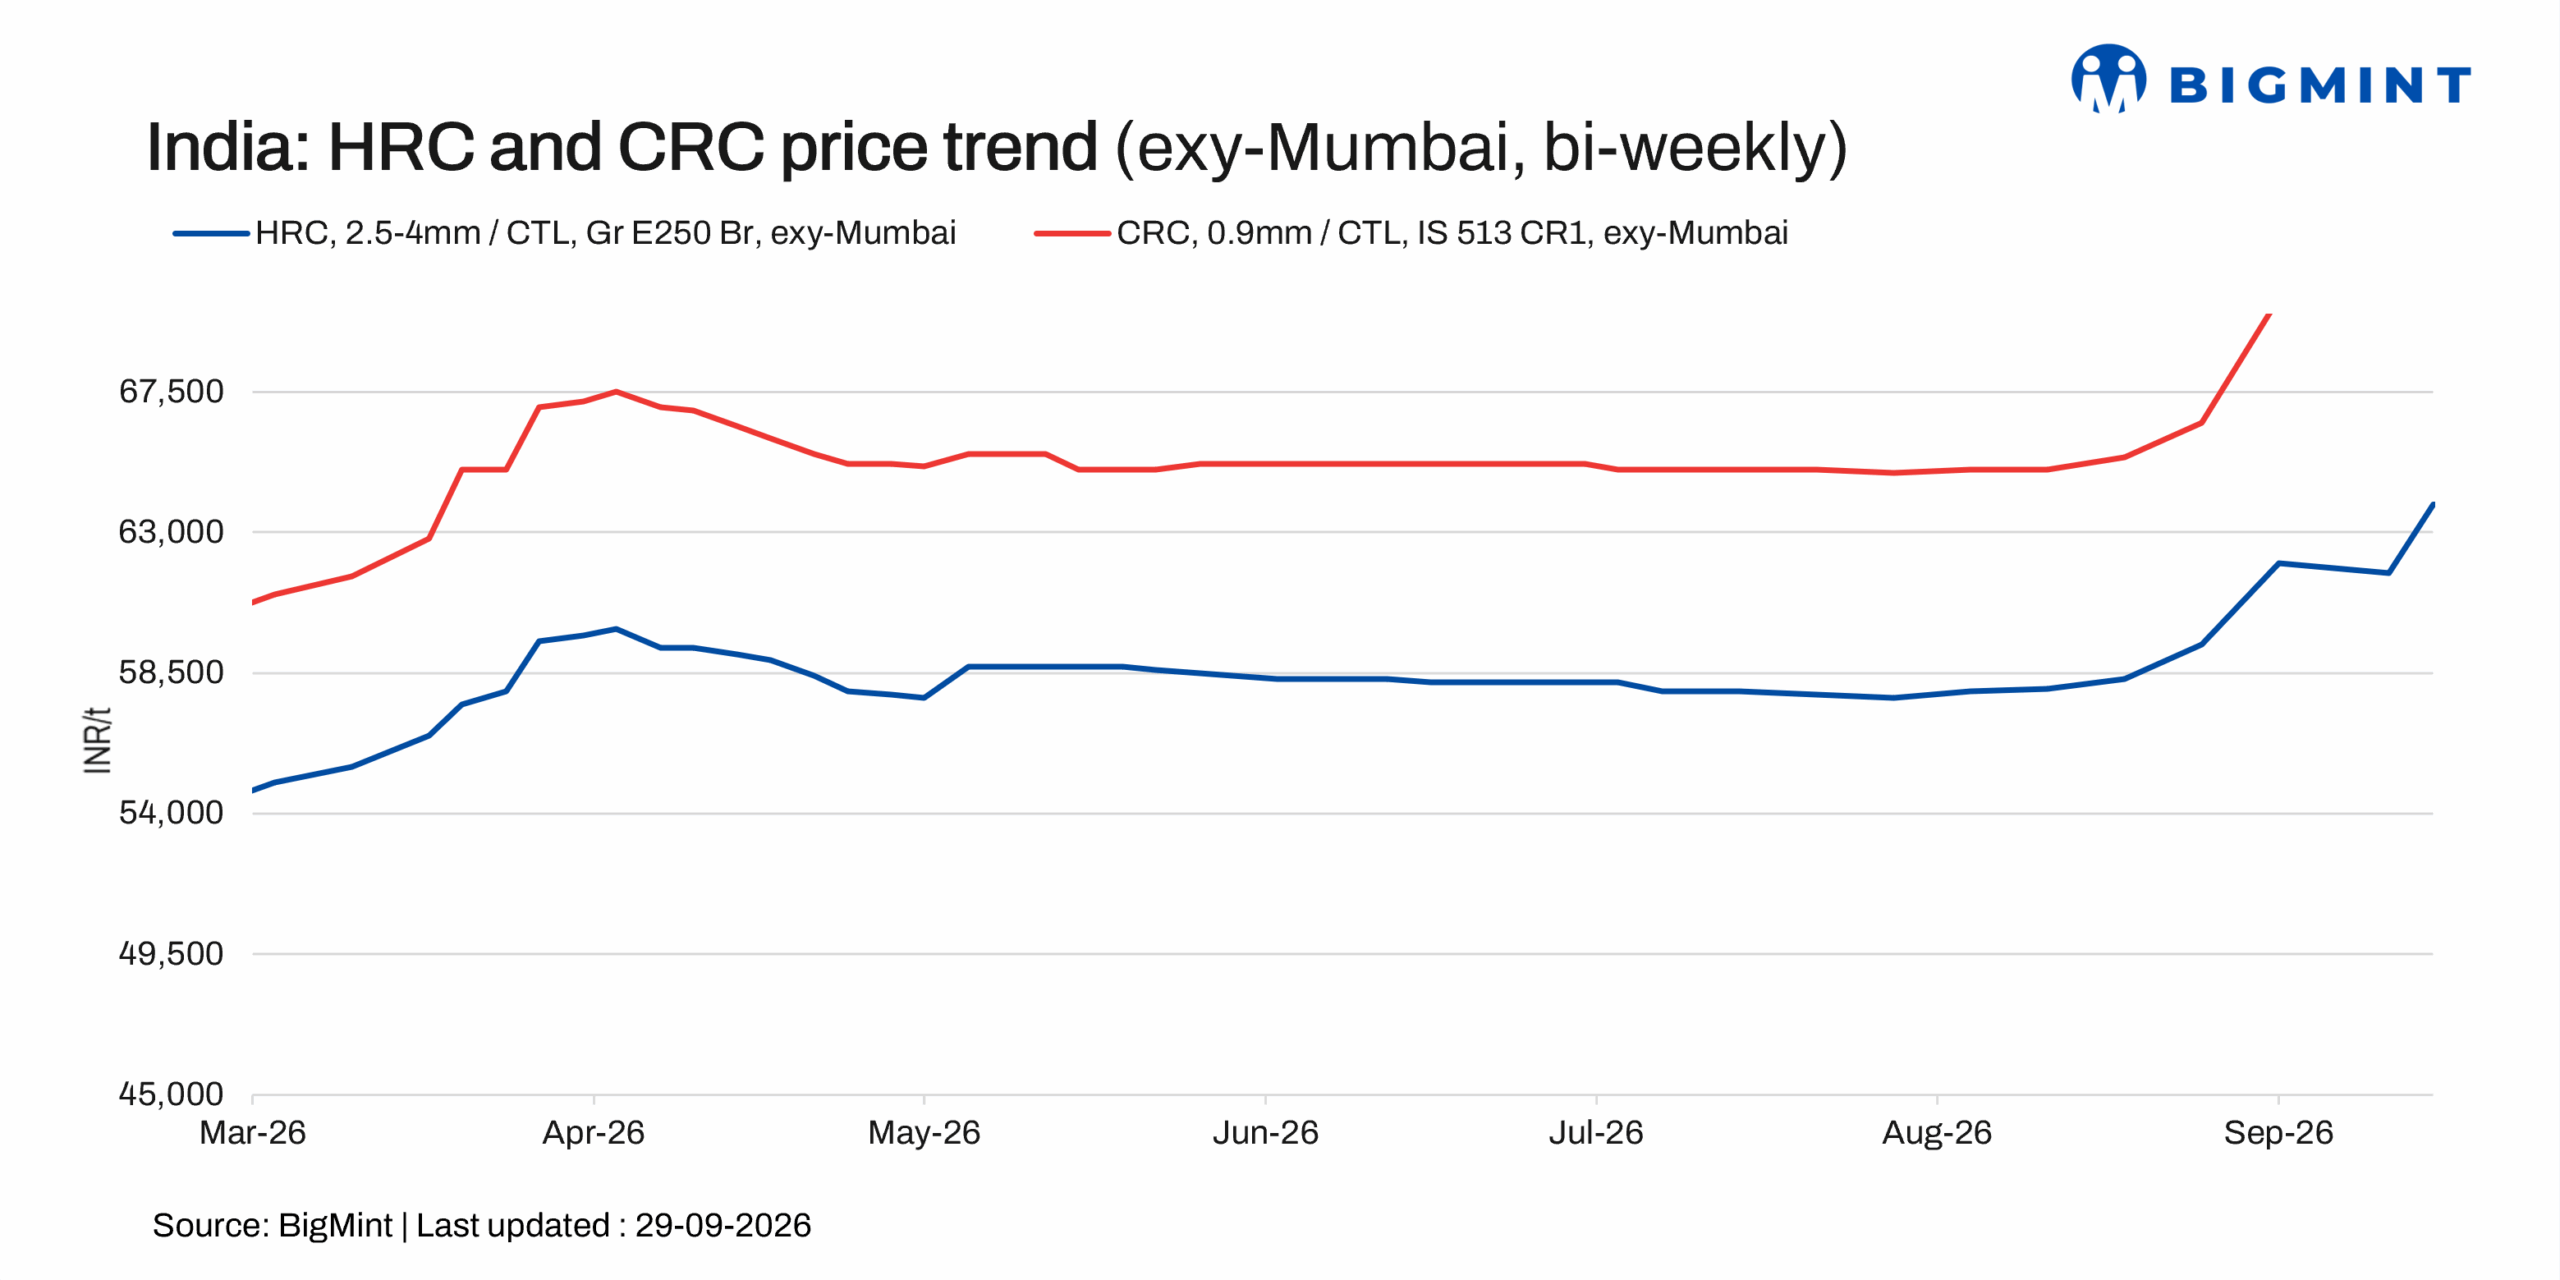
BigMint’s bi-weekly benchmark assessment for Mumbai HRC (2.5-8 mm/CTL, IS 2062, Grade E250 BR) remained unchanged w-o-w at INR 63,900/t ex-Mumbai as of 29 September 2026.
Meanwhile, Mumbai CRC (0.90 mm/CTL, IS 513, CR1) was assessed at INR 74,000/t ex-Mumbai, up by INR 300/t w-o-w from INR 73,700/t in the previous assessment.

Market update
HRC and CRC prices have increased across key markets, mainly following recent price hikes announced by major domestic steel mills. Market demand has also improved slightly compared with last week, with buying activity picking up across regions.
In the western market, demand has improved, with buying activity picking up despite higher price levels. Buyers are continuing to procure material, supported by expectations of further price increases.
In the southern market, overall demand has also improved, with enquiries increasing in the market. However, not all enquiries are being covered, as availability remains relatively tight for some specifications. Inventory levels are estimated at around 80% of normal levels.
In the northern market, demand remains largely need-based, with buyers mainly purchasing for immediate requirements. There is also a slight shortage of thinner-gauge material in the market in both northern and southern market.
Overall, demand and supply conditions remain positive in the near term. Market participants expect prices to move higher further, supported by recent mill price hikes, improving demand and relatively tight availability.
Trade activity:
Import volumes:
India’s bulk HRC imports stood at 109,422 tonnes (t) as of 25 September, with a further 62,854 t expected to arrive by the end of October.
A significant portion of these imports is being received under long-term agreements between Indian companies and their parent entities in South Korea and Japan.

Export volumes:
India’s bulk HRC exports stood at 277,476 t as of 25 September 2026, with another 37,675 t expected to be shipped by the end of this month.
Outlook
HRC and CRC prices are expected to move higher in the near term, supported by improving demand in western and southern markets. Enquiries have started converting into actual purchases, indicating a gradual improvement in market activity.
Domestic mills are expected to raise HRC and CRC prices by around INR 1,000-1,500/t October . With buyers gradually increasing procurement, the expected mill hikes are likely to translate into higher market prices in the coming weeks.
Leave a Reply