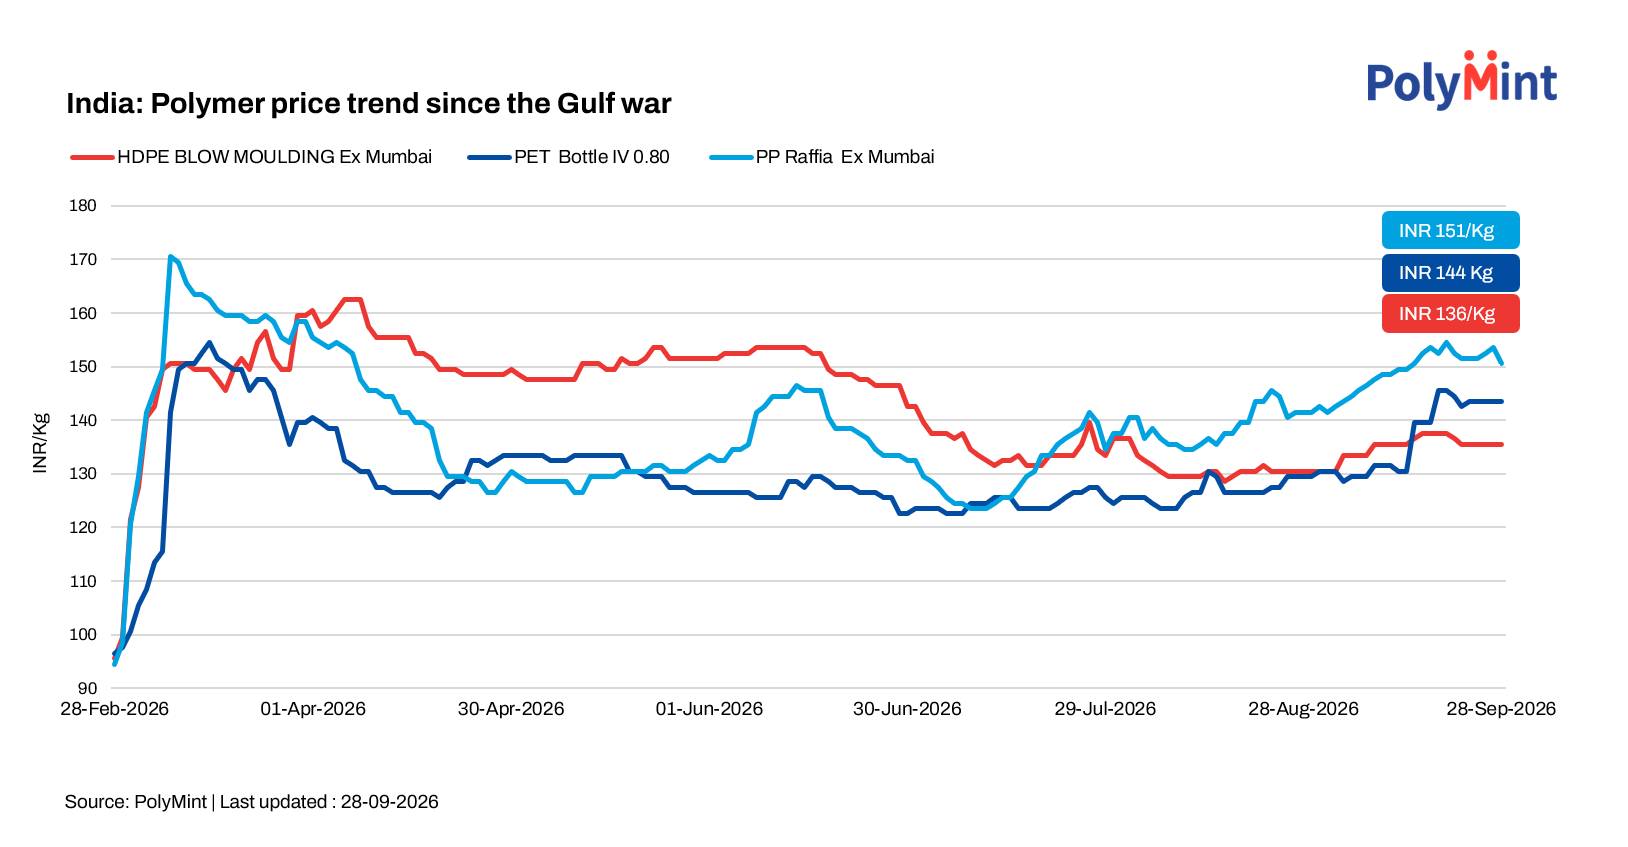
- PP Raffia, PET prices rise more than 50%
- Naphtha remains 42% above pre-war level
Indian polymer prices have undergone a sharp reset since the Gulf conflict began on 28 February, with 25 producer revisions lifting PP Raffia by around 55%, PET Bottle by 53% and HDPE Blow Moulding by 40% over seven months. The increases have tracked the feedstock shock, which has eased from its March peak but remains well above pre-war levels.
Naphtha CFR Far East Asia rose from $640/t on 27 February to $1,240/t on 31 March as Gulf exports collapsed. It has since declined to $910/t on 25 September, down 27% from the peak but still 42% above the pre-war level.
Supply disruptions continue to underpin feedstock costs. Traffic through the Strait of Hormuz fell from more than 100 vessels a day to an average of around five over the summer, while oil flows through the strait declined from 21.6 million bpd in Q4 2025 to 4.9 million bpd in Q2 2026.
The supply situation tightened again in September after Saudi Arabia temporarily shut its East-West pipeline, which carries 4-5 million bpd to the Red Sea, following drone attacks on 11 September.
Domestic prices reverse July correction
RIL’s price revisions show a sharp initial increase in March, followed by a correction through early July and a renewed climb from late July.
PP Raffia rose INR 46/kg across four revisions in March, including individual hikes of INR 15/kg and INR 23/kg. HDPE Blow Moulding and PET also moved higher during the period.
Prices subsequently corrected as naphtha declined from its March peak. PP Raffia fell to around INR 132/kg after a INR 12.49/kg cut on 2 July. HDPE Blow Moulding declined by nearly INR 23/kg across three July cuts to around INR 128.5/kg.
The correction reversed from late July. PP Raffia has since gained INR 23/kg across seven hikes to INR 155/kg, returning to its April peak.
PET Bottle increased INR 15.5/kg across four September hikes to INR 145/kg, its highest level since the conflict began. HDPE Blow Moulding has been comparatively weaker at INR 133/kg, around 14% below its April high.
Import costs track domestic increases
Import replacement costs have risen broadly in line with domestic prices, limiting the incentive for converters to switch to overseas material.
Saudi-origin PP Raffia is offered at $1,355/t CFR Mundra, up 44% from $940/t before the war. Middle East HDPE Blow Moulding is at $1,270/t CFR Mundra, also up 44% from $885/t.
Vietnam-origin PET Bottle is at $1,250/t FOB, up 45% from $860/t.
With overseas offers increasing by a similar margin, imports have provided limited price relief to converters. Domestic producers have consequently retained room to hold higher price levels.
Grade-wise market response remains mixed
PP remains firm, with tight availability of copolymer and random-copolymer grades keeping seller offers high. PVC is also firm as restricted imports and strong overseas offers limit supply, although buyers remain cautious.
PE is soft to stable. Tight LDPE availability and recent producer hikes continue to support prices despite cautious buying.
PET remains firm on limited imports, vessel delays and recent producer hikes. Buyers, however, continue to purchase cautiously.
Leave a Reply