- Scrap buying improves today as finished steel prices increase
- Elevated scrap arrivals, buyers’ resistance to offers lead to w-o-w drop
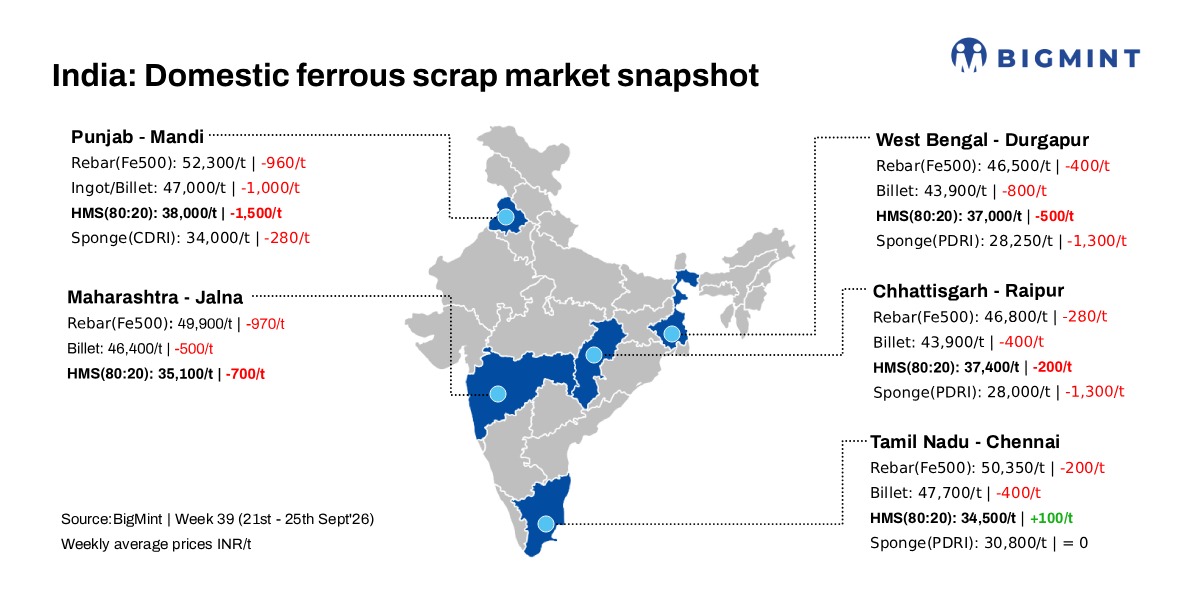
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, rose by INR 500/t d-o-d to INR 41,600/t DAP on 25 September 2026. Meanwhile, the scrap index eased by INR 1,350/t w-o-w, while other grades of scrap declined by INR 1,450-1,500/t.
After a week of subdued activity, demand in the Mandi secondary steel market improved in today’s trading session. Scrap-to-finished steel prices rose by INR 200-500/t d-o-d, supported by steady buying interest in finished steel products.
Scrap buying remained moderate today, as local steelmakers in Mandi began increasing bookings. However, bid-offer gaps continued, driven by adequate mill inventories and healthy scrap arrivals in the region.

Raw material and steel market trends
In Mandi Gobindgarh, sponge iron prices gained INR 400/t d-o-d to INR 34,300/t DAP, though prices were down INR 280/t w-o-w. In Ludhiana, pig iron prices rose INR 100/t d-o-d to INR 43,800/t DAP but declined by INR 500/t amid cautious buying.
In the finished steel segment, Mandi ingot prices increased INR 500/t d-o-d to INR 47,000/t but declined by INR 1,000/t w-o-w as trade activity stayed subdued. Rebar ex-mill prices improved by INR 100/t d-o-d to INR 51,900/t but decreased by INR 960/t.
End-user demand in the northern region remained limited, weighed down by the continuous decline in steel prices.

Alang scrap market
Alang’s ship-breaking melting scrap prices (HMS 80:20) declined by INR 200/t d-o-d to INR 36,300/t ($378/t) ex-yard on 25 September, as softer steel prices across key domestic markets weighed on sentiment. The drop followed parallel weakness in billet and finished steel values in Gujarat and Mandi Gobindgarh, pointing to subdued downstream demand and limiting near-term upside for scrap. Market participants noted cautious procurement from local processors, with buyers preferring smaller lots amid inventory cover and steady arrivals from ship-breaking activity.
Mumbai steel market
IF route rebar (Fe 500) prices in Mumbai held steady d-o-d today at around INR 51,400/t ex-works, with buying activity confined to need-based procurement. Market participation remained subdued, with only moderate enquiries reported across the session.
In the scrap segment, HMS (80:20) prices softened by INR 150/t to INR 36,350/t DAP, reflecting cautious sentiment amid limited finished-steel support. A leading Mumbai steelmaker reportedly booked around 250 t of HMS (80:20) at INR 36,200-36,300/t DAP, while approximately 2,700 t of HMS (90:10) changed hands at INR 37,250-37,350/t DAP.
Upcoming scrap auctions

Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,200-5,600/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $368-369/t, approximately INR 37,650/t (inclusive of freight). HMS (80:20) prices in Mumbai dipped by INR 150/t d-o-d to INR 36,350/t DAP. Indicative prices of shredded from Europe stood at $410/t CFR Nhava Sheva
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 15,900/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply