- Domestic aluminium prices decline as cautious buying weighs on demand
- MCX and LME aluminium prices fall w-o-w despite lower exchange stocks
Domestic aluminium prices in India declined w-o-w, while MCX and LME aluminium prices also eased during the week. Expectations of improving global supply weighed on benchmark prices, as smelter restarts and higher Chinese output raised availability prospects. However, historically low LME inventories and ongoing Middle East supply disruptions continued to provide underlying support.
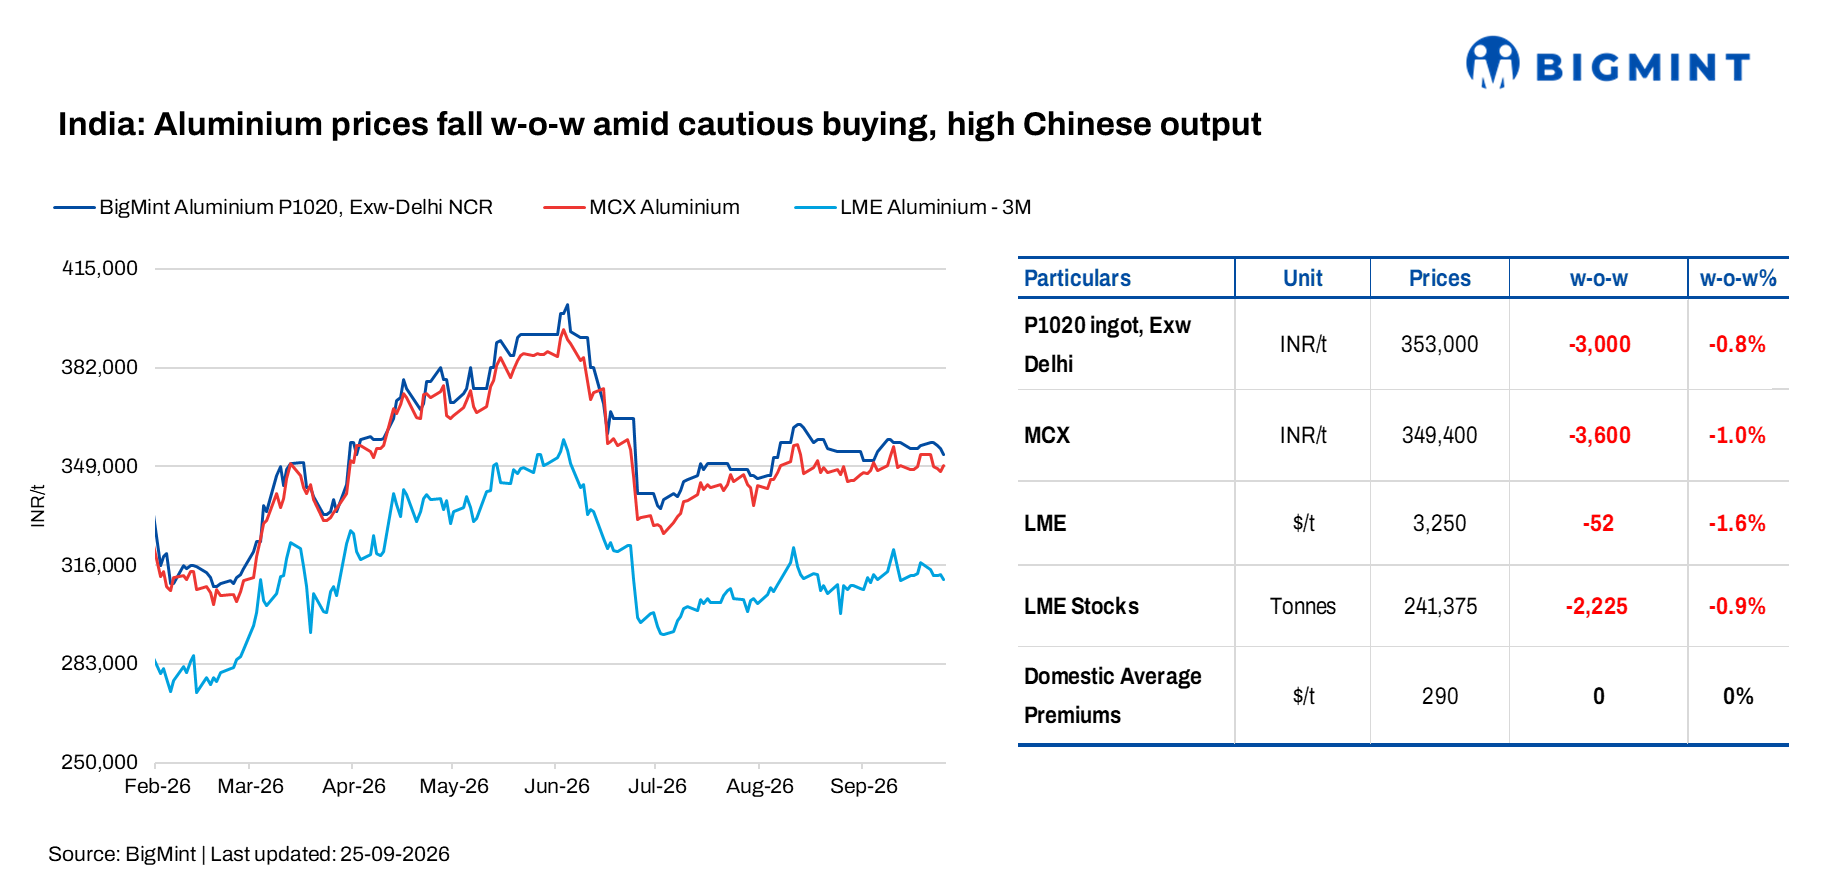
According to BigMint’s assessment, P1020 aluminium ingot prices in Delhi NCR declined by INR 3,000/t, or 0.8%, w-o-w to INR 353,000/t on 25 September, from INR 356,000/t on 18 September.
How did Indian and global exchanges perform?
Domestic aluminium futures on the MCX declined by INR 3,600/t, or 1.0%, w-o-w to INR 349,400/t on 25 September, from INR 353,000/t a week earlier.
Meanwhile, three-month aluminium prices on the LME fell by $52/t, or 1.6%, w-o-w to $3,250/t on 25 September, from $3,302/t on 18 September. Prices weakened as expectations of improving availability offset support from tight exchange stocks.
LME aluminium inventories declined by 2,225 t, or 0.9%, w-o-w to 241,375 t. Stocks remained close to historically low levels, limiting the downside despite the recent price correction.
China’s primary aluminium production reached a record 3.98 mn t in August, up 4.7% y-o-y, as strong margins encouraged smelters to maintain high operating rates.
Market updates
India’s imported aluminium scrap market remained subdued this week. Ganesh Chaturthi holidays reduced trading activity and spot enquiries, while buyers maintained a cautious approach to procurement.
In contrast, domestic aluminium Tense scrap demand improved gradually. Buyers increased enquiries while preparing for September requirements. Declining inventories of competitively priced imported ADC12 could prompt alloy producers to return to the market for fresh purchases.
On the demand side, China’s aluminium consumption remains mixed. Weakness in the property sector continues to weigh on traditional construction-related demand, while industrial segments are showing relatively better resilience.
China’s aluminium exports also remained elevated, with unwrought aluminium and aluminium product exports reaching 626,000 t in August, up 17.2% y-o-y. This indicates that strong overseas shipments continue to provide an outlet for high domestic production.
Outlook
Domestic aluminium prices are expected to remain rangebound in the near term. Historically low LME inventories and continued supply disruptions in the Middle East could limit the downside.
However, improving global supply, record Chinese output and cautious domestic buying may keep prices under pressure. A gradual improvement in domestic scrap demand could provide some support, particularly as imported ADC12 availability tightens.
Overall, the market is likely to remain balanced between persistent supply constraints and expectations of improving availability.
Leave a Reply