- Higher freights support October price gain hopes
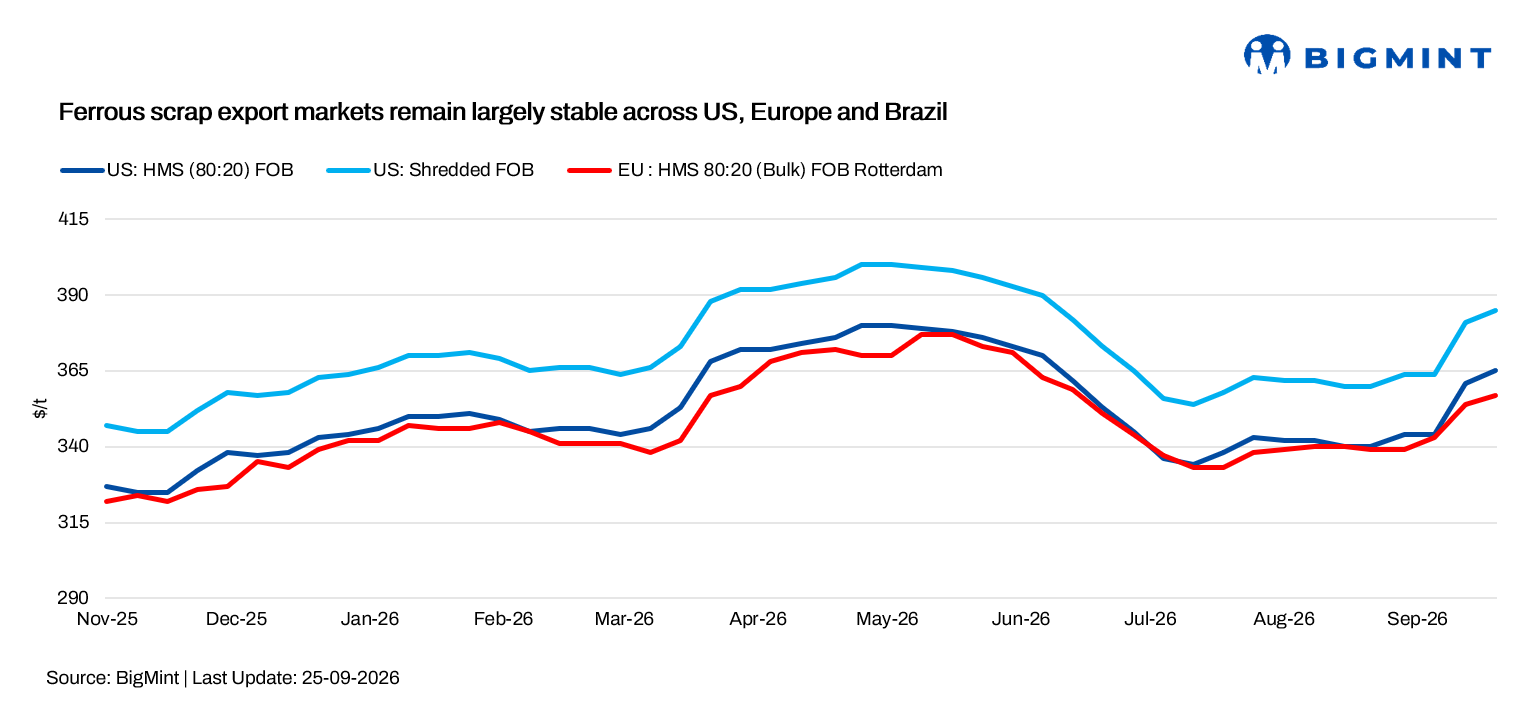
- Rotterdam HMS 80:20 rises $3/t to $357/t FOB
Ferrous scrap export markets remained largely stable on 25 September, with firm export values, elevated logistics costs and limited scrap availability providing underlying support. US export prices strengthened on stronger Turkish demand, while subdued mill buying and logistical challenges kept European and Brazilian markets rangebound.
US
US ferrous scrap prices remained unchanged on 25 September, while stronger export values and rising transportation costs increased the potential for higher prices in October.
Export values strengthened, with FOB HMS prices rising $4/t to $365/t and shredded scrap increasing $4/t to $385/t. Higher export prices were supported by stronger Turkish demand amid disruptions to alternative billet supply routes.
Rising oil prices and higher freight costs continued to increase transportation expenses for both imported and domestic scrap. Market participants expect these higher costs and firm export values to provide support to US scrap prices in October.
Domestic busheling was assessed at $465-475/t DAP Midwest and $450-455/t DAP Southeast. Shredded scrap held at $412-415/t in both regions, while plate and structural scrap remained at $410-412/t Midwest and $394-396/t Southeast. HMS prices were unchanged at $355-360/t Midwest and $360-365/t Southeast.

Europe
The ferrous scrap market remained largely stable in the second half of September, with limited changes from August. E3 heavy melting scrap was assessed at Euro 310-315/t ($354-359/t) DAP and E8 new production scrap at Euro 320-325/t ($365-370/t), both unchanged, while E40 shredded scrap increased slightly to Euro 325-330/t ($370-376/t).
Higher logistics costs and transport disruptions provided some support, but subdued mill demand limited price gains. Low water levels on the Rhine continued to disrupt scrap movement, while road and rail deliveries also faced difficulties.
BigMint’s weekly assessment for Rotterdam HMS 80:20 increased by $3/t w-o-w to $357/t FOB.
In the UK, scrap prices remained broadly stable in the second half of September, supported by elevated collection and freight costs despite limited buying interest. Dockside prices were largely unchanged over the past two weeks, while scrap inflows into yards have yet to fully recover.
HMS 80:20 collection prices were heard at around GBP 220-230/t ($291-305/t) DAP, while higher-value alloyed scrap was trading at a premium.
Turkish mills remained active in deep-sea scrap procurement, but no UK-origin bookings were reported. High collection and freight costs, along with limited alternative supply, are expected to keep UK scrap prices supported despite softer Turkish demand.
Brazil
Brazilian ferrous scrap prices remained unchanged w-o-w by 25 September, as lower steel mill bids were rejected by sellers, keeping the market stable.
Domestic HMS 80:20 stood at BRL 800/t ($154/t) FOT, clean steel scrap at BRL 900/t and turnings at BRL 700/t ($173/t). Export prices also held steady at $300-305/t FOB for HMS 80:20 and $325-330/t FOB for shredded scrap.
Trading activity remained slow, with scrap volumes estimated to be around 40% lower. Limited material availability prevented dealers from accepting lower bids, while high mill inventories, changed procurement strategies and payment delays kept market activity subdued.
Leave a Reply