- India pellet export prices edge up, but Chinese buying remains subdued
- Firm domestic realisations continue to limit export availability
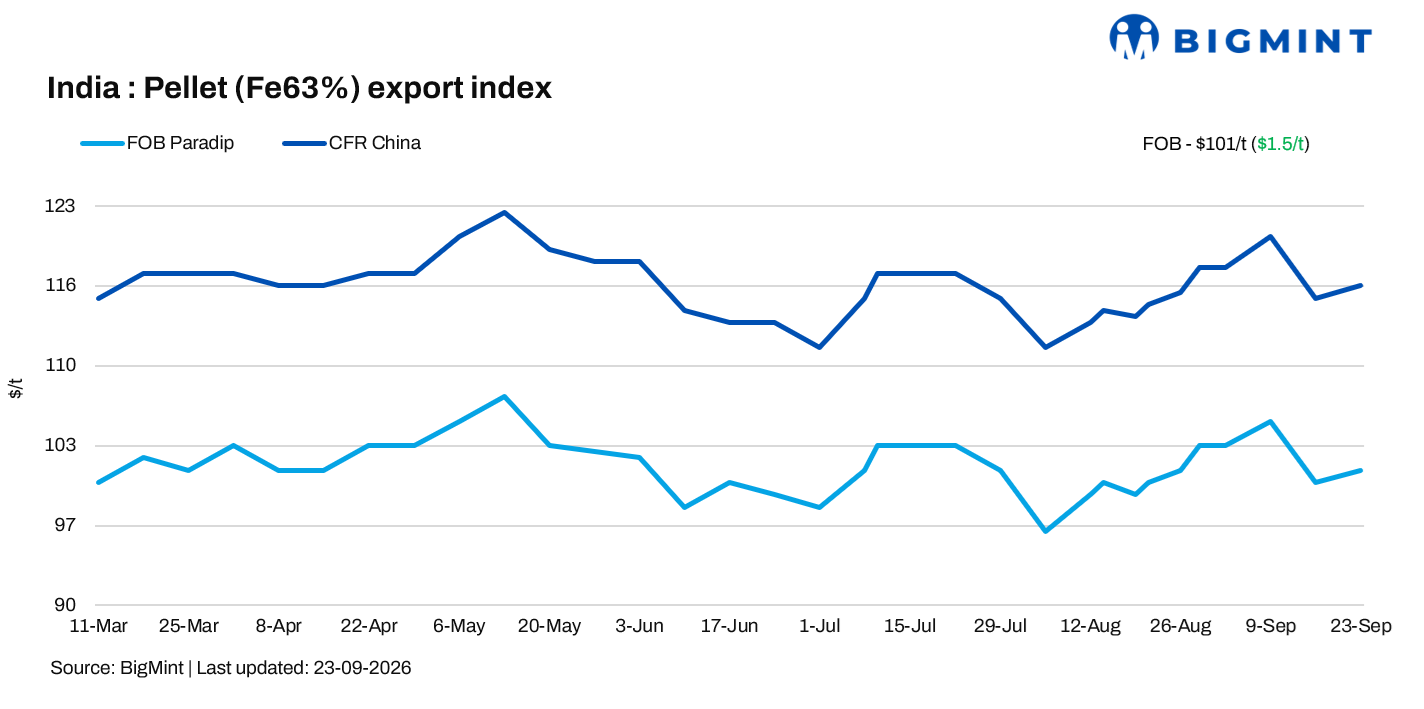
BigMint’s India pellet export index rose by around $1.5/t w-o-w to $101/t FOB East Coast on 23 September 2026, equivalent to around $116/t CFR China. The recovery was almost negligible post the decline of $4-5/t observed last week in pellet export index due to persistent weakness in global Fe 61% iron ore fines price.
Chinese pellet inventories at 34 major ports inched up marginally to around 5.73 million tonnes (mnt), compared with 5.69 mnt a week earlier. While lower inventories offered some underlying support to pellet demand, aggressive restocking has yet to emerge as several Chinese mills remain cautious amid uncertainty over potential steel production cuts.
Rationale
- Zero (0) confirmed deals from India’s east coast were recorded in this publishing window for T1 trade, and, therefore, this category was allotted 0% weightage for today’s price calculations. Click here for the detailed methodology.
- Ten (10) bids, offers, and indicative prices were heard, of which seven (7) were considered for the calculation of the index and given the balance 100% weightage.
Market updates
Chinese mills remained cautious on fresh pellet procurement, despite pellet inventories at major Chinese ports edging slightly higher last week, indicating some limited replenishment. A Chinese trader and an international trader told BigMint that buying sentiment remains weak across both portside and spot markets, as subdued steel production continues to weigh on demand. Several mills remain under maintenance, while some have announced production cuts, reducing the need for urgent or aggressive raw-material procurement.
However, another international trader noted that some fresh restocking was heard ahead of the upcoming Golden Week holiday. The replenishment was largely concentrated on fines and lumps, with no significant improvement seen in pellet inventories.
On the domestic front, Indian pellet sellers remain focused on previously booked orders and ongoing dispatches. Many producers are already well-booked for domestic sales, while those with available material are achieving significantly better realisations in the domestic market. The premium over export realisations is estimated at around INR 1,700-1,800/t on an ex-plant basis, leaving little incentive for sellers to actively pursue export business.
Maintenance at some pellet plants across key producing regions has also tightened near-term domestic availability, providing additional support to domestic prices.
A domestic seller indicated that Indian pellet exports are likely to remain muted until the international iron ore fines index reaches at least $102-103/t CFR China. For pellet exports, sellers are reportedly seeking levels above $116-118/t CFR China, equivalent to around $102-104/t FOB East Coast India, before actively considering export opportunities.
Overall, the pellet export market remains subdued, mainly due to stronger domestic realisations and weak Chinese buying interest. However, the current domestic price rally could lose some momentum as monsoon-related supply constraints ease. With improving availability after the monsoon, Indian pellet exports could gradually regain traction from mid-October onwards, subject to a recovery in international iron ore prices and Chinese demand.

Domestic vs export market
Pellet export realisations for Fe 63% were recorded at INR 7,500/t ($78/t), gaining by INR 100/t this week, while domestic realisations (Fe 62.5%) edged down slightly by INR 50/t w-o-w to INR 9,500/t ($99/t) exw. Thus, the gap shrinked by INR 150/t w-o-w to INR 1,650/t making it still unrealistic for exports to take place.
Factors impacting pellet exports
Chinese iron ore fines prices showed weakness w-o-w: The benchmark iron ore fines Fe 61% index remained rangebound at $95/dmt CFR China on 22 September. The recovery remains weak and slow physical buying in China with expectations of higher freight costs and tighter seaborne availability from major exporters. Some physical market activity picked up significantly throughout the week, particularly at ports, where trading volumes increased slightly due to restocking before the holidays.
DCE iron ore futures surge w-o-w: Iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract settled at RMB 715.5/t on 22 September rising by RMB 7/t, indicating slight optimism during the restocking session .
Outlook
BigMint expects pellet exports to remain subdued in the near term, with firm domestic realisations keeping sellers focused on local sales. Export activity could improve from mid-October as monsoon-related supply constraints ease, but a sustained recovery will depend on stronger Chinese demand and higher international iron ore prices.
Leave a Reply