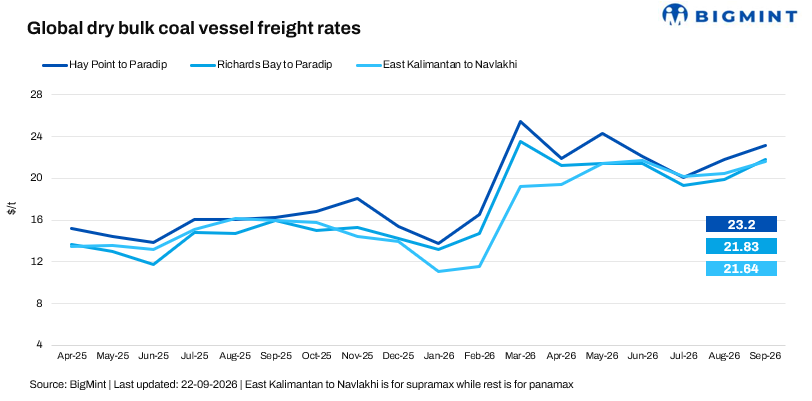
- Panamax stays broadly flat amid limited fixing, cautious Pacific activity
- Supramax sentiment firms on tighter tonnage, but coal bookings remain limited
India-bound coal freight markets held a firm-to-stable tone in the week ended 22 September 2026, with rising bunker costs and tighter vessel availability lending support to rates. But the physical market remained selective, as limited fixtures and uncertainty over October loading prices kept Charterers on the sidelines.
A shipbroker said, “The market remains firm, with bunker prices also moving higher. Sentiment is positive across the major segments, with Capesize, Supramax and Handymax showing firm conditions, while Panamax remains broadly flat. Enquiries are present, although overall activity and fixtures remain limited.”
Route-wise update

The Australia-India Panamax market remained largely unchanged as Pacific activity lacked momentum and fresh fixing was limited. Seasonal demand and vessel positioning for September and October are providing a floor to sentiment, but Charterers remain cautious in a volatile market.
The South Africa-India Panamax route has seen better enquiry levels, helped by a firmer Atlantic backdrop. However, the lack of sufficient fixing has kept the route contained, with owners finding support but limited room to push rates further.
A shipbroker said, “The market is showing a positive tone, with seasonal demand and tightening vessel availability expected to support freight through September and October. Capesize, Supramax and Handymax are firm, while Panamax is relatively flat.”
The Indonesia-India Supramax market presents a more mixed picture. Tighter tonnage is lending support, but this is being countered by weak coal booking activity. A lack of clarity on October loading prices is also making Charterers hesitant to commit.
A shipbroker said, “Coal is currently being offered at lower levels, with no coal bookings reported so far this week, resulting in increased vessel availability. Bunker prices have risen again, further weighing on booking activity, while there is still limited price clarity among Charterers for October loading cargoes.”
Despite the cautious physical market, sentiment remains constructive. Another shipbroker said, “The market remains volatile, with freight sentiment firm to stable. Seasonal demand and vessel positioning are expected to provide support through September and October. Enquiry levels have improved, although fixing activity remains relatively limited at this stage.”
Outlook
The market is entering the next few weeks with a firm undertone but limited fixing. Seasonal demand, vessel positioning, tighter availability and higher bunker costs continue to underpin owners’ rate ideas. The key question now is whether fresh coal bookings and clearer October pricing can convert the current firm sentiment into stronger physical activity. Until then, the market is likely to remain selective and volatile.
Leave a Reply