- Higher HRC, billet prices pull market upwards
- Healthy pellet demand lends support to offers
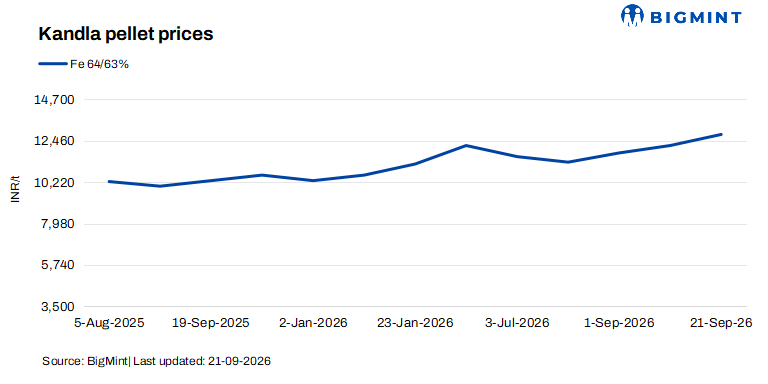
Jindal SAW has raised its iron ore pellet offers (Fe 63±0.5%) for the Kandla market by INR 400/t ($4) m-o-m to INR 12,600/t DAP. The increase was driven mainly by healthy demand from sponge iron producers, higher raw material costs and a firmer global iron ore market.
Market participants noted that the recent rise in semi-finished and finished steel prices has increased input costs, supporting higher pellet realisations. Continued upward revisions by sellers in neighbouring markets have also strengthened the price trend.
Meanwhile, limited availability of lumps and pellets in the domestic market, along with strong bids for Odisha iron ore lumps, which fetched premiums of around INR 1,250/t ($13/t) on a monthly average basis, has reinforced the view of tighter raw material availability.
Key factors driving prices
- South African lumps prices increase m-o-m: South African lumps prices at CNF Kandla averaged around $115.5/t so far in September 2026, up $3/t from August. The increase was largely in line with the rise in global iron ore prices in China. However, elevated lump prices have reduced their cost competitiveness, improving the viability of pellets. Demand for lumps has also remained relatively subdued as buyers remain cost-conscious amid tighter margins.
- Global iron ore (Fe 61%) prices remain healthy: The benchmark Fe 61% iron ore fines price averaged $98/dmt CFR North China so far in September, up $2/dmt m-o-m from August. The market recovered from the weakness seen last month amid renewed buying for restocking after a period of subdued demand and scheduled mill maintenance. Further procurement is expected this week, providing continued support to prices.
- Billet prices increase m-o-m: Ahmedabad billet prices have risen by INR 4,000/t m-o-m to INR 46,800/t so far in September, reflecting relatively firm market sentiment and healthy buying. However, prices stood at INR 47,200/t today, down INR 600/t d-o-d. The recent moderation in finished steel demand and lower buying appetite among secondary steelmakers could limit pellet consumption going forward.
- Finished steel prices jump m-o-m: Ahmedabad’s HRC index (exy) increased by INR 3,850/t m-o-m to INR 58,750/t in August. Sellers have raised prices amid modest improvement in finished steel demand and higher raw material costs across markets.
- Jabalpur’s concentrate prices increase m-o-m: Iron ore concentrate prices in Jabalpur increased by INR 150/t m-o-m to INR 4,800/t in September, adding to feedstock costs for pellet producers. Supply concerns have also persisted due to disruptions in mining operations during the monsoon, keeping raw material availability relatively tight.
Outlook
BigMint expects pellet prices to remain supported in the near term, underpinned by healthy demand and tight raw material availability. However, the current firmness is likely to gradually fade as the monsoon recedes, mining and material movement improve, and domestic supplies normalise. Buying is expected to remain need-based, keeping prices supported in the interim.
Leave a Reply