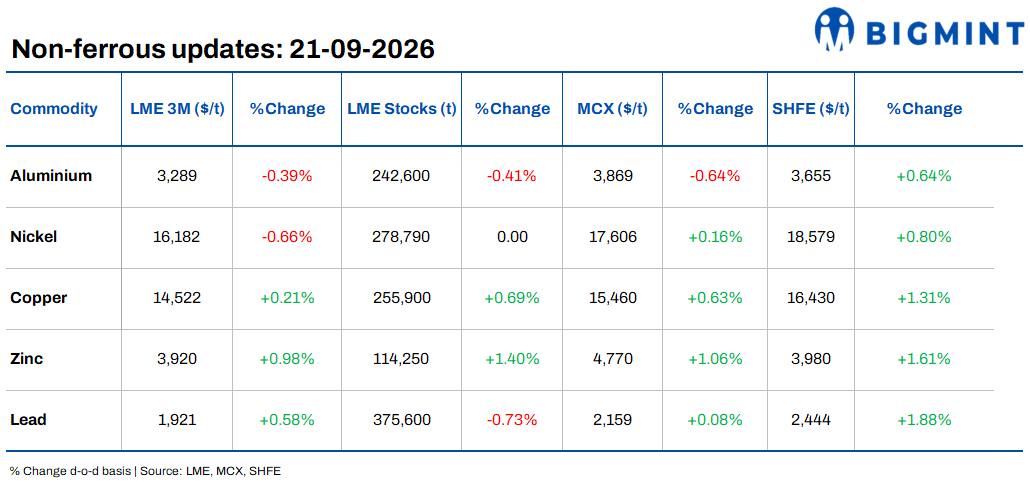
- Zinc leads LME gains; nickel and aluminium decline
- China’s Aug’26 aluminium output hits record high
LME base metals traded mixed on 18 September, with zinc leading the gains, rising 0.98% d-o-d to $3,920/t. Lead followed with a 0.58% increase to $1,921/t, while copper edged up 0.21% to $14,522/t. Aluminium fell 0.39% to $3,289/t, while nickel declined 0.66% to $16,182/t.
LME inventories moved in mixed directions. Zinc stocks rose 1.40% to 114,250 t, the largest increase among the metals, while copper inventories gained 0.69% to 255,900 t. Lead stocks fell 0.73% to 375,600 t, and aluminium inventories declined 0.41% to 242,600 t. Nickel stocks were unchanged at 278,790 t.
Domestic market overview
India’s non-ferrous scrap market witnessed mixed trends on 18 September. Aluminium tense scrap remained unchanged at INR 253,000/t ex-Delhi and INR 250,000/t ex-Chennai.
Meanwhile, aluminium P1020 ingot, ex-Delhi NCR, rose by INR 1,000/t, or 0.3%, to INR 357,000/t from INR 356,000/t. MCX aluminium declined 0.64% d-o-d. The domestic increase in P1020 prices contrasted with softer LME and MCX aluminium markets.
Copper armature scrap (Cu 99%), ex-Delhi, rose by INR 14,000/t, or 1.1%, to INR 1,330,000/t from INR 1,316,000/t. Meanwhile, MCX copper advanced 0.63%, supporting firmer domestic copper scrap prices.

Other updates
Oil falls as diplomacy hopes improve, but Middle East risks persist
Brent crude fell 2.08% to $102.28/bbl on 21 September as hopes of US-Iran diplomacy eased geopolitical risk. Meanwhile, Saudi exports recovered to more than 4 million bpd from 2.4 million bpd in August. However, only 12 commodity vessels crossed the Strait of Hormuz over the latest weekend, versus around 125/day before the conflict, keeping freight and energy risks elevated.
China records highest aluminium output as Gulf smelters restart
China produced a record 3.98 mnt of primary aluminium in August, up 4.7% y-o-y, while January-August output rose 3.9% to 31.12 mnt. Meanwhile, EGA has restarted 315 of 1,262 reduction cells at Al Taweelah, with full restoration targeted for Q1 2027. Aluminium Bahrain is also operating at an annualised 1.3 mnt. Higher Chinese output and recovering Gulf production could improve medium-term availability, although low inventories and logistical constraints continue to support physical markets.
EU Parliament backs wider CBAM coverage for downstream aluminium
The European Parliament adopted its negotiating position on 15 September to expand CBAM coverage to downstream products containing significant aluminium or steel content. The proposal covers 457 products, including wire, fasteners, springs and household articles, compared with 180 in the European Commission’s original proposal. The move aims to reduce carbon leakage and circumvention through downstream trade. However, negotiations with EU member states are still required, while proposed changes targeting downstream products are intended for implementation from 2028.
China’s zinc output falls as concentrate availability tightens
Chinese refined zinc production fell 1.8% y-o-y to 639,000 t in August, marking the first annual decline in almost a year. Smelter maintenance, mining disruptions, negative spot treatment charges and elevated domestic inventories contributed to the reduction. Meanwhile, concentrate shortages have intensified following disruptions at Antamina in Peru and Red Dog in Alaska, alongside restrictions affecting Iranian ore shipments, indicating tighter near-term supply conditions.
Leave a Reply