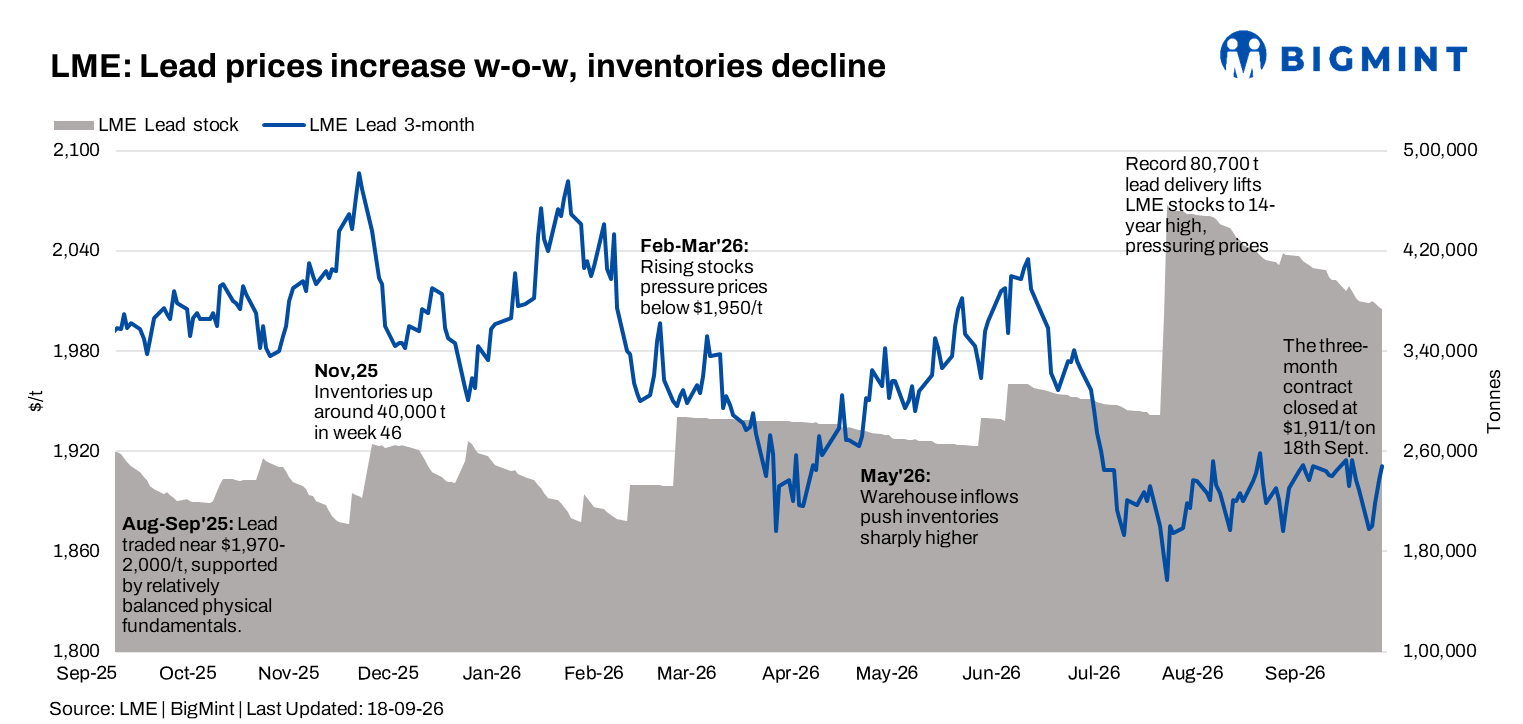
- LME lead rises 0.7% w-o-w as inventories fall 6,400 t
- Battery operating rates improve amid seasonal demand
London Metal Exchange (LME) lead prices recovered during the week as continued inventory drawdowns and improving battery production provided support.
LME lead cash-settlement prices increased 0.8% to $1,868/t on 18 September from $1,854/t on 11 September. The three-month contract rose 0.7% to $1,911/t from $1,897/t.
Meanwhile, LME lead inventories declined by 6,400 t, or 1.7%, to 373,625 t from 380,025 t. Since 21 August, stocks have fallen by 43,225 t, or 10.4%.
LME inventories continue to decline
LME lead stocks continued their downward trend, falling from 380,025 t on 11 September to 373,625 t on 18 September.
The latest drawdown takes cumulative inventory losses since 21 August to more than 43,000 t. However, stocks remain above 370,000 t, limiting the impact of tighter exchange availability on prices.
The cash-to-three-month spread remained at around $43/t backwardation, indicating continued near-term tightness.
Battery operating rates improve
Lead-acid battery production improved during the week amid seasonal demand.
The operating rate of lead-acid battery producers across five provinces in China rose to 72.05% during 11-17 September, up 1.65 percentage points w-o-w. Seasonal demand and improved orders supported production.
Downstream enterprises also increased lead-ingot procurement ahead of the Mid-Autumn Festival and National Day holidays. However, pre-holiday stockpiling is expected to moderate in the coming week.
MCX lead gains as open interest rises
MCX lead prices increased during the week. The 30 September contract closed at INR 197.50/kg on 18 September, compared with INR 196.40/kg on 11 September, gaining 0.6%.
Open interest increased from 666 lots to 717 lots, up 7.7%, indicating higher market participation alongside the price recovery.
HZL lead benchmark declines
Hindustan Zinc Ltd (HZL) reduced its lead benchmark by INR 1,700/t on 17 September to INR 211,400/t.
The latest cut followed a INR 400/t increase on 10 September, when the benchmark was raised to INR 212,200/t.
Outlook
BigMint expects LME lead prices to remain range-bound in the near term, with falling inventories and improving battery production providing support, while elevated stocks and cautious physical demand could limit the upside.
LME inventories have fallen by more than 43,000 t since 21 August, while the cash-to-three-month spread remains in backwardation. However, stocks above 370,000 t continue to indicate ample exchange availability.
In China, battery operating rates have improved, although downstream procurement is expected to ease after pre-holiday stockpiling. In India, MCX lead has moved higher, while HZL’s latest benchmark reduction provides a counterpoint to the international price recovery.
Market participants will monitor LME inventory movements, battery operating rates, downstream demand, lead-ingot imports and domestic prices.
LME lead is expected to trade in a range of $1,890-1,925/t in the near term
Leave a Reply