- Weak buying keeps scrap market under pressure
- Semis, finished steel prices fall by INR 100-300/t d-o-d
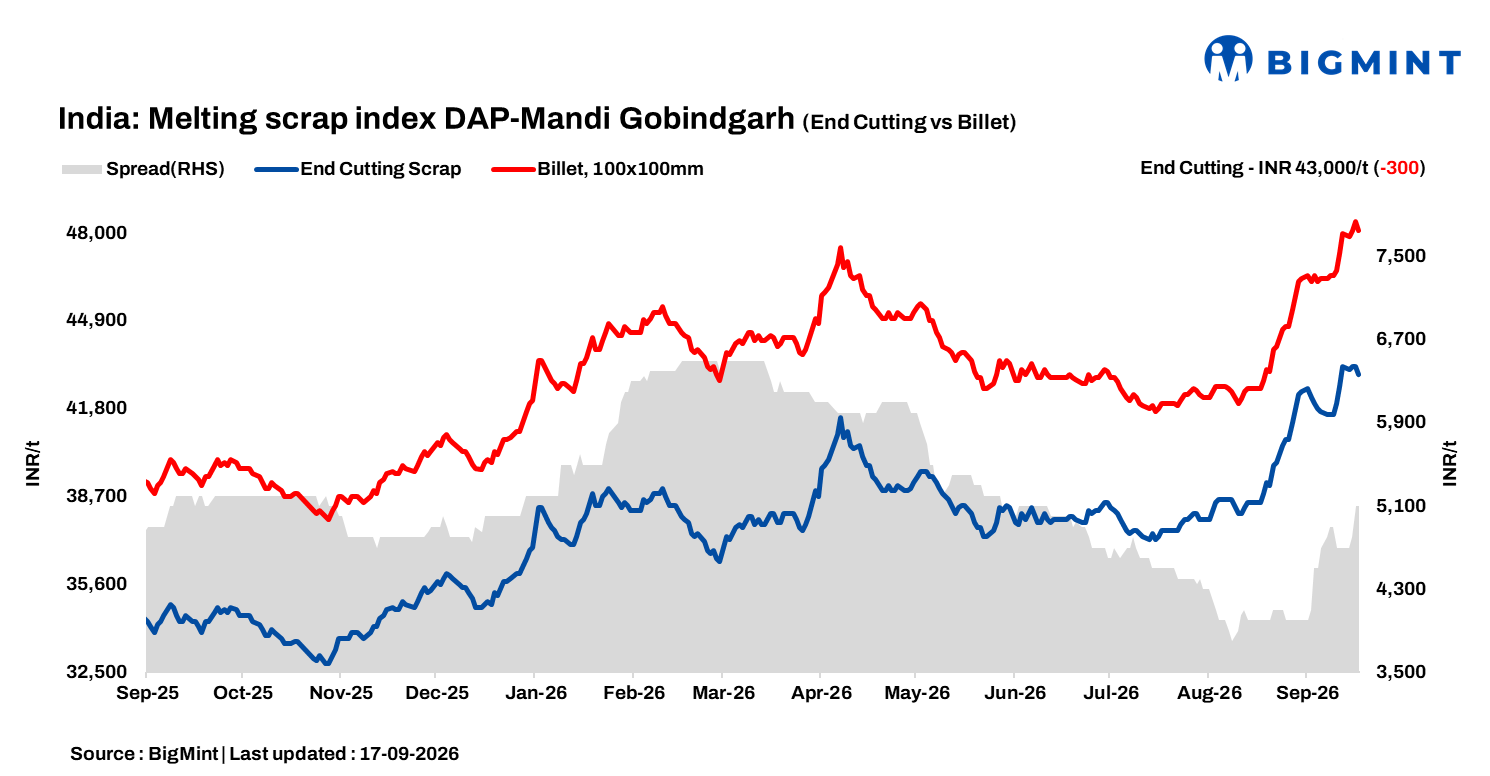
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, fell by INR 300/t d-o-d to INR 43,000/t DAP on 17 September 2026.
Mandi Gobindgarh’s scrap market remained under pressure on Thursday as major buyers maintained a cautious purchasing approach amid thin transaction volumes. Increased scrap arrivals, coupled with comfortable inventory levels at mills, weakened immediate buying interest and compelled local sellers to lower their offers to attract bookings.
The weakness in scrap was further reinforced by the decline in semi-finished and finished steel prices, which fell by approximately INR 100-300/t. Lower ingot and finished steel realisations reduced steelmakers’ ability to absorb high scrap costs, prompting them to seek lower purchase levels and limit fresh bookings.
Market participants noted that trading activity remained thin, while sellers faced increasing pressure to align offers with prevailing steel prices. Unless buying interest improves or finished steel prices stabilise, market sentiment in Mandi Gobindgarh is likely to remain cautious in the near term.
Alternative raw material prices
Sponge iron (CDRI) prices in Mandi Gobindgarh eased by INR 200/t d-o-d to 34,300/t DAP, while steel-grade pig iron prices in Ludhiana remained stable d-o-d at INR 44,000/t DAP.
Steel market
Mandi Gobindgarh ingot prices declined by INR 300/t d-o-d to INR 48,100/t DAP on Thursday, pressured by weak buying interest and a subdued market trend. Prices across other major trading hubs also fell by INR 250-500/t.
In the finished steel segment, rebar prices decreased by INR 100/t d-o-d to INR 53,400/t ex-works, while HR strip (patra) prices edged down by the same amount to INR 52,800/t ex-works. Market activity remained subdued, with buyers adopting a cautious approach amid slow demand and limited trade enquiries. Overall sentiment continued to remain under pressure.
Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 4,800-5,300/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $372/t, approximately INR 37,900/t (inclusive of freight). HMS(80:20) prices in Mumbai remained stable d-o-d at INR 36,600/t DAP. Indicative prices of shredded from Europe stood at $412/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 15,050/t as of 16 Sep’26. The Raipur secondary steel market remained closed today due to Vishwakarma Puja.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply