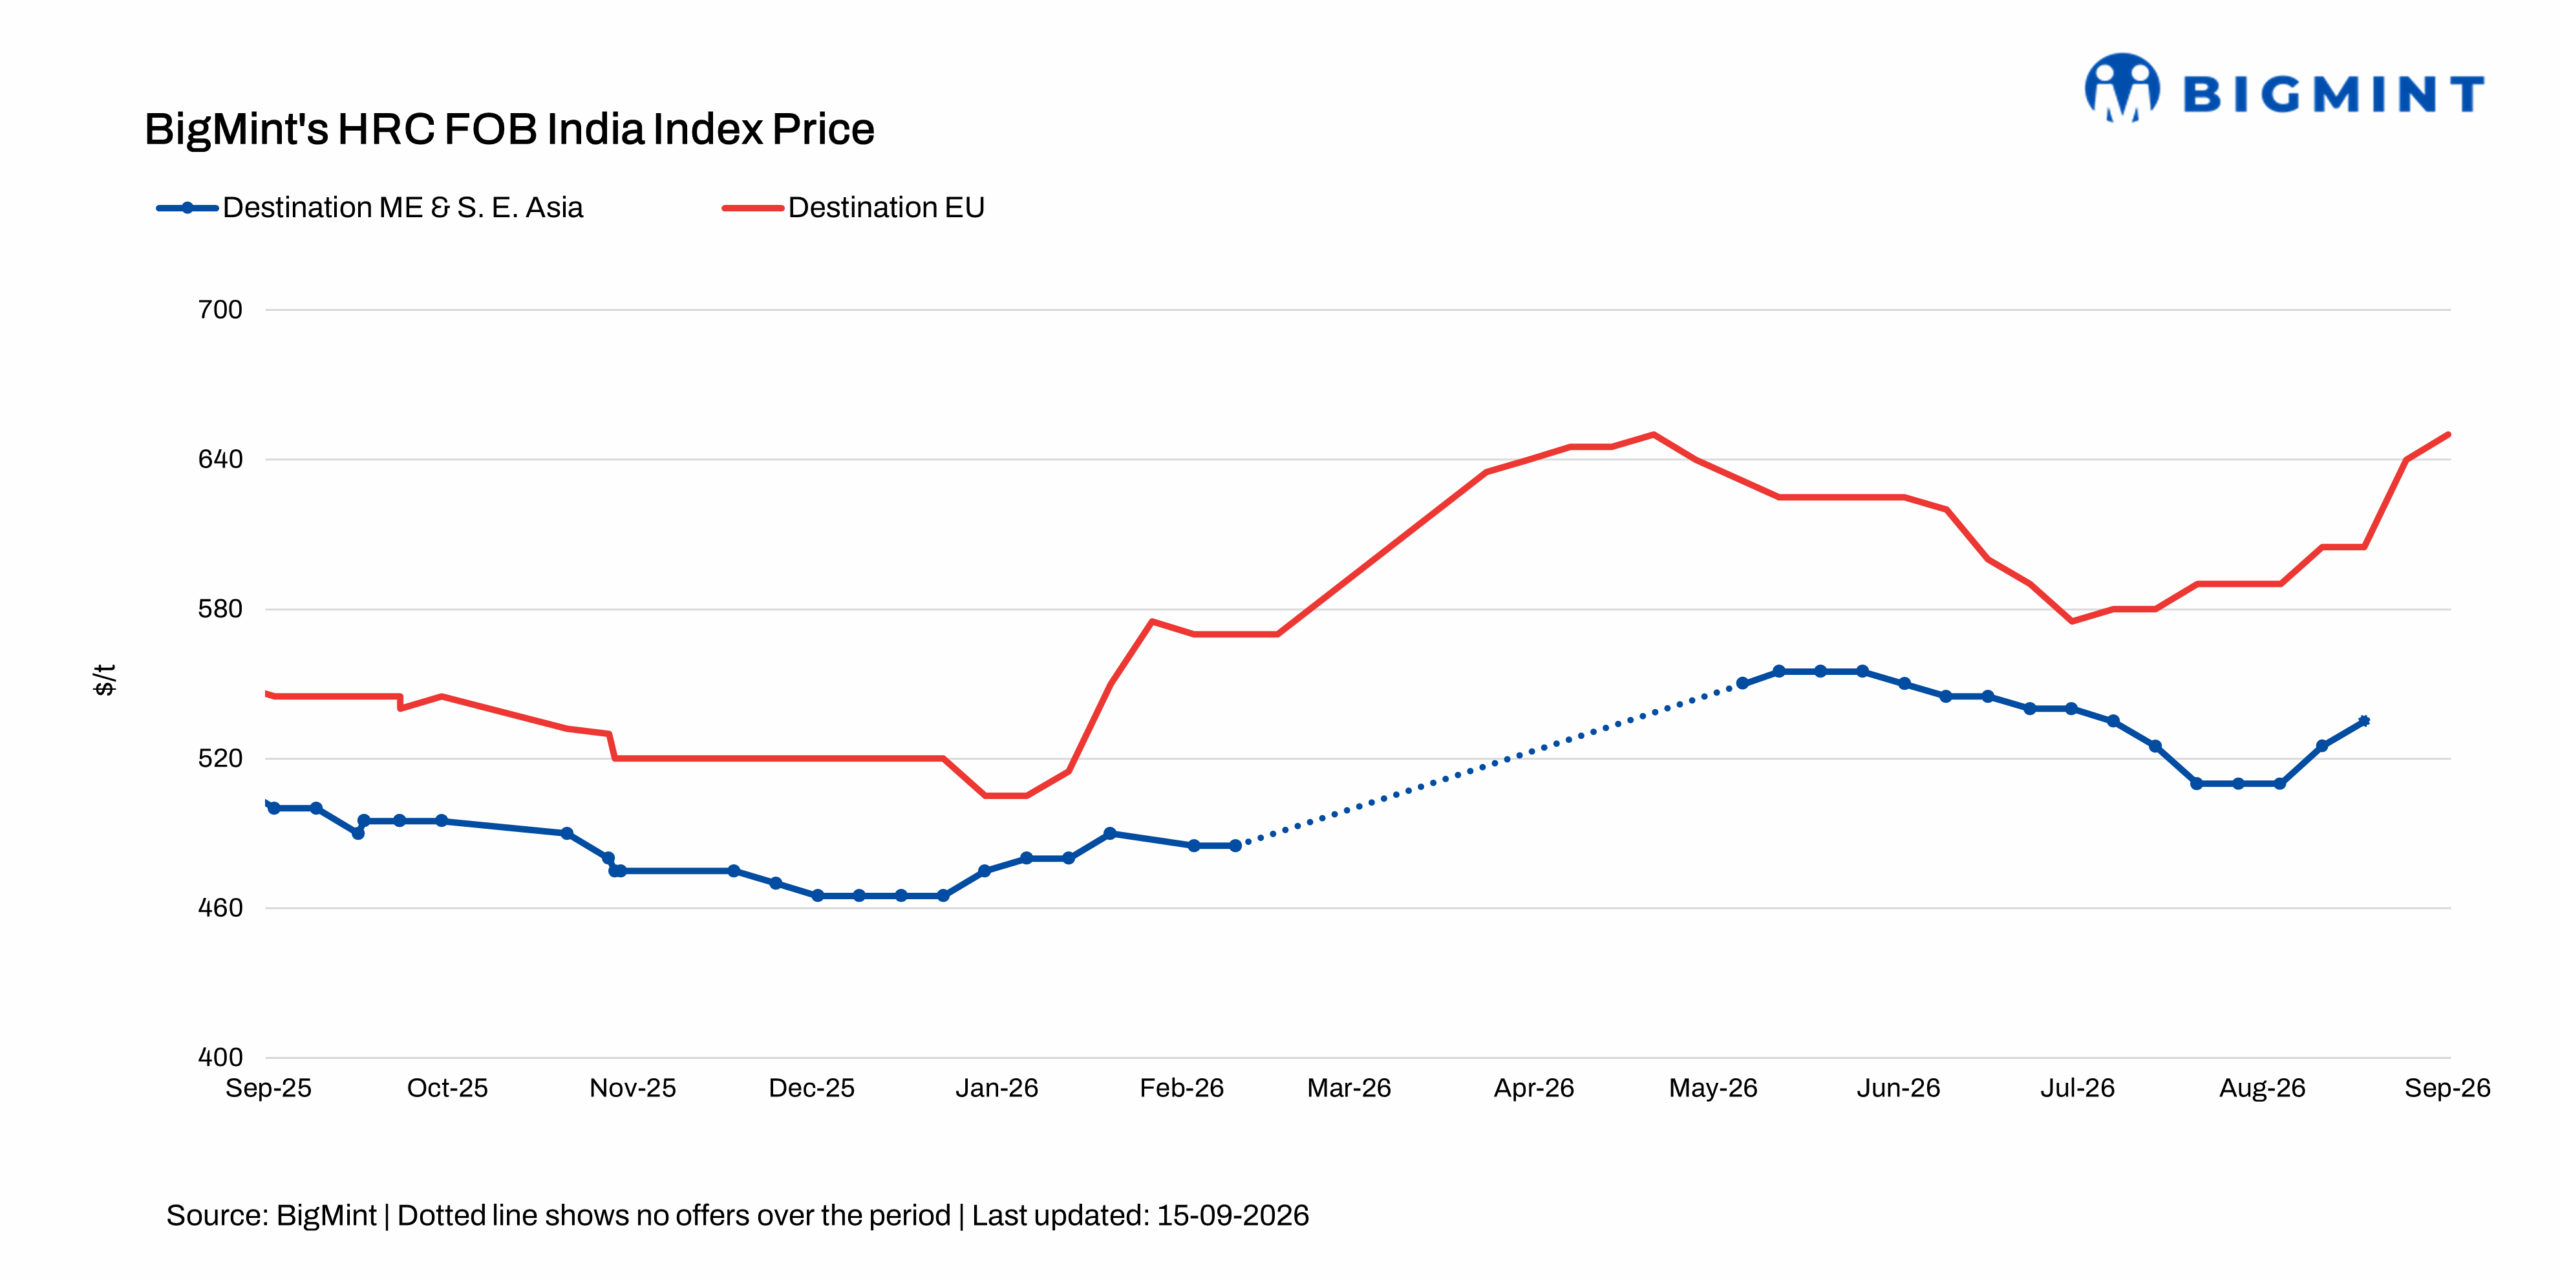
- EU offers rise on stronger domestic realisations, selective Q1 bookings
- Middle East and Vietnam offers remain on hold amid domestic focus
Indian HRC export offers showed mixed trends w-o-w across key destinations in the assessment week ended 15 September 2026. Offers to the EU increased w-o-w, supported by stronger domestic realisations, while those to the Middle East and Vietnam remained on hold as mills continued to prioritise domestic sales and most export allocations were already committed. In the EU, selective Q1 CY’27 bookings were reported, although higher offer levels continued to limit additional booking activity.
HRC export offers to EU rise w-o-w: Indian HRC export offers to the EU rose by around $10/t w-o-w to $650/t FOB, compared with $640/t a week earlier, as stronger domestic realisations led mills to seek higher export prices. Moreover, a booking of around 10,000 t was reportedly concluded at around $710/t CFR Antwerp for the Q1 CY’27 quota period, with freight estimated at around $70/t.
An EU-based source stated, “Although selective bookings have emerged, the higher Indian offer levels have made further business increasingly difficult, as mills continue to seek higher prices while buyers remain unwilling to match these levels. This has widened the gap between mills’ price expectations and buyers’ workable levels, limiting additional booking activity.”
HRC export offers to Middle East, Southeast Asia remain on hold: Indian HRC export offers to the Middle East and Vietnam remained on hold as mills continued to prioritise domestic sales amid stronger realisations and limited export availability. Most export allocations have already been committed, while stronger domestic prices have reduced the incentive for mills to actively pursue additional export business.
Outlook
Indian HRC export offers are expected to show mixed trends across key destinations in the coming week. EU offers are likely to remain elevated as stronger domestic realisations support mills’ higher export price expectations. While selective Q1 CY’27 bookings have emerged, the gap between mills’ price expectations and buyers’ workable levels is likely to keep further bookings limited. Meanwhile, offers to the Middle East and Vietnam are expected to remain on hold as mills continue to prioritise domestic sales and most export allocations remain committed.
Leave a Reply