- Firm global offers support import scrap prices
- Weak steel demand limits mill procurement
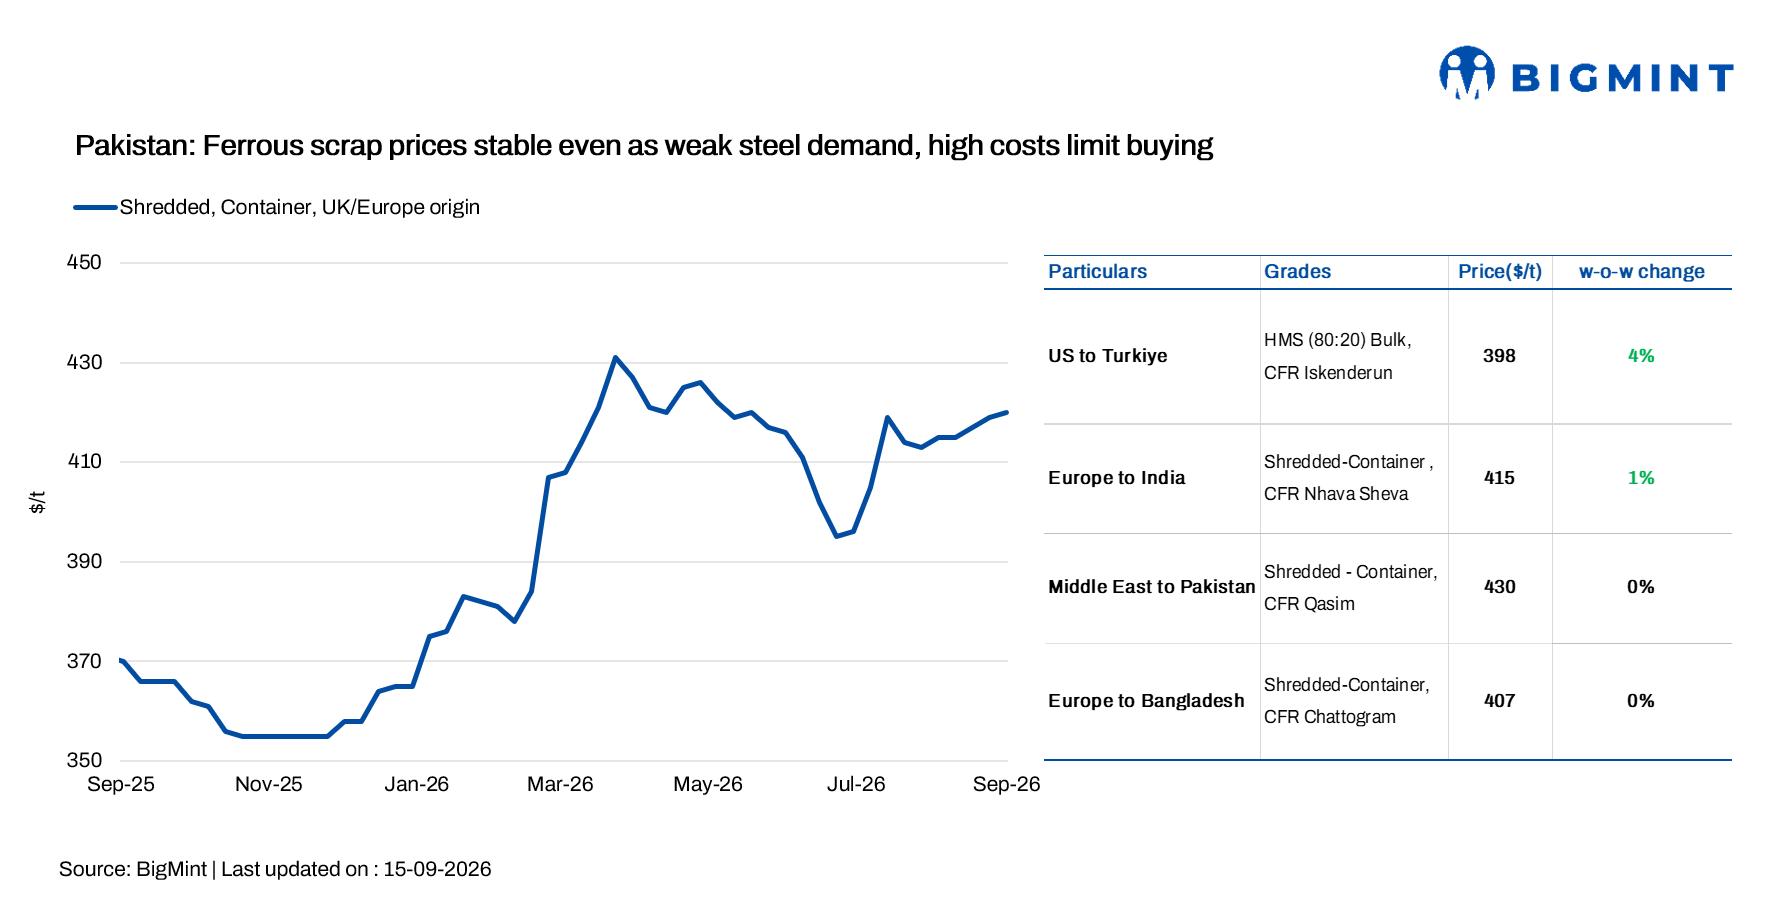
Pakistan’s ferrous scrap market remained largely stable during the week ended 15 September, as weak finished steel demand, narrow margins and a cash crunch kept buyers cautious. Heavy electricity bills and surcharges continued to strain mills’ finances, while higher freight costs and firm global scrap prices supported import offers. Transport disruptions, flooding, infrastructure damage, higher energy costs, new energy taxes and power-supply issues also weighed on market activity.
BigMint assessed Europe-origin shredded scrap at $420/t CFR Qasim, up $1/t w-o-w.
Market scenario
UK-origin shredded offers were heard at $420–425/t CFR Qasim, with recent indications around $420–422/t. A 1,000 t UK shredded cargo was sold at $417–418/t CFR Qasim. European shredded offers were reported at $424–425/t, while a recent 250 t EU shredded cargo was sold at $418/t. A 750 t HMS mixed blue steel cargo was sold at $410/t, while 200 t of Brazilian mixed blue steel and rolling scrap was booked at $430/t CFR Qasim.
Market indications for other origins remained firm. Offers from the EU, UK, US East Coast, UAE and Malaysia included HMS 80:20 grab load at $390–400/t, HMS 80:20/90:10 hand load at $400–410/t, shredded at $415–425/t, turnings at $340–350/t, LMS bundles at $340–345/t, PNS at $410–415/t and busheling bundles at $420–425/t CFR Qasim.
A 2,000 t Philippines-origin GI bundles cargo was sold at $360/t CFR Qasim. Chinese base-grade HRC was offered at $520–524/t CFR, with buyers targeting around $5/t lower, while other grades were offered at $528–531/t, against buying targets near $525/t.
Domestic market
Domestic scrap prices were pressured by selective mill buying and cash-flow constraints. Local scrap was quoted at PKR 134,000–135,000/t ($483-487/t) ex-Karachi, while other market indications placed levels at PKR 136,000–137,000/t ($491-494/t). Billet was assessed at PKR 208,000–212,000/t ($750-765/t) ex-works, while Punjab rebar was at PKR 234,000–235,000/t ($844-848/t). Branded rebar from major mills carried a premium of around PKR 8,000–10,000/t ($29-36/t).
Mill operations remained around 40%, while sales levels were reported at 35–40%, with another indication showing sales improving to around 45%. Despite some recovery in domestic steel prices, weak sales and limited liquidity continued to restrict scrap procurement.
Rising electricity costs are also forcing mills to consider production cuts. Market participants expect these higher costs to eventually be passed on to customers if mills are unable to absorb the additional burden, potentially putting further pressure on finished steel demand.

Outlook
In the coming days, the outlook is expected to remain stable, supported by firm European and UK shredded scrap offers, elevated replacement costs and higher billet and rebar prices. However, tight liquidity, weak finished steel sales, low mill utilisation and rising electricity costs are likely to limit aggressive procurement. Unless finished steel demand improves materially, scrap prices are expected to remain range-bound, with buyers continuing to negotiate around workable replacement levels.
Leave a Reply