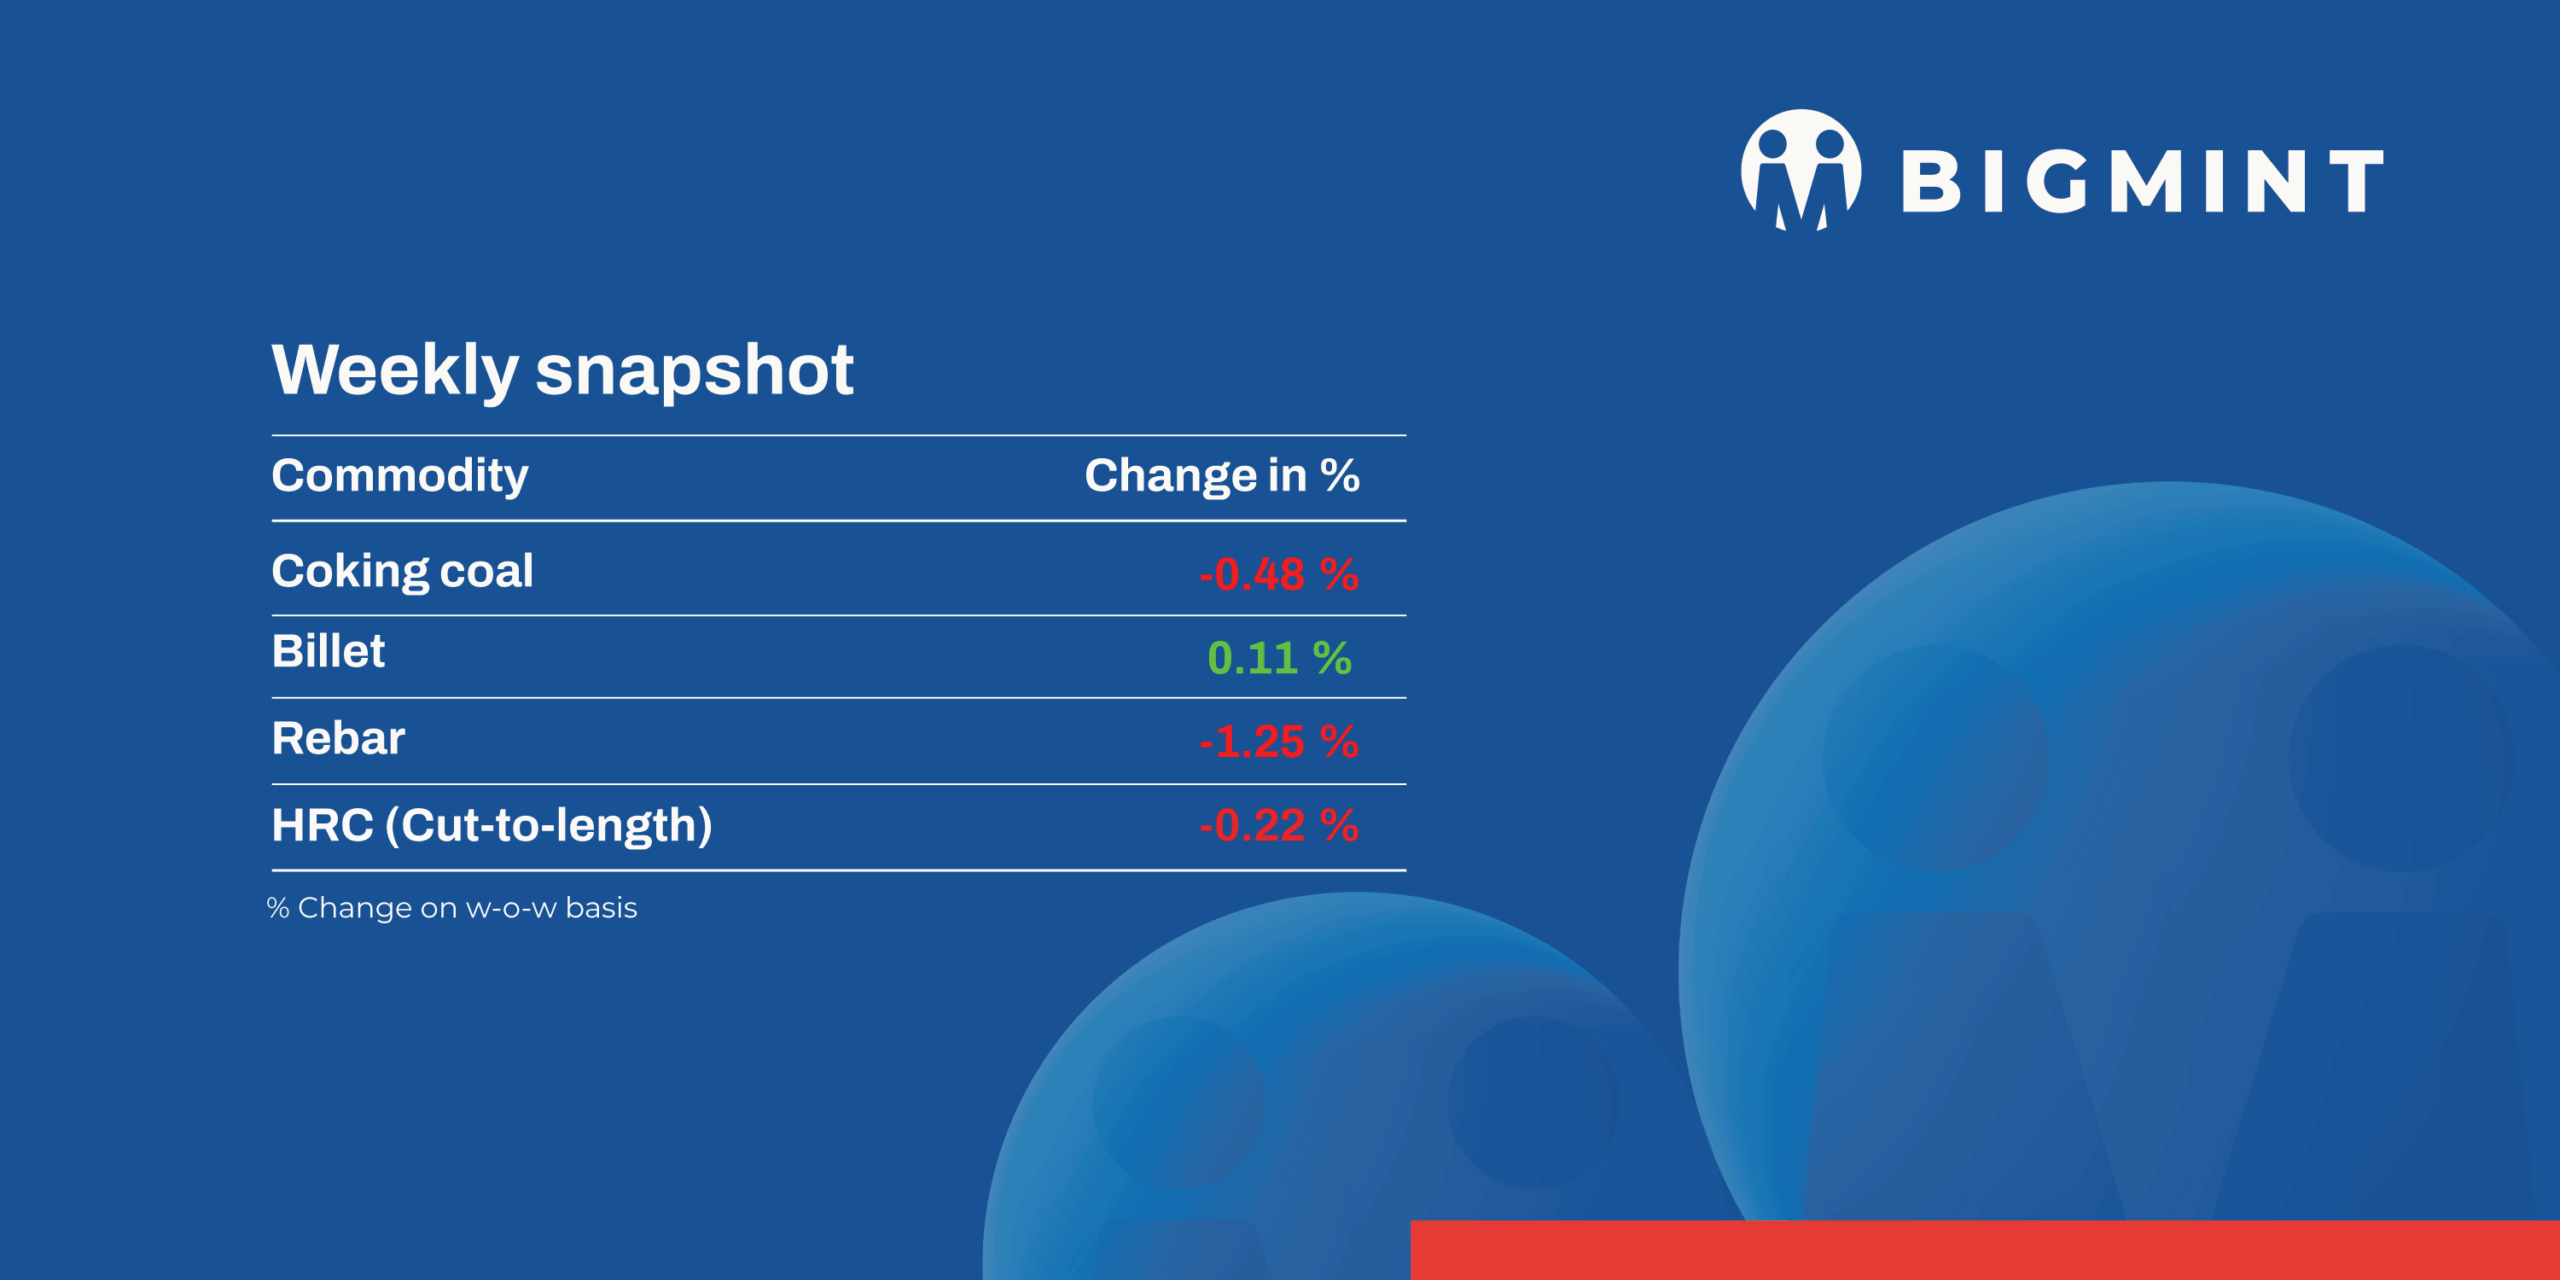
- Iron ore auction bids strengthen, pellet, coking coal and coke prices weaken
- Steel market impacted by festive disruption, liquidity pressures weigh on trades
Indian semi-finished steel markets recorded mixed price movements during the week, with regional supply constraints supporting select products while festive disruptions and weak demand weighed on buying. Raw materials and ferro alloys showed varied trends, while cautious procurement limited price momentum in the finished steel segment.
Iron ore and pellet
- OMC received bids for 1.41 mnt of the 1.44 mnt iron ore fines offered in its 22 October 2026 auction, with only a few low-grade lots remaining unsold. Bid prices rose by INR 50–350/t m-o-m despite a INR 150/t base price cut, supported by supply constraints. OMC also booked the entire 0.731 mnt of calibrated lump ore (CLO) offered, although bid prices declined by INR 100–750/t m-o-m across most mines and grades amid lower base prices for select lots.
- PELLEX declined by INR 100/t w-o-w to INR 11,800/t ($124/t) DAP Raipur on 23 October 2026 amid weak steel demand and pressure on sponge iron margins. Few sellers still under maintenance shut down and expected supply disruptions. Though some deal heard at the lower rate from nearby state.
- BigMint’s iron ore fines export prices remained steady w-o-w at $51.5/t FOB east coast ($66.5/t CFR China) on 22 October. However, trading activity remained subdued amid limited Chinese buying interest, higher freight costs and a persistent gap between buyer and seller price expectations, restricting fresh deals.
- In NMDC’s kumaraswamy’s auction held on 23 October from Karnataka, 82,000 t iron ore lumps (10–40 mm, Fe 57.95–61.87%) got booked at INR 3,704–4,561/t and 228,000 t fines (Fe 57.05–61.58%) booked at INR 2,857–3,862/t. Price excludes royalty, DMF and NMET.
Ferrous scrap
- Imported containerised scrap market remained subdued during the week, with shredded scrap deals heard at $395/t CFR Nhava Sheva before offers stabilised at $400-405/t against bids of $390-395/t. HMS 80:20 offers stood at $360-370/t, while Latin American material was indicated at around $365/t Mundra. Weak finished-steel demand, festive disruptions and high freight costs limited buying interest. A trader also reported selling 1,000 MT of UK-origin steel turnings at $337/t in Chennai.
- Meanwhile, DGFT’s Public Notice No. 35/2026-27, issued on 21 October, revised PSIC requirements for eligible metallic scrap imports from designated countries, including the US, UK, Canada, Australia, New Zealand and the EU. The list of eligible entry ports was expanded from eight to eleven, adding Hazira, Kamarajar and Gangavaram.
Import buying is likely to remain cautious until finished-steel demand improves, although the expanded port options may offer greater logistical flexibility.
Coal
- South African thermal coal prices strengthened in the week ended 23 October, with RB2 at Paradip rising INR 350/t w-o-w to INR 14,550/t and RB3 increasing INR 400/t to INR 12,700/t. At Vizag, RB2 gained INR 350/t to INR 14,500/t, while RB3 rose INR 350/t to INR 12,500/t. Limited fresh offers, higher replacement costs and moderate demand supported prices, despite festive-season trading caution and margin pressure.
- Domestic coal prices weakened amid festive-season sluggishness and cautious spot buying. Ex-Bilaspur 4,500 GCV coal fell INR 200/t w-o-w to INR 6,000/t, while 5,000 GCV coal declined INR 150/t to INR 8,550/t as of 23 October. Washed coal with 38-39% fixed carbon and 5,000 GCV slipped INR 50/t to INR 9,500/t FOR Raipur on 21 October. However, SECL auction bids remained firm, reflecting continued competition for selected grades.
- Metallurgical coke prices declined across domestic markets amid weak steel-sector margins and cautious buying. BF-grade met coke in eastern India fell INR 800/t w-o-w to INR 40,500/t ex-Jajpur, while western India prices decreased INR 400/t to INR 37,000/t ex-Gandhidham. Rajkot foundry-grade coke edged down INR 100/t to INR 39,100/t. Imported Indonesian met coke remained stable at $368/t CFR India, while proposed Chinese coke price hikes offered some support amid subdued mill demand.
- BigMint’s PHCC index declined $1/t w-o-w to $292/t CNF Paradip on 23 October, extending its fall by nearly $15/t since end-September. An Australian miner reportedly sold 75,000 t of Goonyella coking coal to an Indian mill at $267/t FOB for November loading. Tighter coal checks in China, uncertainty around Australian production and Russian port disruptions supported prices, while weak steel margins limited buying interest.
Ferro alloys
- Silico manganese: Silico manganese prices continue to dwell down by INR 1,025/t ($11/t) to INR 81,900-82,300/t ($866-859/t) across key regions, while export offers for 65-16 grades lowered by $6/t to $983/t FOB Vizag/Haldia.
- Weak demand and uncertainty in downstream markets continued to dampen buying interest. Buyers remained cautious about fresh purchases amid uncertainty over near-term price movements, keeping trading activity limited and prompting sellers to face greater resistance to their offers. With demand showing no significant signs of recovery, prices may remain under downward pressure in the near term.
- Ferro manganese: Ferro manganese prices were mostly stable with slight down by INR 100/t ($1/t) w-o-w to INR 89,700/t ($936/t) exw Durgapur, while Raipur stayed unchanged to INR 89,800/t ($938/t). Prices were largely stable supported by sellers’ reluctance to lower offers, limiting downward movement despite subdued buying interest.
- Ferro silicon: Ferro silicon prices edged up by INR 7,00/t ($7/t) w-o-w to INR 96,700/t ($1,010/t) in Guwahati, while Bhutan prices also gained by INR 300/t ($3/t) at 96,000/t ($1,002/t). Prices continue to drew support from limited availability in the Northeast and sustained offer levels from Bhutanese suppliers.
- Ferro chrome: Ferro chrome prices remained unchanged at INR 120,000/t ($1,253/t).With OMCs chrome ore and Vedanta FACORs ferro chrome auction concluded on 22 October, not much of activity was reported in market last week.
- At the OMC’s chrome ore auction, almost entire volume of 95,300 t was booked out of 100,000 t offered. Bid prices increased by 1-7% (INR 100-1,627/t) m-o-m for most grades, while a few grades recorded declines of 0.04-8% (INR 13-1,887/t). The mixed price movement indicates varying buying interest across grades, although the overall booking level remained high.
Semi-finished steel
- Billet
India’s semi-finished steel market witnessed mixed price movements this week, as festive holidays and limited buying activity continued to weigh on overall market sentiment. As per BigMint’s assessment, domestic billet prices increased by INR 50-900/t ($0.5-9/t) w-o-w across major markets. However, Chennai, Jalna and Mumbai recorded declines of INR 100-1,000/t ($1-10/t), amid weak finished steel demand and subdued procurement activity over consecutive weeks.
Buying interest remained limited during the festive period, as buyers opted a cautious approach amid uncertainty over demand recovery. Although power supply disruptions have been resolved, as per market participants, the improvement in production conditions has yet to translate into stronger market sentiment. Overall, persistent weakness in downstream steel demand continued to restrict buying activity. - Sponge iron
Indian sponge iron prices increased by INR 100-1,300/t ($1-13/t) w-o-w across major regions, supported by modest bookings during the week. However, market performance remained uneven, with Chennai and Rourkela recorded price declines of INR 50-800/t ($0.5-8/t) on slower demand. Despite the overall price increases, buying activity remained cautious as downstream steel demand continued to weigh on market confidence. - Indian sponge iron export offers to Nepal and Bangladesh increased by $7-11/t w-o-w, despite weak demand in the neighbouring countries. The rise in offers was due to domestic price volatility, although higher quotations have yet to indicate improvement in export demand. Pellet-based DRI offers to Nepal increased by $8/t w-o-w to $322/t CPT Raxaul, while CDRI/mix sponge iron offers rose by $7/t to $352/t CPT Raxaul. Meanwhile, sponge iron export offers to Bangladesh increased by $11/t to $369/t CPT Benapole.
Finished long steel
- IF-rebar: IF-route rebar prices witnessed a mixed trend across major markets, with regional market dynamics and festival holidays impacting trading activity. Buying remained subdued, as limited improvement in demand kept buyers cautious and procurement largely need-based. Mill inventories were estimated at around 7-10 days, while order booking visibility remained limited to 3-5 days. The near-term outlook remains positive but rangebound, with higher price levels continuing to face resistance from buyers. Market participants are largely maintaining a wait-and-watch approach, restricting purchases to immediate requirements. Price movements will depend on raw material cost trends, regional market sentiment and a sustained improvement in underlying steel demand.
- W-o-w, rebar prices showed mixed trends, fluctuating in the range of INR 100-600/t across regions, according to BigMint’s assessment.
- Trade reference prices of Fe 500-grade rebars manufactured via the IF route (10-25 mm size) were assessed at INR 47,100-47,700/t exw Raipur and INR 50,900-51,500/t exw Jalna.
- Trade reference prices of heavy structural steel for the base size 150 mm channel stood at INR 49,500-50,000/t exw Raipur.
- Trade reference prices of wire rod stood at INR 47,800-48,500/t exw Raipur.
- BF-route rebar: BigMint’s trade-level assessment increased by INR 700/t ($7/t) w-o-w to INR 65,000/t ($685/t) ex-Mumbai on 23 October 2026.
- Regional divergence emerges: In south and central India prices declined by INR 500-1,000/t amid improved supplies, while tight availability supported prices in select western and northern markets.
- Project demand supports prices: Landed project prices remained at INR 65,000-66,000/t, with buyers continuing procurement ahead of the festive period.
Flat steel
- India’s trade-level HRC prices showed mixed trends during the week, declining by INR 200-700/t in some markets while remaining stable in others, despite major steel producers raising HRC prices by INR 500/t mid-week. Comfortable inventories, sluggish demand and a slowdown in buying activity ahead of the festive period kept purchases largely need-based. Liquidity constraints and tight cash flows further weighed on market sentiment, prompting some sellers to offer discounts to liquidate stocks.
- BigMint’s bi-weekly benchmark assessment for Mumbai HRC (IS2062, Grade E250, 2.5–8 mm/CTL) remained unchanged w-o-w at INR 63,700/t exy-Mumbai as of 23 October. Meanwhile, the benchmark assessment for Mumbai CRC (IS513, Grade O, 0.9 mm/CTL) declined by INR 300/t w-o-w to INR 73,100/t from INR 73,400/t on 16 October.
- Import volumes: India’s bulk HRC imports stood at 105,163 t as of 16 October 2026, with a further 101,118 t expected to arrive by the end of October. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.
- Export volumes: India’s bulk HRC exports stood at 45,530 t as of 16 October 2026, with another 65,000 t expected to be shipped by the following week.
- Indian HRC export offers varied w-o-w across key destinations during the week. Offers to the European Union (EU) increased w-o-w, supported by firm domestic realisations. However, no fresh bookings were reported as buyers remained reluctant to accept higher prices amid weak downstream demand and elevated inventories. Meanwhile, offers to the Middle East and Vietnam remained on hold as mills continued to prioritise domestic sales, leaving limited availability for export to both destinations.

Leave a Reply