- Pakistan scrap offers surged as UAE supply disruptions tightened availability
- India’s import demand weakened, while Japan raised scrap buying prices
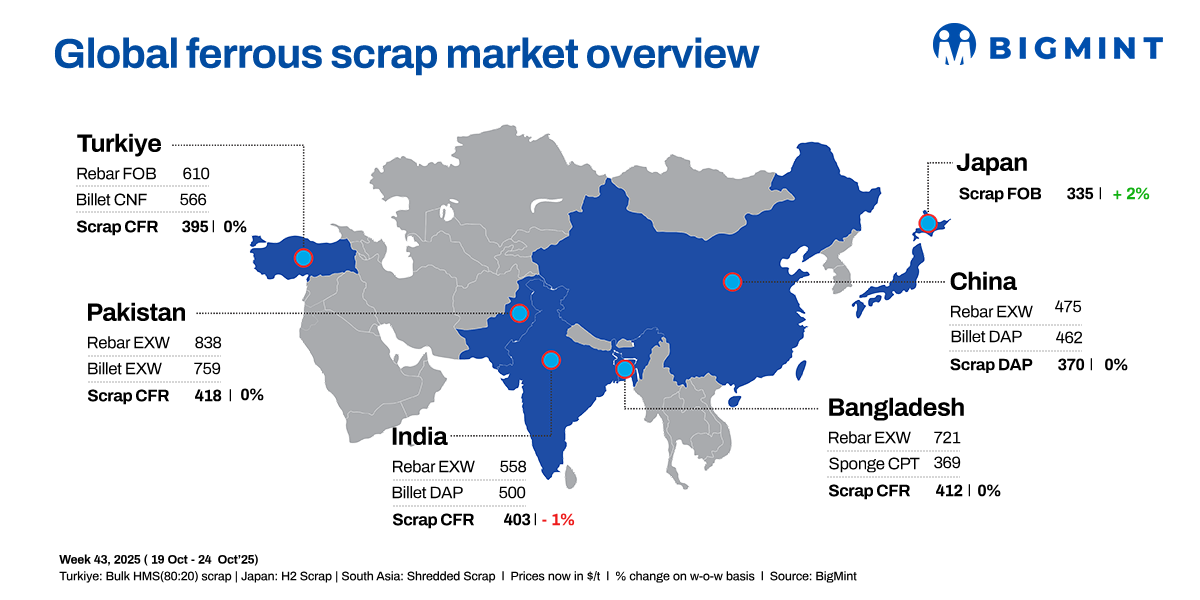
Global ferrous scrap markets remained mixed in the week ended 24 October 2026, with firm prices in Turkiye, the US and Pakistan contrasting with subdued import demand in India and Bangladesh. Supply disruptions supported Pakistani offers, while Japan’s buying prices rose and regulatory changes in India and Thailand influenced regional trade sentiment.
Turkiye: Deep-sea imported scrap market remained largely stable during the week, with HMS 80:20 prices holding at $395/t CFR. Turkish mills’ bids for US- and Baltic-origin material were reported at $395/t CFR, while tradable US-origin values ranged from $392-400/t CFR. EU-origin offers were heard at $390/t initially, with later indications in the $380s/t CFR.
Buying interest improved towards the end of the week as more mills entered the market, and a Baltic-origin cargo was reportedly booked above $395/t CFR, although details remained unconfirmed. However, weak rebar sales, subdued downstream demand and reduced crude steel production continued to limit procurement. Elevated freight costs, limited offers and shipping constraints provided some support to sellers, while mills remained reluctant to accept higher prices.
US: RMDAS ferrous scrap index rose on 21 October versus September, with shredded scrap up $28/t to $447/t, HMS up $27/t to $391/t and prompt industrial composite scrap up $23/t to $495/t, supported by firm mill demand and below-normal inventories.
India: Imported containerised scrap market remained subdued during the week, with shredded scrap deals heard at $395/t CFR Nhava Sheva before offers stabilised at $400-405/t against bids of $390-395/t. HMS 80:20 offers stood at $360-370/t, while Latin American material was indicated at around $365/t Mundra. Weak finished-steel demand, festive disruptions and high freight costs limited buying interest. A trader also reported selling 1,000 MT of UK-origin steel turnings at $337/t in Chennai.
Meanwhile, DGFT’s Public Notice No. 35/2026-27, issued on 21 October, revised PSIC requirements for eligible metallic scrap imports from designated countries, including the US, UK, Canada, Australia, New Zealand and the EU. The list of eligible entry ports was expanded from eight to eleven, adding Hazira, Kamarajar and Gangavaram.
Import buying is likely to remain cautious until finished-steel demand improves, although the expanded port options may offer greater logistical flexibility.
Pakistan: Imported ferrous scrap market strengthened sharply during the week following the disruption of UAE supplies after a Pakistan-bound vessel carrying an estimated 30,000 tonnes of scrap sank. UK/EU-origin shredded scrap offers rose to $420-422/t CFR Qasim from $409-412/t previously, while a UK-origin loaded shredded cargo was reportedly sold at $425/t CFR Qasim.
Tight supply strengthened sellers’ pricing power in Pakistan, with prices expected to remain firm until UAE shipments resume. A Karachi-based steelmaker anticipates a further $5-10/t rise amid stronger demand for UK and European scrap.
Bangladesh: Imported ferrous scrap market remained firm, although sluggish finished-steel demand and elevated inventories limited buying interest. Australian-origin shredded scrap was offered at $415/t CFR Chattogram, while UK-origin shredded stood at $408-410/t and HMS at $370-375/t. Singapore-origin PNS offers were quoted at $430-435/t amid rising freight rates. Japanese H2 was offered at $405-410/t, with freight reaching $90-100/t for 15,000-20,000 t cargoes. European shredded scrap stood at $410/t, HMS 80:20 at $378/t, Malaysian bundle mix at $345-350/t and busheling at $415/t.
Japan: Ferrous scrap market remained bullish, with FOB Tokyo Bay prices rising JPY 300/t ($2/t) to JPY 52,500/t ($335/t). Tokyo Steel also increased buying prices at its Kyushu plant by JPY 1,000/t ($6/t) to JPY 52,500/t ($332/t), effective 22 October 2026, while rates at its other seven locations remained unchanged at JPY 51,000-52,500/t ($323-332/t).
China: China produced around 651 mnt of crude steel in 8MCY26, with BF-BOF accounting for 89% and electric furnaces 11%. The limited EAF share continues to restrict scrap consumption growth through electric steelmaking, despite China being the world’s largest steel scrap consumer.
Thailand: Thailand has tightened scrap container inspections amid a crackdown on illegal e-waste imports. On 21 October, the Customs Department proposed a possible ban on ferrous, copper, aluminium and rubber scrap imports, with a six-to-12-month transition period under consideration. Uncertainty over implementation has raised concerns about port delays and higher logistics costs.
UAE: UAE ferrous scrap market remained under pressure amid subdued steel demand, sufficient mill inventories and increased material availability following a vessel incident. Domestic HMS processed prices delivered to Abu Dhabi fell below AED 1,000/t, while HMS buying was reported at AED 1,000-1,020/t and shredded scrap at AED 1,120-1,130/t. BigMint assessed processed HMS 80:20 at AED 1,003/t ($273/t), down AED 23/t ($6/t) week-on-week, as oversupply and cautious buying weighed on prices.
Leave a Reply