- Tighter scrap availability supports supplier offers amid cautious buying
- Weak finished steel demand, liquidity constraints weigh on Mandi scrap prices
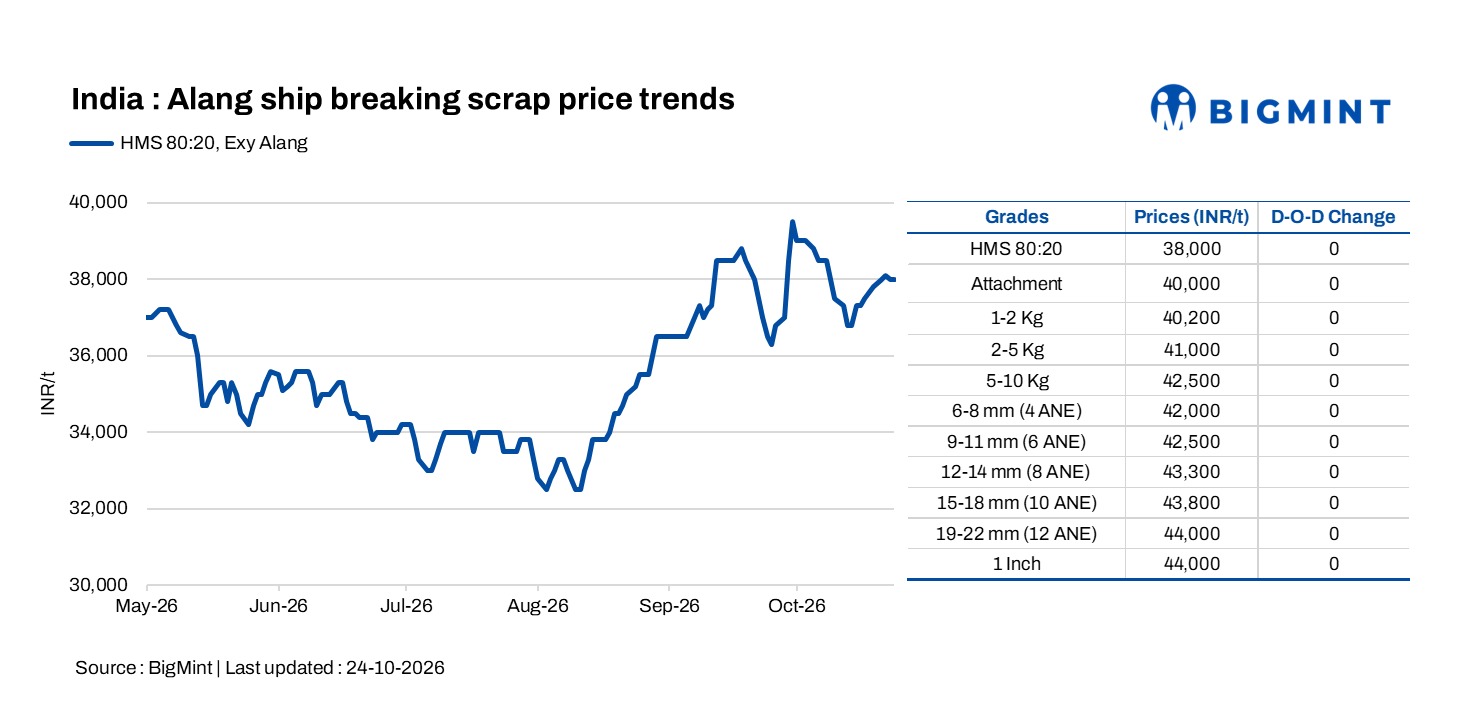
Alang’s ship-breaking melting scrap prices (HMS 80:20) remained stable day-on-day (d-o-d) at INR 38,000/tonne (t) ($400/t) ex-yard on 24 October 2026, but increased by INR 800/t week-on-week (w-o-w). The weekly gain reflects tighter scrap availability and post-festive season demand, which encouraged suppliers to maintain firmer offers despite cautious buying.
Improved steel prices in regional markets provided additional support to scrap values over the week. However, buying interest remained closely linked to finished steel demand, with consumers assessing near-term requirements before committing to larger volumes. The lack of consistent downstream offtake continued to limit the scope for a stronger recovery.
Market direction will depend on whether firmer regional steel prices translate into sustained demand from rerollers and other scrap consumers. If finished steel sales remain subdued, buyers are likely to continue need-based procurement, keeping further price gains in check.
Gujarat market update

In Gujarat, billet prices at Bhavnagar declined by INR 200/t d-o-d to INR 46,600/t DAP on 23 October but remained INR 900/t higher w-o-w. Rebar prices in Ahmedabad also fell by INR 200/t d-o-d to INR 52,800/t ex-works, while recording a w-o-w increase of INR 250/t.
The weekly gains indicate that regional steel prices have retained some support, although the latest daily declines point to limited near-term momentum. Market participants remain cautious about extending procurement as demand for finished steel continues to influence buying decisions and price negotiations.
Billet producers are likely to remain sensitive to input costs and conversion margins, while rebar manufacturers will monitor sales volumes before making further price adjustments. The divergence between weekly gains and daily declines suggests that the market is stabilising unevenly rather than entering a sustained upward trend.
Mandi market update
In Mandi Gobindgarh, billet prices declined by INR 300/t d-o-d to INR 46,900/t DAP on 23 October. Rebar prices remained stable at INR 52,300/t ex-works, while HMS 80:20 prices fell by INR 500/t to INR 37,100/t DAP.
A steady inflow of scrap, coupled with restrained buying by major mills, kept the market under pressure. Sluggish demand in the finished steel segment further strained liquidity across the region’s secondary steel industry, limiting mills’ ability to absorb additional raw material at prevailing prices.
Market participants remained cautious, with mills favouring limited, need-based procurement amid uncertainty over finished steel offtake. Suppliers faced with adequate material availability and slower conversions showed greater flexibility in pricing to clear inventories. The decline in HMS 80:20 prices reflects this imbalance between supply and demand, while the stability in rebar indicates that finished steel prices have yet to adjust fully to the weakness in scrap and billet markets.
Overall, sentiment in Mandi remained weak to neutral, with buyers adopting a wait-and-watch approach. Prices are likely to remain under pressure or trade within a narrow range unless finished steel demand improves, scrap arrivals ease, or mills increase procurement to replenish inventories.
Leave a Reply