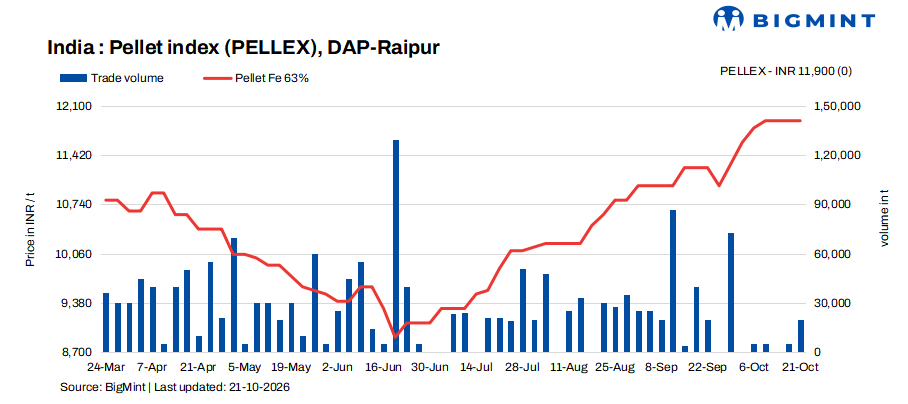
- Firm seller offers and post-festive restocking support pellet prices
- Weaker steel prices and competitive offers from outside state limit upside
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, remained unchanged at INR 11,900/t ($126/t) DAP Raipur on 21 October 2026 compared with the previous assessment on 16 October.
Prices continued to draw support from firm seller offers, limited spot availability. However, trading activity remained subdued, with only a few deals recorded as buyers resisted prevailing price levels amid softening sponge iron and billet prices.
Market participants reported that pellet producers have largely maintained their offers despite weakening downstream steel market indicators. Several manufacturers remain occupied with pending dispatches against previously committed orders, while maintenance shutdowns at major plants have further limited spot availability. These factors have reduced selling pressure and restricted the scope for an immediate price correction.
However, buying interest remains selective. Although some transactions are being concluded at discounts of around INR 300-400/t to prevailing offers, buyers continue to resist higher price levels. Competitive landed offers from neighbouring markets, particularly Odisha, have also increased pressure on Raipur-based suppliers, with some consumers considering sourcing material from outside the region rather than waiting for local offers to soften.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- Two (2) deals were recorded in this publishing window and One (1) was taken for calculation. Thus, the T1 trade category was accorded a weightage of 50%.
- Twelve (12) firm offers, bids, and indicative prices were heard, of which eleven (11) were taken for price calculation and given the balance 50% weightage.
Price movements and offers
Major pellet manufacturers in Chhattisgarh largely maintained their offers for Fe 62.5-63% (± 0.5%) grade pellets, reflecting limited spot availability and expectations of improved demand following the festive period. The suspension of regular procurement during Durga Puja and Dussehra was followed by a gradual resumption of buying, providing some support to market sentiment.
Nevertheless, the improvement in demand has yet to translate into a significant increase in trading volumes. Market participants indicated that deals are being concluded below prevailing offers, highlighting the widening gap between sellers’ price expectations and buyers’ purchasing limits. With downstream steel prices showing weakness, consumers remain cautious about committing to large volumes at current pellet prices.
Competitive landed offers from neighbouring markets have added to this resistance. Buyers are increasingly evaluating alternative sourcing options, limiting the ability of Raipur-based suppliers to push prices higher. While sellers have largely refrained from revising their offers downward, the persistence of discounted transactions suggests that underlying demand remains insufficient to support a broad-based price increase.
Market scenario
The Raipur pellet market remains caught between firm seller resistance and cautious procurement. Several major producers are either operating under maintenance shutdowns or prioritising the execution of existing orders, limiting fresh spot availability. Consequently, sellers have little immediate incentive to reduce their offers aggressively, particularly while pending dispatches continue to absorb available material.
However, this supply-side support is yet to be matched by a sustained recovery in downstream demand. Buyers remain wary of prevailing pellet prices as sponge iron and billet markets have softened, while competitive offers from outside Chhattisgarh provide alternatives to local procurement.
Market participants are also closely tracking Odisha Mining Corporation’s (OMC) iron ore e-auction scheduled for 22 October 2026. OMC has reduced its base prices by around INR 150/t for fines and INR 50–450/t for calibrated lump ore (CLO), with 1.43 million tonnes (mnt) of fines and 0.731 mnt of CLO on offer. The lower base prices have reinforced expectations of raw material price adjustments and prompted buyers to reassess their near-term procurement strategies.
Market participants expect a possible correction of INR 300-400/t in Raipur pellet prices if lower auction prices translate into cheaper raw material procurement and competitive offers from neighbouring regions persist. However, the extent of any decline will depend on the auction outcome, actual transaction levels and the pace at which major producers resume regular market sales.

Key market drivers
- Sponge iron prices fall by INR 150/t ($2/t) w-o-w: BigMint’s price assessment for P-DRI in Raipur softened by INR 150/t to INR 28,000/t ($296/t) ex-works on 21 October compared with 14 October. Buying remained largely need-based, with limited bulk procurement despite enquiries from consumers. While bookings concluded in the previous session supported seller confidence, buyers remained reluctant to commit to larger volumes at prevailing prices. The weakness in sponge iron prices has limited downstream support for pellet offers.
- Billet prices down by INR 100/t ($14/t) w-o-w: BigMint’s billet index in Raipur declined by INR 100/t ($1/t) to INR 44,400/t ($470/t) ex-works on 21 October compared with 14 October. Trading resumed after a three-day holiday period, with procurement largely restricted to immediate requirements. The absence of strong support from finished steel demand continues to weigh on market sentiment, while price volatility is likely to keep steelmakers cautious about raw material purchases.
Outlook
BigMint expects Raipur pellet prices to remain largely stable in the near term, with a downward bias if buying interest remains subdued. Firm seller offers, pending order execution and maintenance shutdowns at major plants are likely to limit immediate price declines. However, softening sponge iron and billet prices, competitive landed offers from neighbouring markets and expectations of lower raw material costs could intensify buyer resistance.
The outcome of OMC’s 22 October auction will be a key near-term indicator. While limited spot availability may prevent a sharp correction, sustained weakness in downstream demand could prompt sellers to offer larger discounts to secure fresh bookings.
Leave a Reply