- Sep price recovery, October hikes to bolster Q3 realisations
- Capacity utilisation improves to 71% against 66% in Q2FY’26
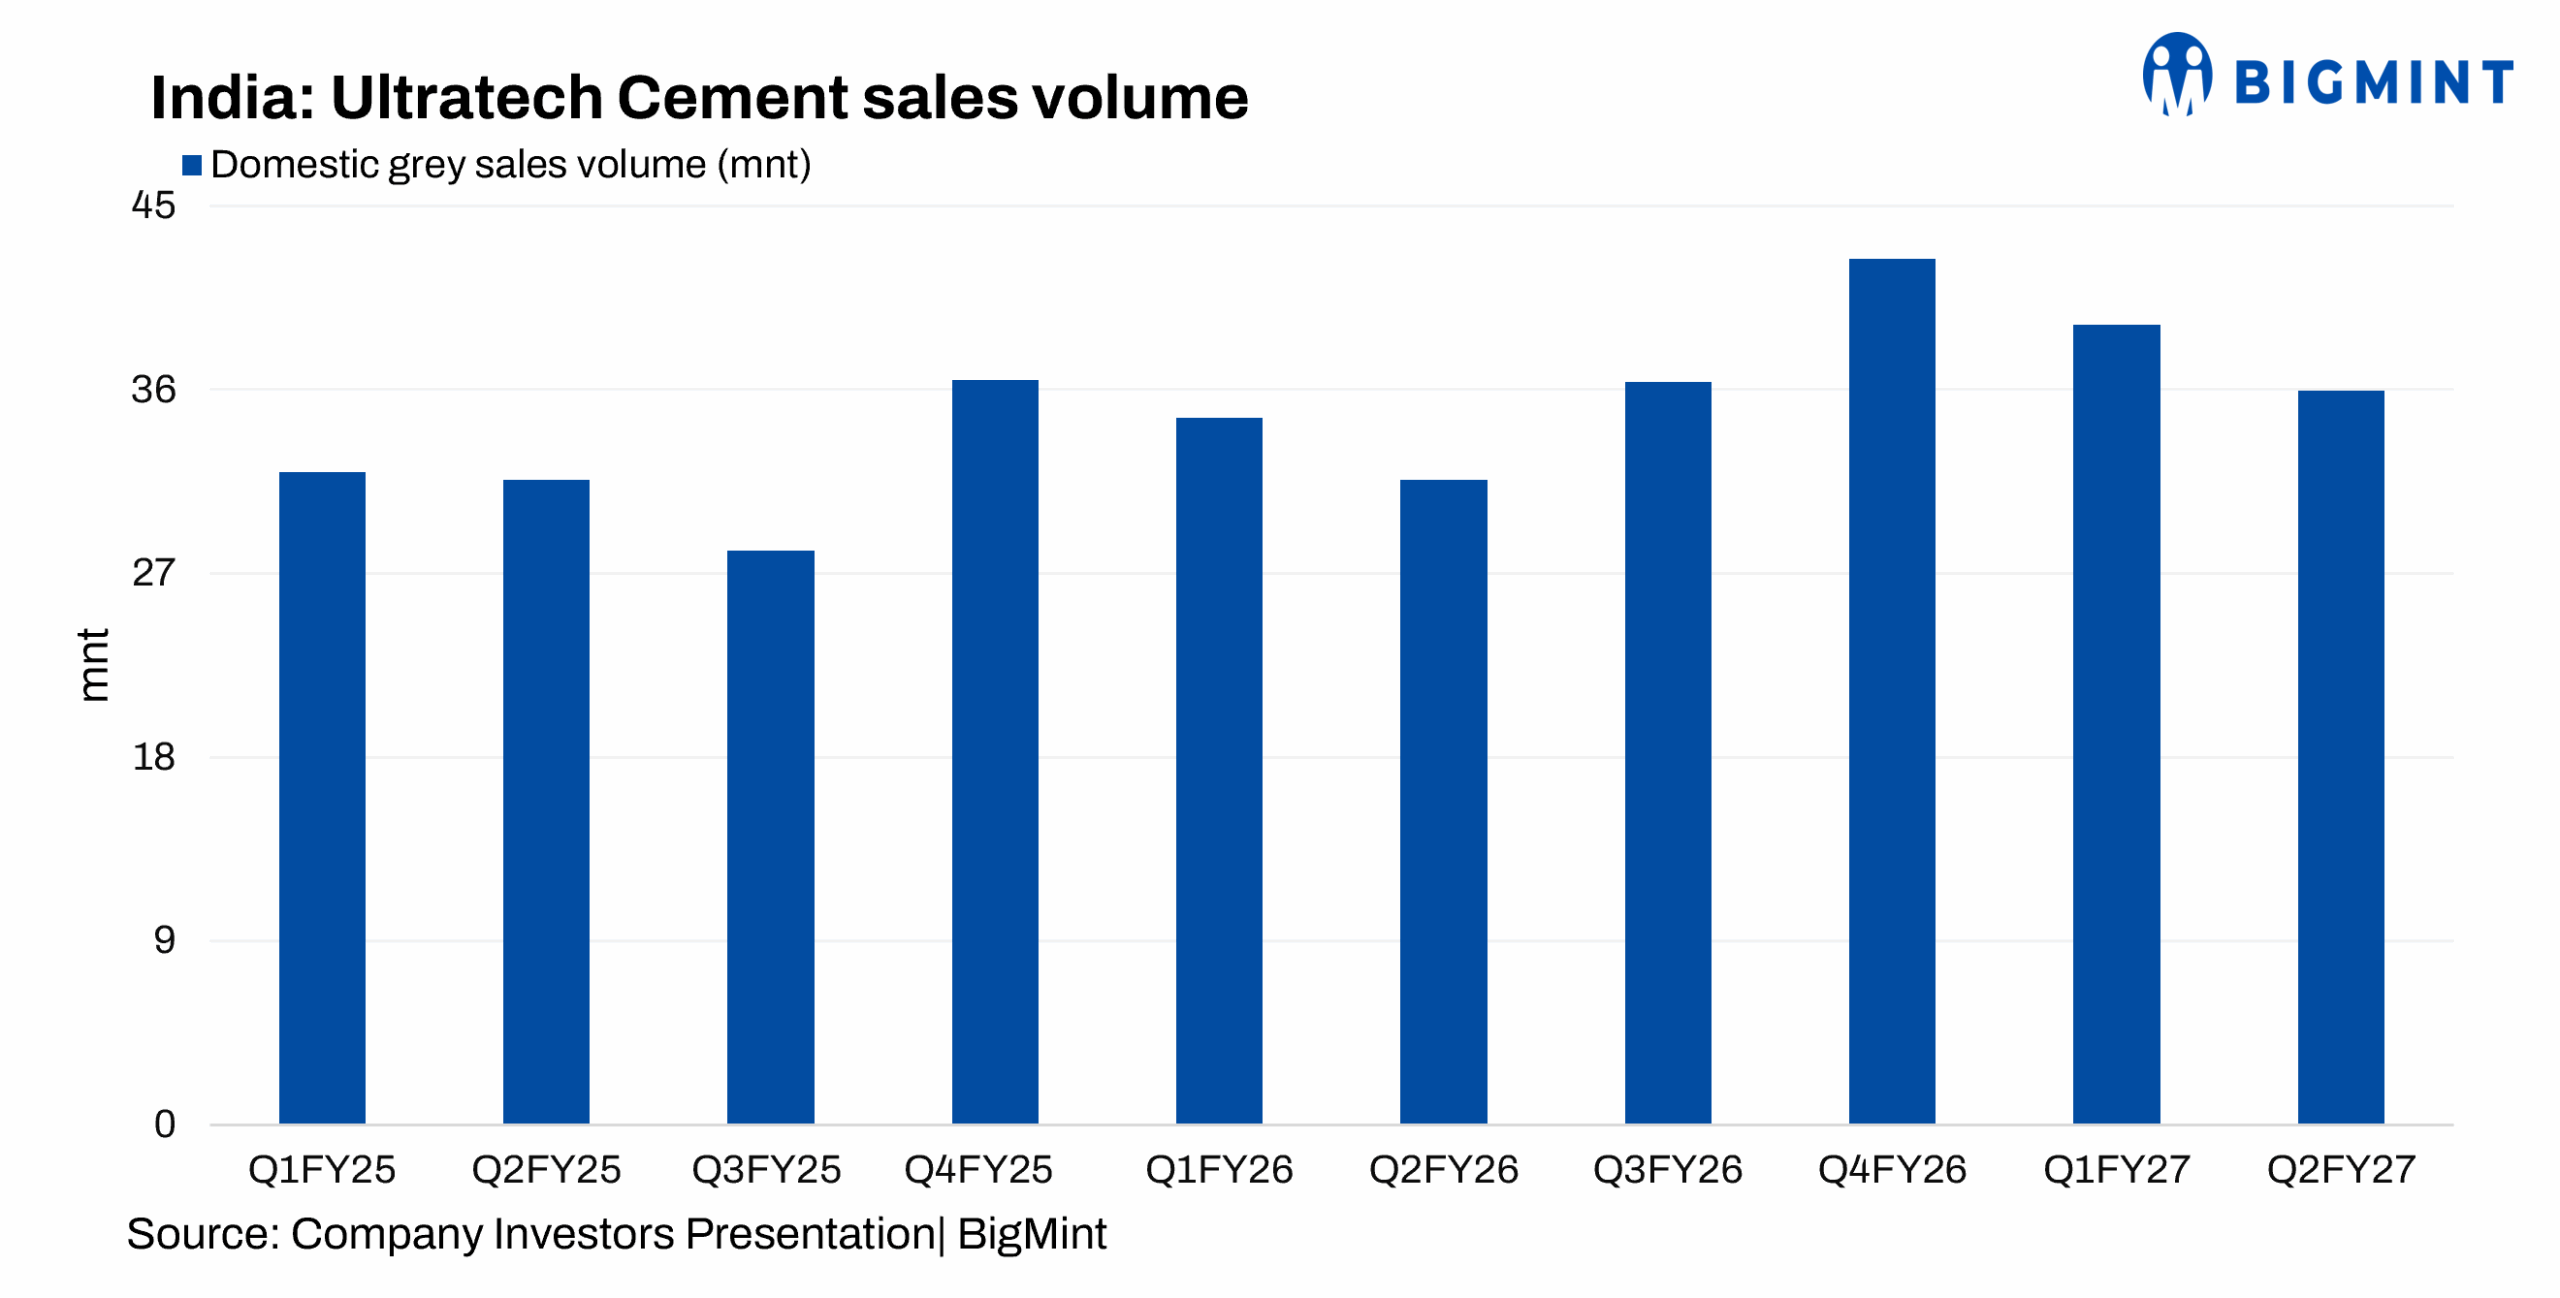
UltraTech Cement reported strong operational performance in Q2FY’27, with a 14% y-o-y increase in sales to 35.94 million tonnes (mnt), supported by resilient retail demand, reduced monsoon-related disruptions, and improved capacity utilisation. The increase in sales volumes strengthened operating leverage, while rising fuel costs continued to exert pressure on margins. The company expects recent cement price hikes to improve realisations in Q3FY’27, subject to sustained market acceptance.
Pricing, demand trends
Average cement trade prices in major markets remained broadly stable q-o-q in Q2FY’27, declining by around 1.5%, primarily due to weaker prices in August. Prices recovered during the second half of September, increasing by INR 7-10/bag m-o-m.
Trade prices ended September around 3% above the Q1 average, followed by further increases in October. The company expects the full benefit of these hikes to reflect in Q3FY’27 earnings, depending on price retention and market acceptance.
The company also reported a premium cement share of 37% and blended cement share of 67.3% in Q2FY27, supported by premiumisation, strong regional demand, improved weather conditions, and expanding UltraTech Building Solutions (UBS) distribution, while product-mix optimisation and energy efficiencies helped mitigate input-cost pressures. Meanwhile, capacity utilisation improved to 71% compared with 66% in Q2FY’26.
EBITDA/t declines
The company’s operating EBITDA rose 20.3% y-o-y to INR 3,721 crore in Q2FY’27, compared with INR 3,094 crore a year earlier. However, EBITDA per tonne declined 19.8% q-o-q to INR 974 from INR 1,214 in Q1FY’27, reflecting seasonal softness and elevated input costs. Despite strong volume growth and improved capacity utilisation, the company expects sustaining price hikes and controlling fuel expenses to be critical to restoring per-tonne profitability.
The company aims to increase EBITDA per tonne y-o-y over the next two quarters, with price hikes offseting elevated fuel and logistics costs. By March 2028, UltraTech is targeting an EBITDA per tonne of INR 1,400/t.
Regional demand diverges
Southern markets recorded the strongest combined momentum in pricing, sales volumes and capacity utilisation, with volumes increasing 15-20% y-o-y. Northern markets registered growth exceeding 20%, while western and central markets expanded by around 10% each. Eastern markets recorded around 5% growth, constrained by heavy rainfall and construction disruptions. Price recovery gained momentum across the eastern corridor in early October, while Maharashtra markets strengthened in September, particularly Mumbai, where prices increased by 3-4%.
Fuel costs pressure margins
Fuel and raw material costs increased by around 3% q-o-q, with fuel costs rising from INR 45/bag to INR 51.50/bag amid elevated petcoke prices and constrained domestic coal availability. Despite these pressures, fixed costs per tonne declined 6% y-o-y, as absolute fixed costs increased only 4%, below the 13.8% growth in sales volumes.
Improved operating leverage helped support profitability, although further energy-cost increases could constrain margin expansion if cement price realisations do not keep pace. Keeping this in mind, the company successfully installed 116 MW of renewable power and a 10 MW waste heat recovery system (WHRS), achieving a 47% green power mix and a 7.2% thermal substitution rate.
Expansion outlook strengthens
The company expects domestic cement demand to strengthen over the next two to three years, driven by individual home builders, urban housing, infrastructure development and private-sector capital expenditure. The company highlighted a growing pipeline of infrastructure and industrial projects, including roads, power plants, industrial parks and data centres.
In line with its target of 240 mnt/year by FY’28, the company commissioned 4.6 mnt/year of capacity in the month of September, which includes the 3.6 mnt greenfield capacity at Petnikota in Andhra and 1 mnt of debottlenecking at three other units, taking its domestic cement capacity to 204.7 mnt/year. The company also indicated that an organic expansion plan beyond its existing 240 mnt/year capacity is under preparation, reflecting its long-term growth ambitions and expectations of sustained domestic consumption.
Outlook
UltraTech’s Q3 performance is expected to benefit from improved cement realisations, resilient demand, and higher capacity utilisation. However, sustained margin recovery will depend on the durability of price increases, fuel-cost movements and regional demand conditions. Continued infrastructure spending, housing activity and planned capacity expansion are expected to support the company’s medium-term growth outlook.
Leave a Reply