- Domestic sales offer higher realisations, exceeding exports by INR 2,500/t
- Chinese imported iron ore prices dip w-o-w, weighing on export sentiment
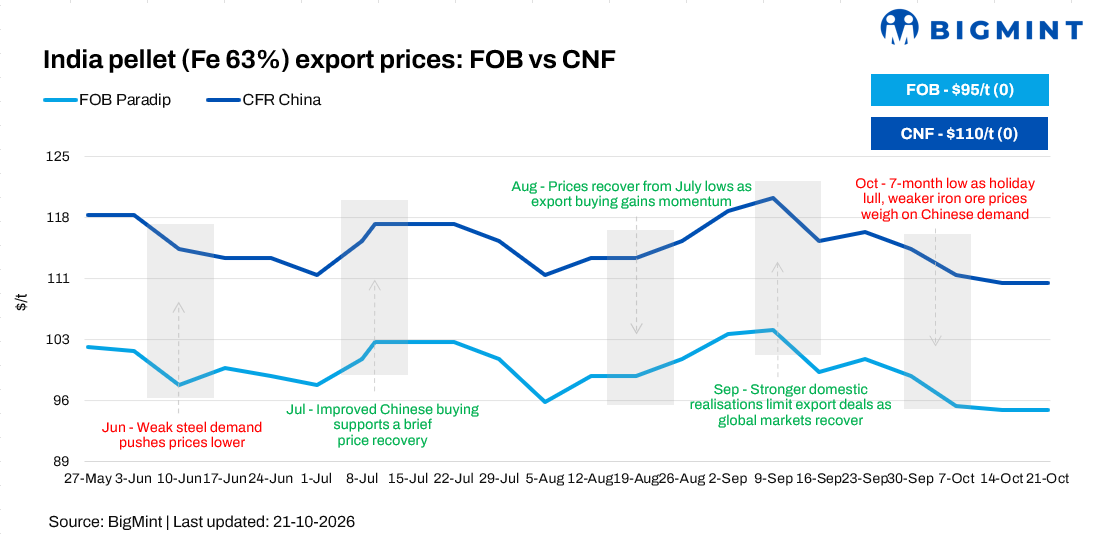
BigMint’s India pellet export index remained unchanged w-o-w at $95/tonne (t) FOB East Coast in the week ended 21 October 2026, equivalent to around $110/t CFR China. Export market activity remained subdued, with no firm offers or buying interest reported amid Dussehra holidays.
Market participants said trading activity was largely limited to indicative price discussions, with no significant transactions reported during the week. Buyers and exporters remained divided on price expectations, while the holiday-related slowdown further restricted fresh enquiries and negotiations.
A trader told BigMint, “There was no buying interest and no firm offers during the week due to Dussehra holidays. The market remained largely inactive.”
Rationale
- Zero (0) deals from India’s east coast were recorded for T1 trade during the publishing window; therefore, this category was assigned a 0% weightage in today’s price calculation.
- Eight (8) bids, offers, and indicative prices were heard, all of which were considered for the calculation of the index and given the balance 100% weightage.
Domestic market remains more attractive
Indian pellet producers continued to find the domestic market more attractive than exports, limiting their willingness to offer material to overseas buyers at prevailing prices. With domestic realisations offering comparatively better returns, exporters remained cautious about pursuing international sales.
A major pellet exporter said, “Domestic markets are more attractive to Indian producers at present, leaving limited incentive to sell in the export market at current price levels.”
Export realisations for Fe 63% pellets remained largely stable w-o-w at INR 7,000/t ($73.4/t) ex-works, with a slight recovery. Meanwhile, domestic realisations for Fe 62.5% pellets held steady at INR 9,600/t ($101/t) ex-works, supported by relatively stronger domestic market economics.
Consequently, the gap between domestic and export realisations widened marginally by INR 52/t ($0.6/t) w-o-w to INR 2,583/t ($27.4/t). The wider spread continued to favour domestic sales, discouraging exports amid weak overseas demand and limited buying interest.
Meanwhile, iron ore pellet dispatches surged to 189,000 t during 10-16 October 2026, compared with 48,000 t in the previous week. The entire volume was shipped through Kandla port, according to BigMint’s weekly vessel line-up data.

Weak global market caps export prospects
The export market continued to face pressure from softening seaborne iron ore prices and weak steel market conditions. Limited buying interest from overseas consumers, coupled with uncertainty over near-term demand, kept market participants cautious.
“Trading activity remained subdued, with limited firm enquiries and deals as exporters and buyers remained apart on price expectations”, another trader highlighted.
The benchmark iron ore fines (Fe 61%) index edged down by $1/dry metric tonne (dmt) w-o-w to $90/dmt CFR China on 20 October 2026, from $91/dmt on 13 October. Market sentiment remained subdued amid weak steel demand, compressed mill margins and limited spot buying by Chinese steelmakers. Buyers continued to adopt a cautious, wait-and-watch approach, restricting fresh procurement and limiting upward price momentum.
Persistent concerns over downstream steel consumption and elevated port inventories further weighed on market confidence. While fluctuations in seaborne supply and changes in mill procurement could offer intermittent support, a sustained recovery in spot prices will depend on improved steel demand and stronger buying interest from Chinese mills.
Meanwhile, iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract rose by RMB 7/t ($1.1/t) w-o-w to RMB 681/t ($102/t) on 21 October 2026, from RMB 674/t ($100.9/t) a week earlier. The modest gain in futures indicated some improvement in market sentiment, although persistent concerns over steel demand and profitability continued to cap the upside. The divergence between softer spot prices and firmer futures reflected cautious market positioning, with participants awaiting clearer signals on China’s steel demand and raw material procurement trends.
Outlook
India’s pellet export market is likely to remain subdued in the near term unless fresh overseas enquiries translate into firm bookings. The resumption of normal market activity after the holiday period, movements in seaborne iron ore prices and the relative attractiveness of domestic sales will remain key factors influencing export offers and trading sentiment.
Leave a Reply