- Imported coal demand weak as buyers favour need-based buying
- Domestic coal prices decline, pressuring washed coal, auction prices
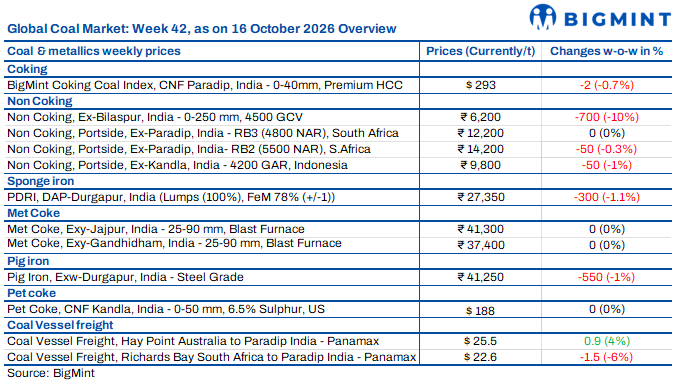
Coal markets remained mixed during the week ended 16 October 2026, with subdued industrial demand and cautious procurement weighing on prices across several segments. Imported coal availability improved, while domestic supplies and rising port inventories limited upside potential. However, firm international offers, higher freight costs and tight power-plant stocks provided support. Washed coal and metallurgical coke faced pressure from weaker downstream demand, while petcoke prices rose on higher replacement costs. Post-Diwali restocking remained a key factor for near-term market direction.
Indonesian coal prices ease as demand stays weak
Indian portside prices of Indonesian thermal coal declined marginally in the week ended 16 October, as weak industrial demand and ample availability weighed on buying. Prices of 5,000 GAR coal fell INR 100/t to INR 11,700/t at Kandla and INR 11,600/t at Vizag. 4,200 GAR prices dropped INR 50/t to INR 9,800/t and INR 9,700/t, respectively, while 3,400 GAR coal at Navlakhi declined INR 100/t to INR 7,750/t. Port inventories rose 1.3% w-o-w to 18.68 mnt in Week 41, while power plant stocks fell 1% to 20.44 mnt, covering around seven days of consumption. Firm Indonesian FOB benchmarks limited downside, while post-Diwali restocking could support demand.
South African coal prices ease amid weak demand
South African thermal coal prices at Indian ports softened on 16 October, as weak spot demand and improved domestic coal availability limited buying interest. Ex-Paradip RB2 (5,500 NAR) fell INR 50/t w-o-w to INR 14,200/t, while RB3 (4,800 NAR) remained stable at INR 12,200/t. At Vizag, RB2 declined INR 100/t to INR 14,150/t, while RB3 dropped INR 100/t to INR 12,150/t. Mangalore offers stood at INR 14,300-14,400/t for RB2 and around INR 12,200/t for RB3. Firm export offers and freight costs supported replacement prices, but rising port inventories to 18.68 mnt and cautious sponge iron buying limited recovery prospects.
Domestic coal prices continue to weaken
Ex-Bilaspur 4,500 GCV coal prices fell INR 700/t w-o-w to INR 6,200/t as of 16 October, while 5,000 GCV coal declined INR 300/t to INR 8,700/t. The correction followed high-premium SECL auction purchases, which left some buyers reluctant to lift booked quantities as spot prices weakened. Some participants reportedly defaulted on earnest money deposits (EMDs), as auction purchase costs became less competitive against prevailing market rates.
Washed coal prices fall on weak demand
BigMint assessed 38-39% FC (5,000 GCV) washed coal FOR Raipur at INR 9,550/t on 14 October, down INR 550/t w-o-w. Lower domestic coal prices and subdued sponge iron demand weighed on buying interest. Weak downstream steel demand further limited procurement, while buyers remained cautious about purchasing at earlier price levels.
Indian met coke prices hold steady amid weak demand
Indian BF-grade met coke prices remained stable w-o-w, with eastern India at INR 41,300/t ex-Jajpur and western India at INR 37,400/t ex-Gandhidham. Foundry-grade prices in Rajkot also held at INR 39,200/t. Selective buying and subdued steel demand limited trading activity, despite deals at INR 43,750/t and INR 44,000/t exw for specific grades. Imported Indonesian met coke prices fell $2/t to $368/t CFR India, while Australian PHCC declined $2/t to $269/t FOB. China’s cumulative coke price cuts reached RMB 200-220/t ($30-33/t) since 1 October. Durgapur pig iron prices also dropped INR 550/t to INR 41,300/t, keeping the outlook cautious.
US thermal coal prices ease as supplies improve
Indian NAPP retail prices eased to INR 18,200-18,800/t ex-port by 13-16 October, down from INR 19,000-19,500/t in early October. Kandla indications stood at around INR 18,500/t on 16 October as fresh cargoes improved availability. Tracked Kandla and Tuna inventories rose to 107,177 t on 12 October from 99,533 t a week earlier, while weekly lifting increased to 42,787 t. Cement producers continued evaluating NAPP, ILB and alternative fuels, although high replacement costs supported sellers. The October-November at-port and scheduled cargo list totalled 2.475 mnt, comprising 2.321 mnt of NAPP and 0.155 mnt of ILB. Tight forward availability limited the scope for sustained price declines.
US petcoke prices rise as freight costs increase
US Gulf Coast 6.5% sulphur petcoke prices rose $5/t w-o-w to $115/t FOB on 14 October, marking a $41/t increase over four months. Higher coal prices and freight costs pushed Indian import offers to $185-190/t CFR by 16 October. Freight to India reached $57.75/t, around $20/t higher y-o-y. Cement producers increasingly used existing stocks, domestic coal and alternative fuels to manage costs. October petcoke import visibility reached 965,519 t, including 428,247 t recorded through 11 October and 537,272 t outstanding through 12 October. However, higher replacement costs and cargo commitments limited the scope for sustained price declines despite improving availability.
Indian petcoke prices rise across major refineries
India’s domestic petcoke prices increased in October, with IOCL raising prices by INR 2,490-2,500/t, Nayara Energy by INR 2,180/t, MRPL by INR 2,000/t and BPCL by INR 1,500/t. IOCL road prices reached INR 19,700/t at Koyali, INR 20,970/t at Panipat, INR 18,720/t at Paradip and INR 18,840/t at Haldia. Nayara’s price rose to INR 20,960/t, up 11.6% m-o-m and 41% y-o-y. MRPL’s rake and road prices increased to INR 17,370/t and INR 19,300/t, respectively. BPCL prices reached INR 19,500/t at Bina and Kochi. Higher international replacement costs, freight and marine insurance expenses supported the increases.
Coal freight rates show mixed trends
India-bound coal freight markets remained mixed in the week ended 16 October. Australian Panamax freight to Paradip rose $0.9/t w-o-w to $25.5/t, supported by Pacific demand. South African freight to Paradip fell $1.5/t to $22.6/t, while East and South Kalimantan Supramax rates to Navlakhi declined $0.9/t and $1/t to $23.1/t and $22/t, respectively. Limited bookings and high freight offers weighed on Indonesian routes. The Baltic Dry Index fell 14.4% to 2,545, while Singapore VLSFO rose 1.5% to $910/t, increasing vessel operating costs. Freight sentiment remained route-specific, with bunker costs supporting offers but cautious chartering limiting gains.
Leave a Reply