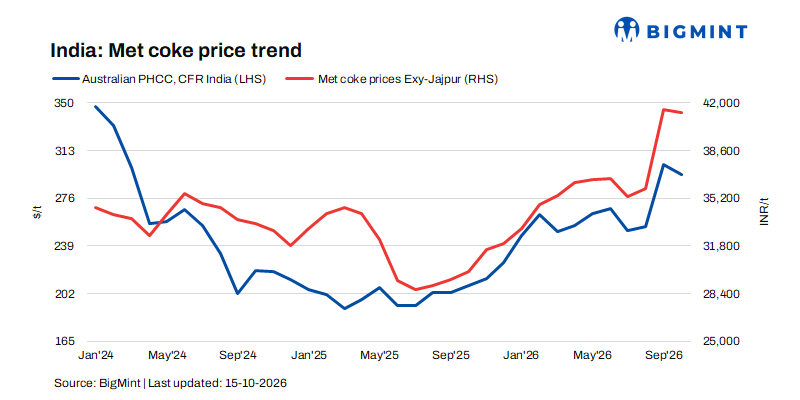
- Indian met coke prices stable amid selective buying
- Chinese coke price cuts, softer global coal prices keep outlook bearish
India’s metallurgical coke (met coke) prices remained stable w-o-w in the assessment week ended 15 October, as selective buying and subdued downstream steel market conditions limited price movement. While transactions continued at prevailing levels, weakness in international coking coal and Chinese coke markets, coupled with declining pig iron prices, kept market sentiment cautious.
Domestic met coke prices remain rangebound
Blast furnace (BF)-grade met coke prices in eastern India remained unchanged w-o-w at INR 41,300/t ex-Jajpur, while western India prices held at INR 37,400/t ex-Gandhidham. Foundry-grade met coke prices in Rajkot also remained stable at INR 39,200/t ex-Rajkot. Limited trading activity and cautious procurement by buyers amid subdued steel market conditions prevented any significant price movement.
Market transactions remained selective, with a 12,000-t deal reported at INR 43,750/t ex-works (exw) in eastern India. Separately, a trader reportedly purchased 2,000 t of BF-grade met coke at INR 44,000/t exw, particularly for material with 65 CSR. These transactions indicate continued demand for specific quality grades, although broader buying interest remained restrained.
Imported coke and Australian coking coal prices edge lower
Imported Indonesian met coke prices in India declined marginally by $2/t w-o-w to $368/t CFR India, reflecting a softer international market. Meanwhile, Australian premium hard coking coal (PHCC) FOB prices eased by around $2/t w-o-w to $269/t, indicating limited downward pressure on raw material costs. The marginal decline in these benchmarks has yet to translate into lower domestic met coke prices, as prevailing transaction levels and grade-specific requirements continue to support price stability.
Chinese coke price cuts deepen pressure on global market
China’s second round of metallurgical coke price cuts took effect nationwide on 12 October, bringing cumulative reductions to RMB 200-220/t ($30-33/t) since October 1. A further third round of cut is anticipated amid persistent weakness in the steel market, although resistance from coke producers could limit the pace of reductions.
Post-holiday restocking by downstream buyers provided some initial support; however, the recovery in demand proved short-lived. Continued pressure on steel sector profitability and uncertain consumption prospects are likely to weigh on Chinese coke demand, potentially limiting any recovery in international met coke prices and influencing sentiment in the Indian market.
Falling pig iron prices weigh on domestic demand
Durgapur steel-grade pig iron prices declined by INR 550/t w-o-w to INR 41,300/t ex-works, indicating continued pressure in the downstream market. Lower pig iron realisations can constrain margins and purchasing flexibility among steelmakers and foundries, potentially limiting their willingness to absorb higher input costs. This has added to the cautious sentiment prevailing in the domestic met coke market.
Outlook
Indian met coke prices are likely to remain largely range-bound in the near term, with a downside bias if international coking coal and Chinese coke prices continue to weaken. Cautious steel-sector procurement, subdued downstream realisations and limited demand recovery are expected to restrict upward price movement.
However, stable domestic transaction levels, demand for specific quality grades and any resistance from coke producers to further price reductions could limit the downside. Market direction will largely depend on changes in steel demand, Chinese coke pricing and movements in imported coking coal and met coke benchmarks.
Leave a Reply