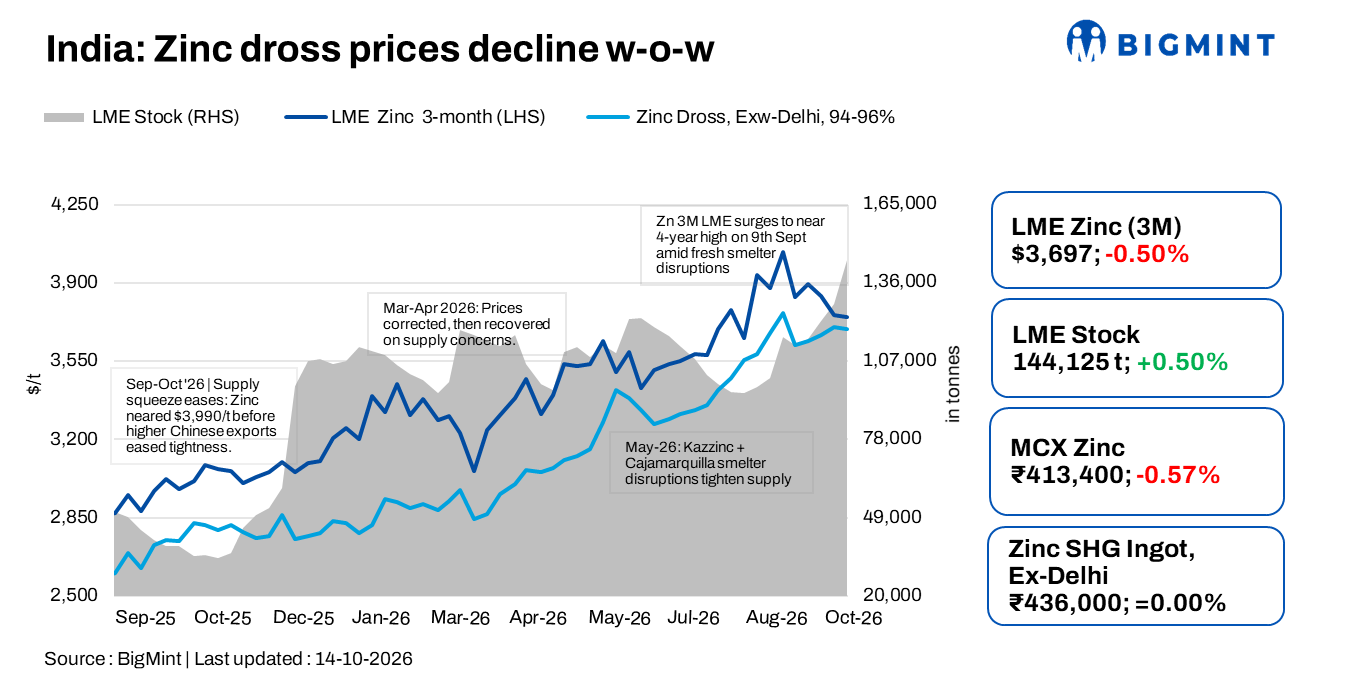
- LME zinc 3-month price declines marginally w-o-w; inventories rise 12.8%
- Zinc dross and oxide prices edge lower; scrap prices decline further
India’s zinc dross and oxide prices declined marginally in the week ended 15 October, amid a sharp increase in LME zinc inventories and mixed movement in primary zinc prices. Zinc scrap prices fell more noticeably, reflecting continued weakness in the secondary market.
Three-month LME zinc declined by $7/t, or 0.2%, w-o-w to $3,749/t on 14 October from $3,756/t on 7 October. The cash-settlement price increased marginally by $4/t to $3,803/t from $3,799/t.
LME zinc inventories increased by 16,375 t to 144,125 t from 127,750 t a week earlier. Meanwhile, the cash-to-three-month backwardation widened to $54/t from $43/t, indicating that nearby tightness persisted despite rising exchange stocks.
Zinc dross, oxide prices ease
Domestic zinc dross prices declined by INR 1,000/t w-o-w to INR 350,700/t ex-Delhi on 15 October, compared with INR 351,700/t a week earlier. Zinc oxide (99% Zn) prices fell by INR 500/t to INR 334,200/t ex-Delhi from INR 334,700/t.
The marginal decline in secondary zinc prices came amid a slight decrease in three-month LME zinc prices and rising exchange inventories. While the cash-settlement price edged higher, the increase was insufficient to prevent a marginal correction in domestic dross and oxide prices.
Zinc scrap prices decline further
In the north Indian zinc scrap market, big Tukdi (97-98% Zn) was assessed at around INR 347,000/t ex-Delhi, while mid-sized Tukdi (97-98% Zn) was around INR 343,000/t. Small Tukdi was assessed at around INR 334,000/t.
Scrap prices declined during the week, with big Tukdi down INR 5,000/t, mid-sized Tukdi down INR 4,000/t and small Tukdi down INR 3,000/t compared with the previous assessment.
Domestic SHG zinc edges lower
BigMint’s assessment of domestic SHG zinc ingot prices stood at INR 436,000/t ex-Delhi on 14 October, down INR 1,000/t from 8 October. Meanwhile, Hindustan Zinc Ltd (HZL) raised its SHG zinc benchmark by INR 3,100/t to INR 411,300/t on 12 October.
Outlook
Zinc dross and oxide prices may remain under pressure in the coming week, with rising LME inventories and weaker three-month zinc prices limiting upside. However, movements in primary zinc prices and domestic replacement costs could provide some support.
The increase in LME stocks and the marginal decline in three-month zinc prices point to a potentially softer market, while the wider cash-to-three-month backwardation indicates that nearby tightness has not fully eased.
Further movement in dross and oxide prices is likely to depend on primary zinc price trends, inventory developments, nearby spreads and domestic demand.
Leave a Reply