- Absent buying interest, no firm export offers
- Domestic realisations higher than exports
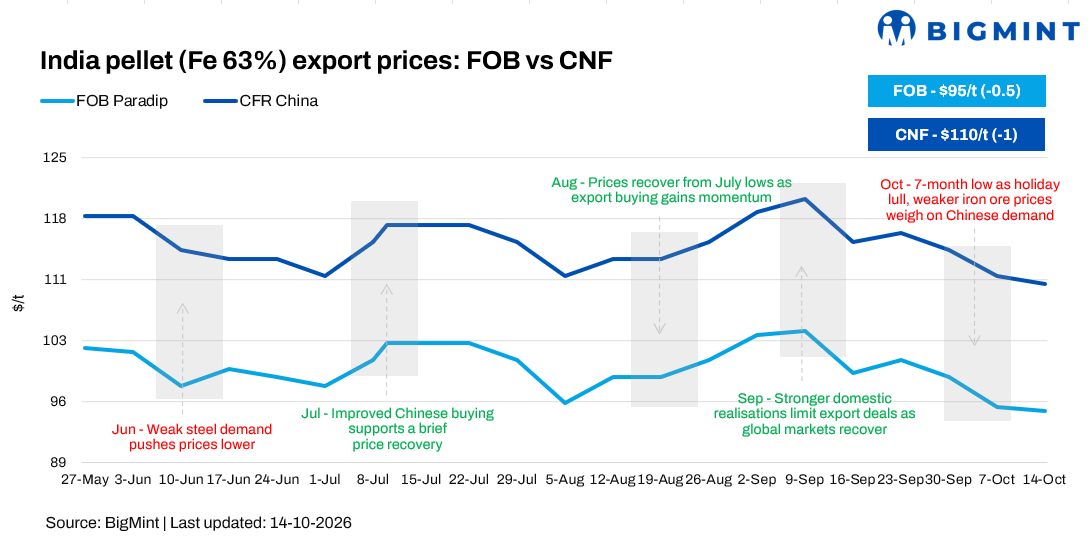
BigMint’s India pellet export index declined marginally by around $0.5/tonne (t) w-o-w to $95/t FOB East Coast in the week ended 14 October 2026, equivalent to around $110/t CFR China. Prices continued to fall after touching a seven-month low previous week, reflecting persistent weakness in export realisations and subdued buying interest from China.
Export offers remained under pressure amid cautious Chinese buying and limited demand visibility. Buyers continued to assess price levels amid uncertain steel market conditions, while Indian exporters faced challenges in securing competitive realisations in the overseas market.
“Buying interest remains absent, with no firm export offers reported so far”, said a trader.
However, Chinese pellet inventories across 34 major ports edged down to around 5.44 million tonnes (mnt) in week 42 of CY’26, from 5.53 mnt a week earlier. The marginal decline indicates some drawdown in port stocks, potentially reflecting continued cargo consumption and limited fresh arrivals. However, the reduction remained modest and has yet to signal a meaningful improvement in demand, as cautious procurement by Chinese steel mills and weak steel margins continue to limit restocking activity.
Rationale
- Zero (0) deals from India’s east coast were recorded for T1 trade during the publishing window; therefore, this category was assigned a 0% weightage in today’s price calculation.
- Five (5) bids, offers, and indicative prices were heard, of which all were considered for the calculation of the index and given the balance 100% weightage.
“Most producers are not willing to sell at current levels. Yesterday a major pellet producers’ tender did not conclude. We heard that material was sold domestically at around INR 11,300/t ($117/t), which is much higher than what is achievable in the export market today,” a trader said.
The disparity between domestic and export realisations is consequently limiting sellers’ willingness to participate in the seaborne market.

Domestic market remains more attractive
The domestic market continued to offer better realisation opportunities for Indian pellet producers compared with exports. This has encouraged sellers to prioritise domestic sales, limiting their incentive to pursue overseas bookings at prevailing export prices.
Export realisations for Fe 63% pellets mostly stable w-o-w to INR 7,000/t ($73.4/t) ex-works this week. However, the modest recovery remained insufficient to significantly improve export competitiveness. Meanwhile, domestic realisations for Fe 62.5% pellets increased to INR 9,600/t ($101/t) ex-works, supported by comparatively stronger domestic market economics.
Consequently, the gap between domestic and export realisations widened by INR 381/t ($4/t) w-o-w to INR 2,531/t ($26.6/t), further strengthening the relative attractiveness of domestic sales. The widening differential is likely to reinforce exporters’ cautious approach, particularly amid subdued overseas buying interest and limited visibility on fresh export deals. With domestic realisations offering a substantial premium over export earnings, pellet producers are likely to prioritise the domestic market unless international prices improve enough to narrow the gap.
Meanwhile, iron ore pellet dispatches plunged to 48,000 t during 3-9 October 2026, down from 130,520 t in the previous week, with the entire volume shipped through Kandla port.
Global iron ore and DCE futures decline amid cautious Chinese buying
- Iron ore index falls to $90/t CFR China: The benchmark iron ore fines (Fe 61%) index declined by $1/dry metric tonne (dmt) w-o-w to $90/dmt CFR China on 13 October 2026, from $91/dmt on 7 October. Prices remained under pressure amid cautious buying by Chinese steel mills following the Golden Week holiday, with subdued steel demand, margin pressures and limited restocking interest weighing on market sentiment. Buyers continued to adopt a wait-and-watch approach, limiting spot market activity. Near-term price movements will depend on the pace of mill restocking, steel demand recovery and changes in production levels in China.
- DCE iron ore futures fall on cautious demand outlook: Iron ore futures on the Dalian Commodity Exchange (DCE) for the January 2027 contract declined by RMB 28.5/t ($4.3/t) w-o-w to RMB 674/t ($100.7/t) on 14 October 2026, from RMB 702.5/t ($105/t) a week earlier. The sharp decline reflected persistent caution over China’s steel demand following the Golden Week holiday, with weak steel margins and uncertainty over mills’ restocking plans weighing on market sentiment. Buyers remained selective amid limited signs of a sustained recovery in steel consumption, while expectations around production controls and the pace of downstream demand continued to influence futures trading. The near-term outlook remains cautious, with prices likely to depend on improvements in steel mill profitability, restocking activity and demand for finished steel.
Outlook
Indian pellet export prices are likely to remain under pressure in the near term unless Chinese buying interest strengthens or export realisations improve. Meanwhile, the domestic market is expected to remain the preferred destination for producers as long as it offers better returns than overseas sales.
Leave a Reply