- Pakistan: European shredded offers eased amid cautious buying interest
- Bangladesh: Australian scrap deals supported active import market
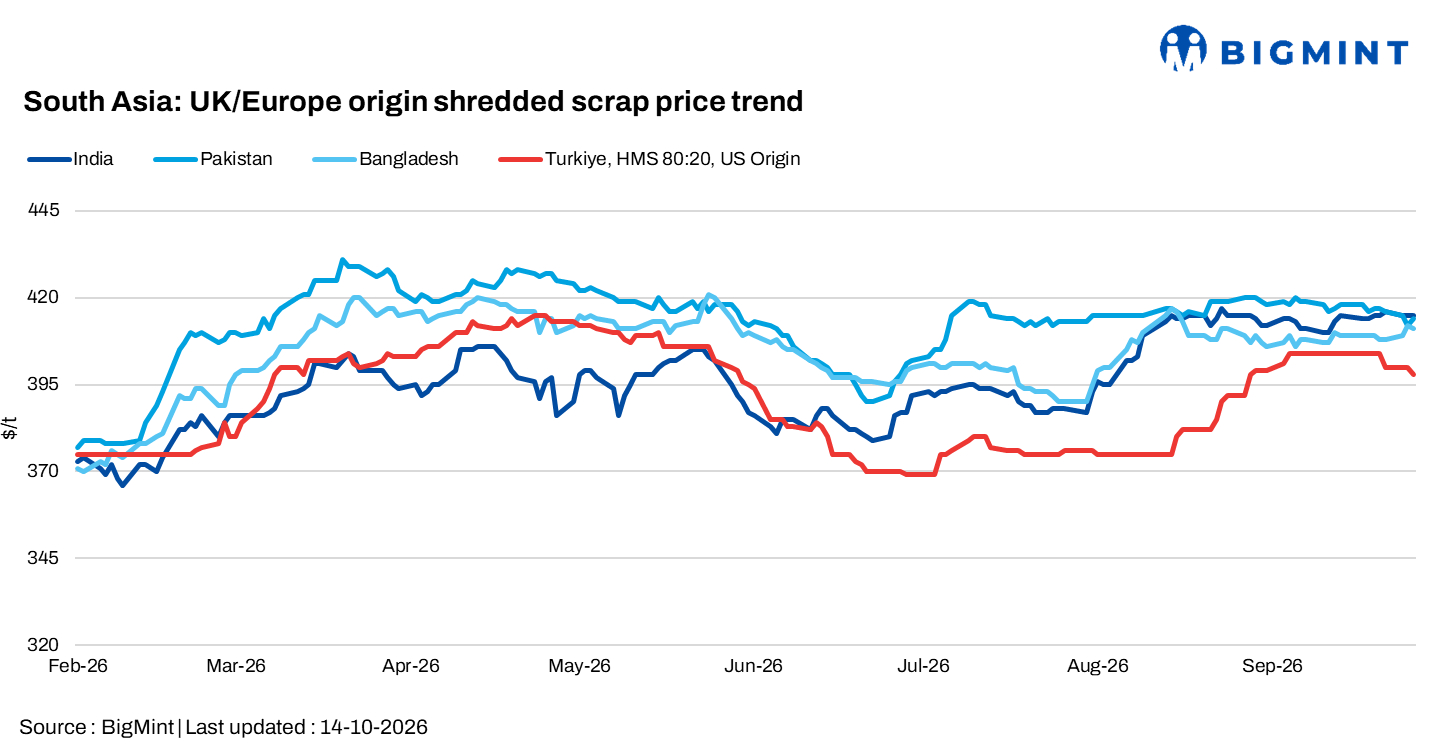
South Asia’s scrap market remained mixed on 14 October 2026, with subdued import buying in India, easing offers in Pakistan and active trading in Bangladesh. In Turkiye, weaker rebar demand weighed on sentiment, while elevated freight costs limited sellers’ flexibility.
India: Indian scrap buyers remained cautious, with no confirmed trades or firm bids and offers reported in the imported containerised segment. Lower domestic scrap prices and softening rebar demand continued to weigh on import interest, prompting mills to prioritise locally available material. UK-origin shredded scrap offers stood at $410–415/t, while HMS 80:20 bids were reported at $355–360/t CFR Mundra, significantly below offers of around $370/t CFR. Meanwhile, pool iron, plate iron and beech iron were assessed at $347/t CFR Mundra, and iron skull at $337.86/t CFR Mundra.
Pakistan: Imported scrap market remained under pressure, with European-origin shredded scrap offers falling to $413–415/t CFR Qasim from $420–425/t earlier, while bids stood at $410–412/t. UK-origin shredded scrap was workable at around $415/t CFR Qasim, with offers slightly higher. Meanwhile, domestic scrap prices remained elevated at PKR 132,000–134,000/t ($477–484/t), limiting the competitiveness of imported material.
Bangladesh: Imported scrap market remained active, with Brazilian HMS offered at $370-380/t, while Malaysian GI bundles and LMS bundles were quoted at $335/t and $345/t, respectively. Malaysian bushling was offered at $410/t. Domestic scrap prices stood at BDT 52,000-57,000/t.
Recent deals included a Australian shredded scrap at $420/t CFR Chattogram and a Australian HMS 80:20 at $380-390/t CFR Chattogram. Additionally, a UK-origin containerised PNS scrap was reported last week at $418-420/t CFR Chattogram, indicating continued buying interest in imported material.

Turkiye: Deep-sea scrap prices weakened at the beginning of the week as falling rebar prices weighed on market sentiment. However, prices remained largely stable, with tradable values for US-origin HMS 80:20 assessed at $390-402/t CFR, while EU-origin material was reported at $380-390/t CFR.
US exporters were targeting $403-405/t CFR, but elevated dry bulk freight rates continued to limit sellers’ pricing flexibility. Market participants expected prices to stabilise around $400/t CFR amid subdued downstream sentiment and persistent freight cost pressures.

Leave a Reply