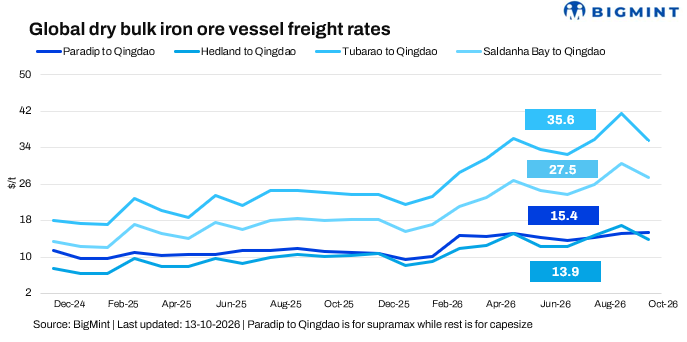
- Pacific Capesize rates weaken amid scarce iron ore cargoes and ample tonnage
- Subdued Atlantic activity limited freight levels
Iron ore vessel freight rates declined across key routes in the week ending 13 October 2026, as subdued iron ore demand, limited fresh cargo enquiries and ample vessel availability weighed on market sentiment. Rates faced broad-based downward pressure, particularly on long-haul routes from Brazil and South Africa, where weaker Atlantic demand and rising vessel availability pushed freight levels to multi-month lows.
Meanwhile, resistance from vessel owners to lower bids amid limited fresh enquiries continued to characterise the India-China route.
Route-wise sentiment

The Atlantic market remained under greater pressure as subdued Brazilian iron ore cargo enquiries and ample vessel availability intensified competition among shipowners, pushing rates on long-haul routes to multi-month lows. In the Pacific, limited fresh Australian cargo bookings and cautious Chinese buying weighed on sentiment. On the India-China route, however, shipowners continued to resist lower offers, limiting the extent of downward rate adjustments amid thin enquiry volumes.
Outlook
Dry bulk iron ore freight rates are likely to remain under pressure until fresh cargo enquiries improve. Pacific sentiment will depend on renewed Australian iron ore bookings and sustained Chinese buying, while the Atlantic market will require stronger Brazilian cargo flows to absorb available tonnage. Any post-holiday recovery in Chinese demand could provide support, but a sustained rebound will depend on an improved cargo-to-vessel balance.
Leave a Reply