- Buyers focus on immediate needs amid price uncertainty
- Suppliers face wide bid-offer gaps and tight liquidity
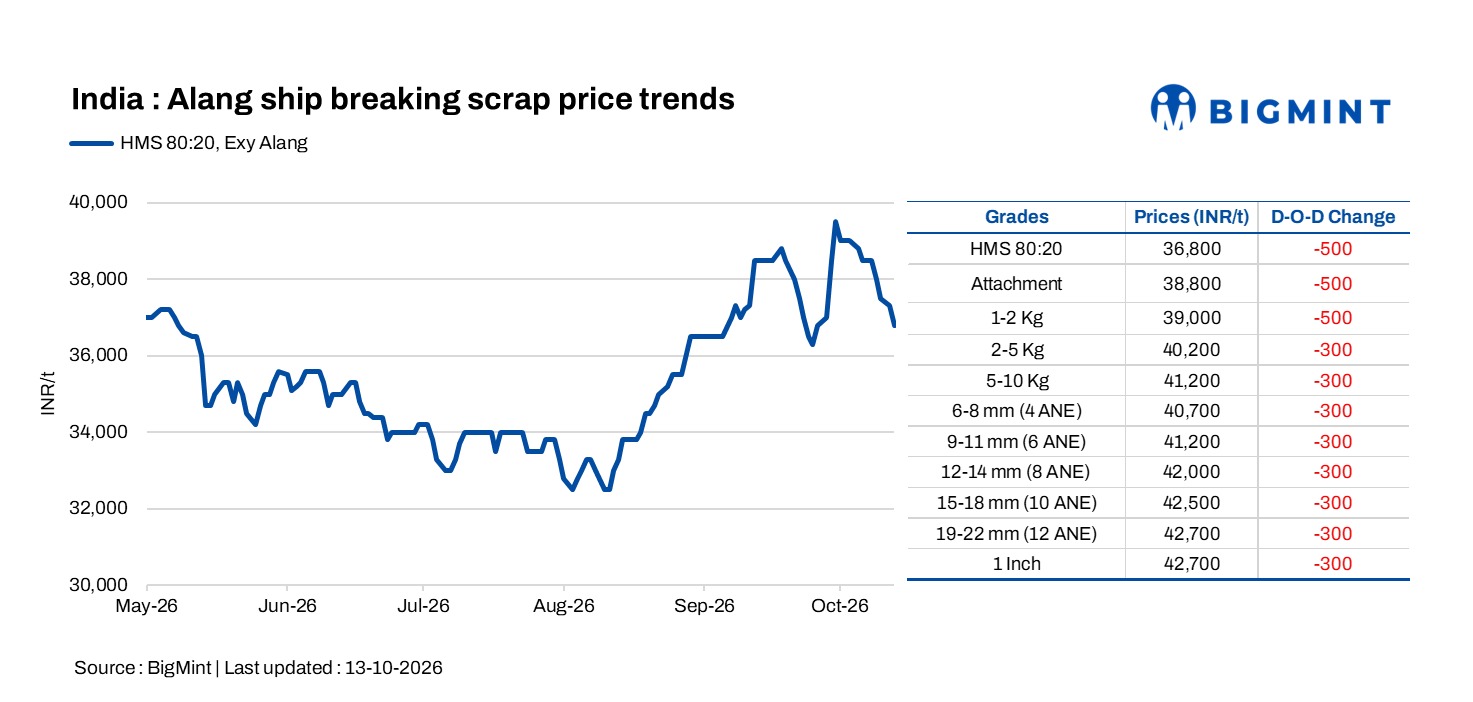
Alang’s ship-breaking melting scrap prices (HMS 80:20) declined by INR 500/tonne (t) d-o-d to INR 36,800/t ($386/t) ex-yard on 13 October 2026. Persistent weakness in downstream steel markets has further dampened buying interest, with buyers reluctant to commit to fresh purchases amid expectations of continued price volatility. Trading activity remains subdued, as most buyers are covering immediate requirements rather than building inventories.
The gap between buyers’ bids and sellers’ price expectations continues to constrain trade, with uncertainty over the near-term direction of finished steel prices limiting the scope for a recovery in scrap prices.
Gujarat market update

In Gujarat, billet prices at Bhavnagar fell by INR 200/t d-o-d to INR 46,000/t DAP, while rebar prices in Ahmedabad remained unchanged at INR 52,500/t ex-works. The decline in billet prices reflects continued pressure on secondary steel producers amid subdued demand and weak price realisations.
Despite stable rebar prices, market sentiment remains cautious, with buyers reluctant to make aggressive purchases without clearer signs of improvement in finished steel demand. This is limiting mills’ pricing flexibility and keeping sentiment in the regional scrap market under pressure.
Mandi market update
In Mandi Gobindgarh, billet prices declined by INR 250/t d-o-d to INR 47,200/t DAP on 13 October. HMS scrap prices fell by INR 300/t to INR 38,200/t DAP, while rebar prices decreased by INR 200/t to INR 52,700/t ex-works.
Healthy scrap arrivals have added to supply pressure on local suppliers, widening bid-offer disparities as active mills quote lower prices. Liquidity constraints are further reinforcing buyer caution, with procurement largely restricted to immediate requirements rather than inventory accumulation. Weak finished steel realisations are also squeezing mill margins, reducing their willingness to absorb higher scrap costs.
Outlook
Scrap prices are likely to remain under pressure in the near term as weak downstream demand, cautious buying and limited liquidity continue to constrain procurement across key markets. Any sustained recovery will depend on improved finished steel demand, stronger mill margins and a narrowing of bid-offer disparities.
Leave a Reply