- Sponge iron prices dip INR 100/t d-o-d
- Semis, finished steel prices decrease INR 200-250/t
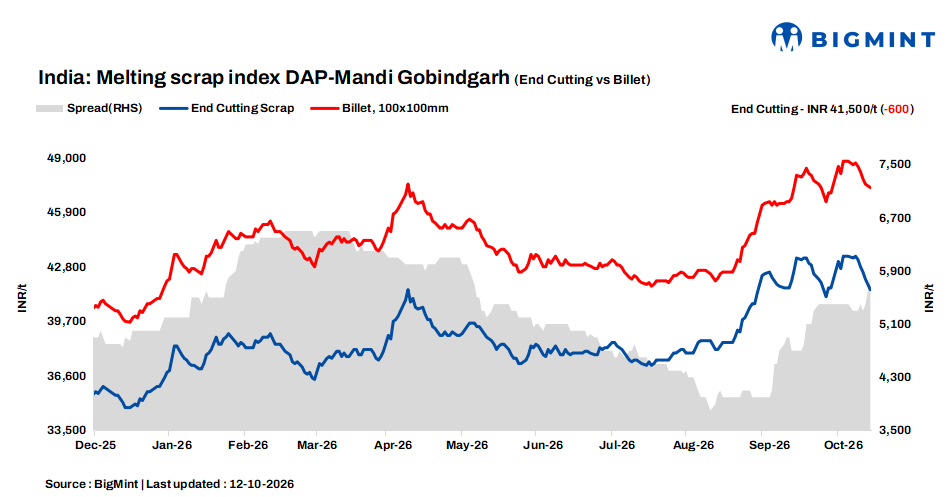
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, declined by INR 600/tonne (t) d-o-d to INR 41,500/t DAP on 12 October 2026.
Mandi Gobindgarh’s secondary steel market is grappling with subdued finished steel demand, prompting a majority of mills to slow or suspend fresh scrap procurement amid sufficient raw-material inventories. Healthy scrap arrivals have further pressured local suppliers, widening bid-offer disparities as active mills quote lower levels.
Liquidity constraints are reinforcing buyer caution, with procurement largely restricted to immediate requirements. Consequently, scrap offers are being revised downward at higher levels, while transaction activity remains selective and volume-driven. The market is expected to stay stable-to-weak until finished-steel offtake improves and mill inventories normalise.
Within a week, prices across all scrap grades in Mandi Gobindgarh declined by around INR 1,800-2,100/t, reflecting mounting pressure in the local scrap segment.
Raw material
Sponge iron prices in Mandi Gobindgarh declined by INR 100/t d-o-d to INR 34,000/t DAP, as local mills remained selective amid limited buying interest. In contrast, steel-grade pig iron prices held steady at INR 44,000/t DAP, reflecting relatively balanced availability.
Steel market
Semi-finished steel prices in Mandi Gobindgarh decreased by INR 250/t d-o-d to INR 47,200/t DAP. Prices across other major steel-producing centres also declined by approximately INR 100-650/t, highlighting broad-based weakness in the secondary steel market.
In the finished steel segment, Fe500 rebar prices in Mandi Gobindgarh declined by INR 200/t d-o-d to INR 52,700/t ex-works, amid weak downstream demand. HR strip (patra) prices remained stable at INR 51,500/t ex-works; however, patra prices have fallen INR 1,700/t over the week, extending the ongoing downtrend.
Overall, weak downstream demand, limited mill procurement, and pressure on selling prices continued to weigh on market sentiment.
Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,600-6,000/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $371/-$374/t, approximately INR 37,900/t (inclusive of freight). HMS (80:20) prices in Mumbai remained stable d-o-d at INR 36,900/t DAP. Indicative prices of shredded from Europe stood at $415-$416/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,150/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply