- Weak US employment data, interest rate concerns prompt hike
- Rising Chinese exports ease supply tightness, Western smelter risks persist
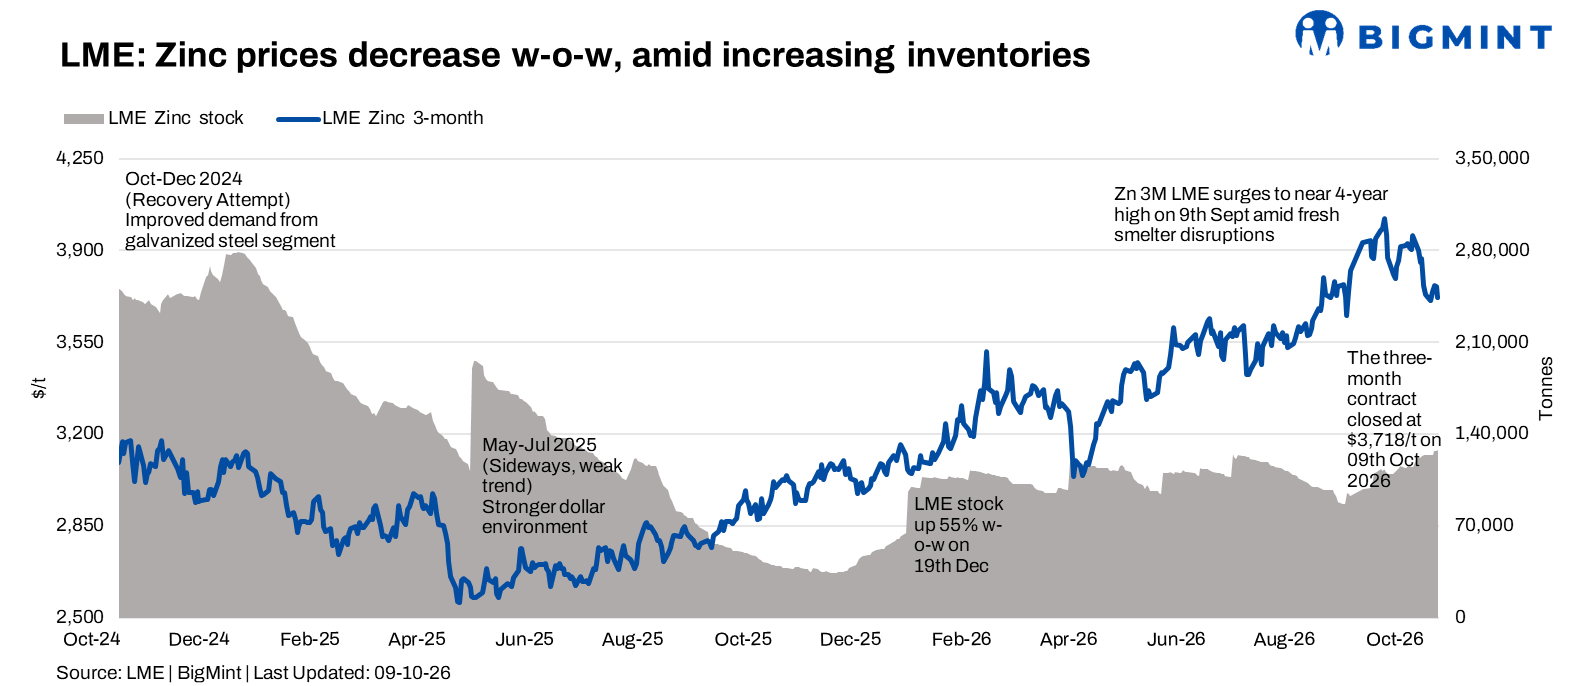
LME zinc prices recovered during the week ended 9 October following a correction during China’s National Day holiday. LME cash settlement rose 1.1% to $3,840/t on 9 October from $3,798/t on 2 October. The three-month contract increased 1.3% to $3,781.50/t from $3,733/t.
LME inventories increased by 3,100 t, or 2.5%, to 126,850 t during the week. The cash-to-three-month backwardation narrowed to $58.50/t from $65/t, indicating easing nearby physical tightness despite continued demand for cash metal.
Chinese exports ease overseas supply pressure
Zinc prices remained influenced by contrasting supply dynamics between China and Western markets. China’s refined zinc exports surged to 40,668 t in August, the second-highest monthly volume in nearly 20 years, according to the World Bureau of Metal Statistics. The country recorded net exports of 4,388 t during January-August 2026 amid slowing imports and favourable overseas prices.
Chinese deliveries have contributed to rising LME inventories, particularly in Asian warehouses, easing some of the supply pressure behind the earlier rally. However, the continued backwardation indicates that near-term availability remains relatively tight.
Western refined zinc production declined 3.4% year-on-year in H1CY’26, according to the International Lead and Zinc Study Group (ILZSG). Nyrstar’s strategic review of its Budel smelter in the Netherlands has added to concerns over potential supply constraints amid high energy costs and low treatment charges.
Rising inventories and further Chinese shipments could limit price gains, although renewed production disruptions or slower exports may tighten the market again.
LME zinc rebounds after holiday-led correction
LME zinc came under pressure during China’s National Day holiday, with the three-month contract briefly falling below $3,700/t on 2 October. Prices subsequently recovered following weaker-than-expected US employment data and a reassessment of interest-rate expectations.
The three-month contract rose to $3,756/t on 7 October before reaching $3,781.50/t on 9 October. However, it remained below the early-September four-year high of around $4,065/t.
The narrowing backwardation and continued inventory accumulation indicate that immediate supply pressure has eased. Nevertheless, the cash premium and persistent Western supply risks continue to support market sentiment.
SHFE zinc resumes trading after National Day holiday
China’s domestic zinc market remained closed from 1-7 October for the National Day holiday, with SHFE trading suspended. Trading resumed on 8 October, with prices influenced by LME movements and domestic supply-demand expectations.
Tight concentrate availability and weak treatment charges continued to weigh on smelter margins. China’s October refined zinc output was estimated at around 564,000 t, according to SMM, below earlier expectations.
On the demand side, activity improved slightly in transmission towers and high-end small hardware, while broader downstream demand remained subdued. Social inventories declined to 193,100 t before the holiday as consumers restocked, although some post-holiday accumulation was expected.
MCX zinc rebounds as open interest declines
MCX zinc futures recovered during the week, with the October contract closing at INR 422.05/kg on 9 October against INR 410.60/kg on 1 October, up INR 11.45/kg, or 2.8%.
The contract touched a weekly high of INR 429.85/kg on 8 October and a low of INR 407.10/kg on 5 October. Open interest declined to 1,993 lots from 2,669 lots on 1 October, a decrease of 25.3%.
Prices recovered alongside international markets, although the decline in open interest indicates reduced outstanding positions without establishing a definitive cause.
Domestic zinc market remains firm despite benchmark reductions
India’s domestic zinc market remained elevated despite benchmark price reductions.
Hindustan Zinc Ltd (HZL) reduced its benchmark Special High-Grade (SHG) zinc ingot price by INR 14,000/t on 5 October to INR 409,700/t, followed by a further INR 1,500/t reduction on 8 October to INR 408,200/t.
BigMint’s SHG zinc assessment stood at INR 435,300/t ex-Delhi on 9 October, down INR 1,700/t, or 0.4%, from INR 437,000/t in the previous week’s comparison. The assessment remained INR 27,100/t above HZL’s latest benchmark.
The domestic correction reflected weaker international prices and benchmark revisions, while elevated replacement costs and global supply concerns continued to influence market sentiment.
Outlook
LME zinc is expected to remain volatile as rising inventories and Chinese exports counter persistent concentrate and Western smelter supply risks.
The recovery towards $3,840/t indicates support following the early-October correction. However, further inventory accumulation and increased Chinese shipments could limit the upside, while renewed supply disruptions may tighten the market.
Support is seen at $3,700-3,750/t, while resistance is expected around $3,850-3,900/t. LME inventories, backwardation, Chinese exports, treatment charges, smelter developments and post-holiday demand in China will remain key indicators for zinc prices.
Leave a Reply