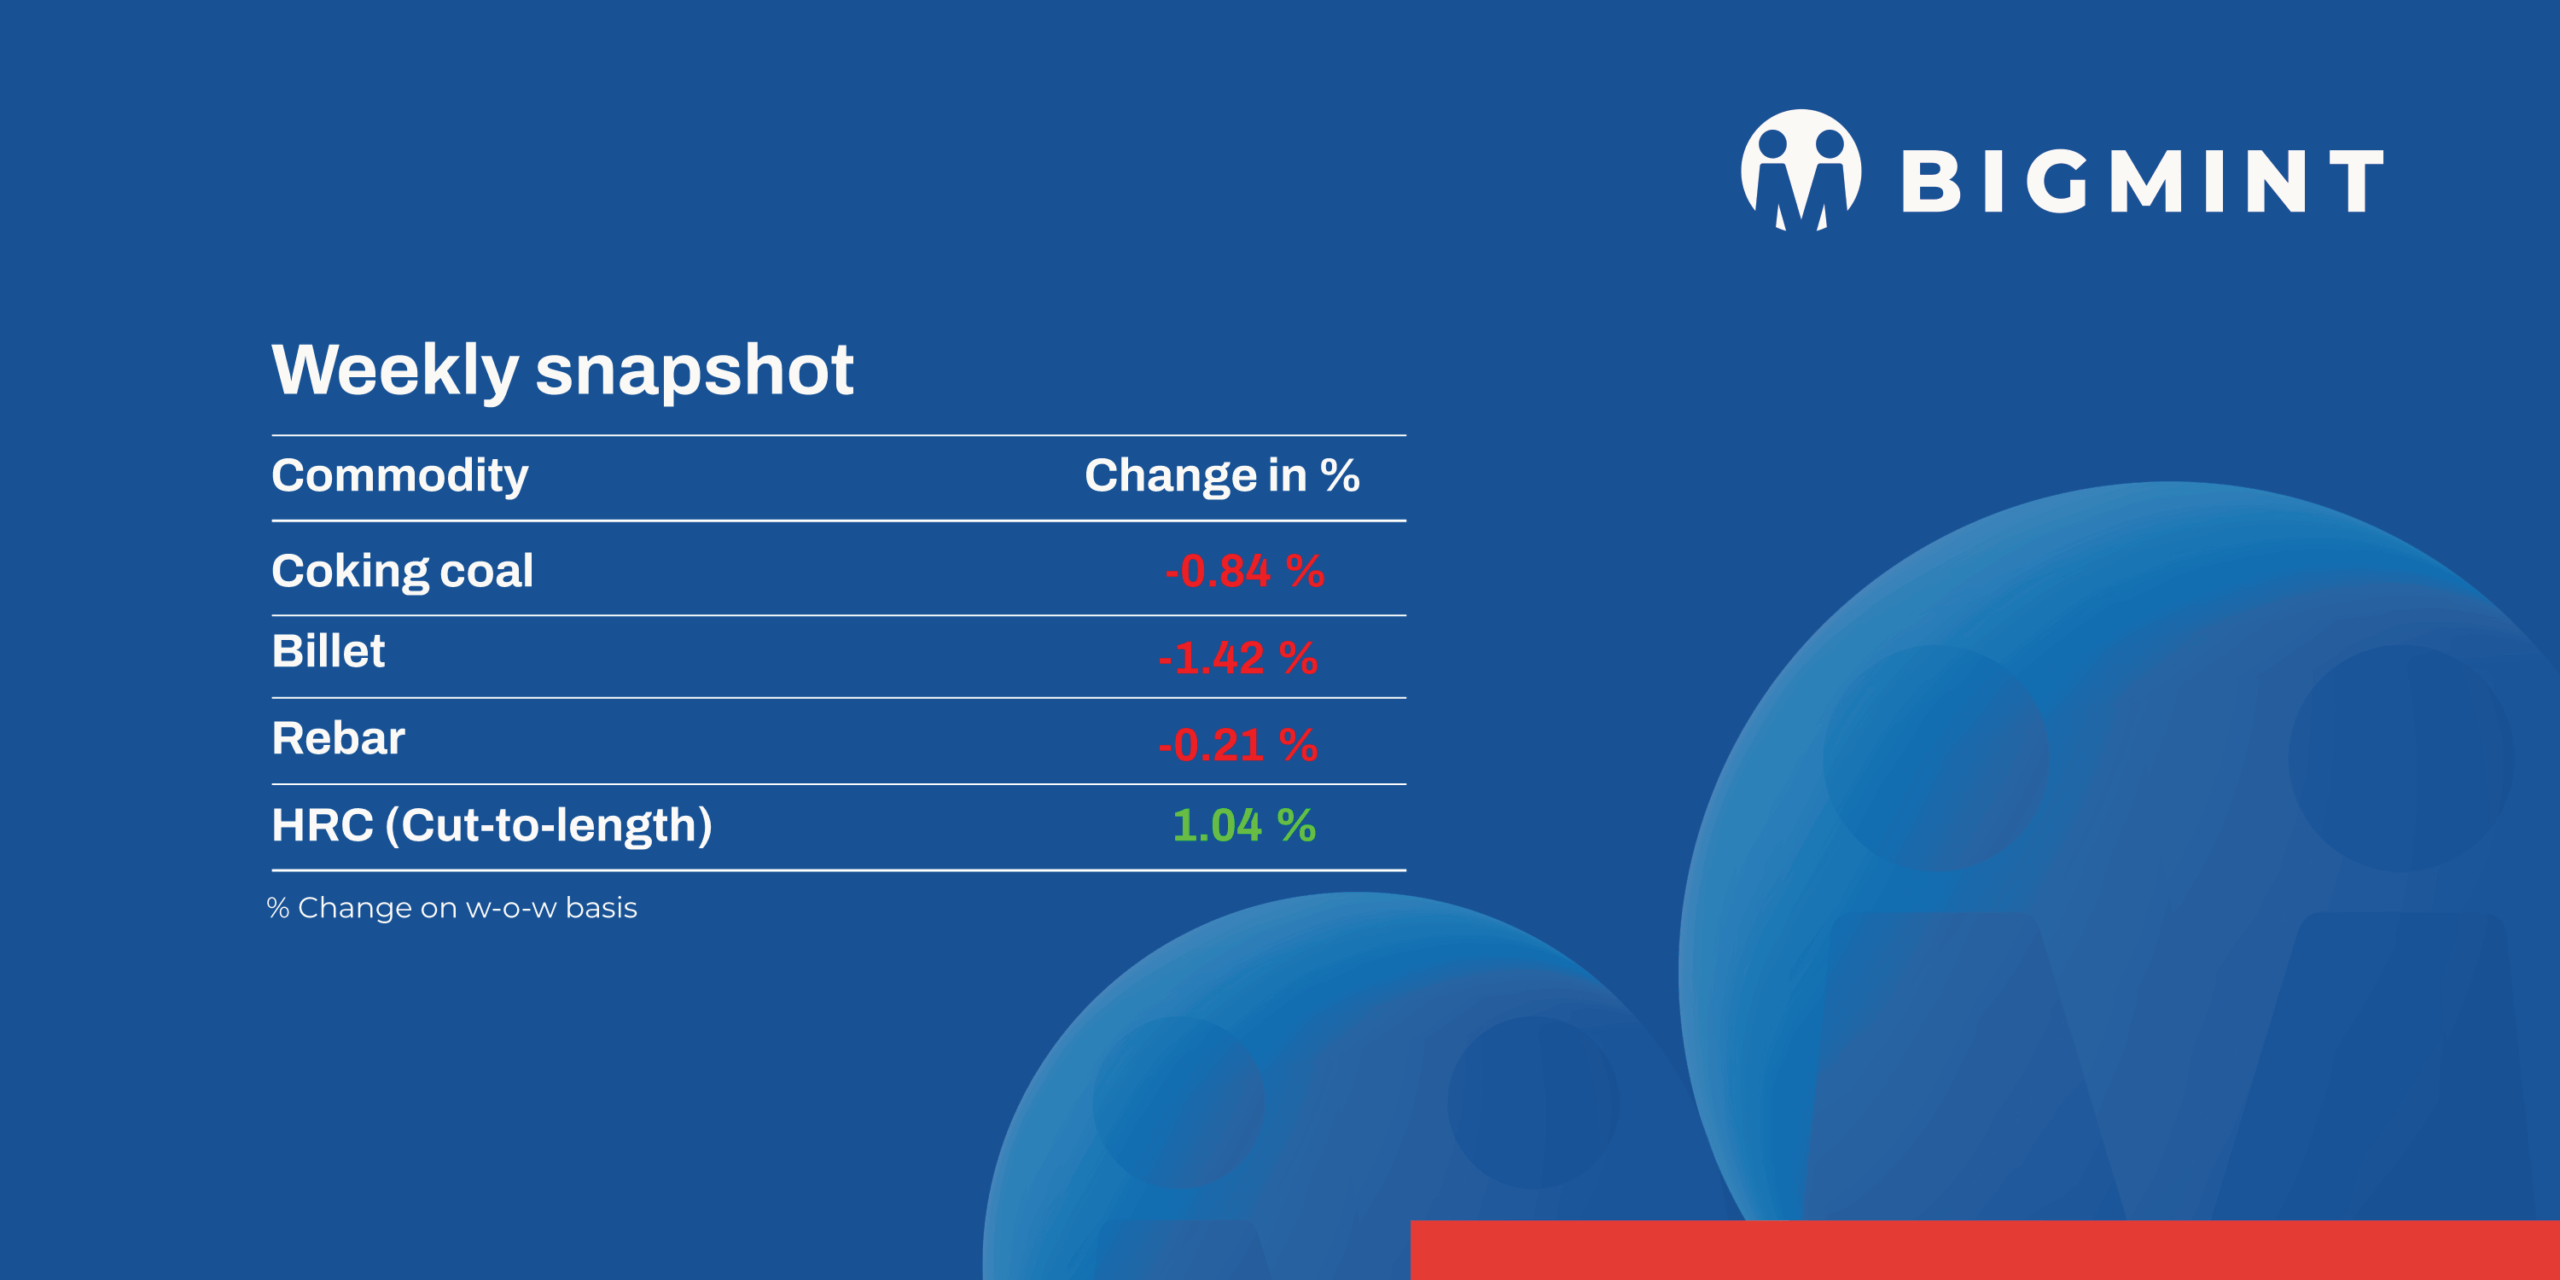
- Billets, sponge iron and IF-rebar weaken, while BF-rebar and flat steel advance.
- Ferro alloys strengthen on tighter availability and higher input costs, supporting producer offers.
Indian steel markets showed mixed trends in the week ended 9 October, with billets and sponge iron declining amid weak demand, while ferro alloys gained on rising input costs and tighter supply. BF-route rebar and flat steel prices increased, supported by mill hikes and selective buying.
Iron ore and pellet
- PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, increased by INR 300/t w-o-w to INR 11,900/t DAP Raipur on 9 October 2026. Limited pellet availability and dispatch constraints affecting iron ore fines supplies continued to support prices, despite weakening sponge iron and finished steel prices. However, trading activity remained subdued as elevated pellet prices were considered unviable amid weak downstream steel prices.
- Tirumala Constructions emerged as the preferred bidder for Andhra Pradesh’s Gutupalli iron ore block with a 47.75% final price offer. Located in Nandyala district, the 29.76-ha block holds estimated resources of 1.23 mnt at 53.45% Fe, with G2 exploration status.
- Iron ore import inquiries in India have increased as declining global prices improve import viability amid tightening domestic availability. South African lumps (Fe 65%) are currently being offered at around $118-120/t CFR India, attracting greater interest in imported cargoes. A cargo of South African lumps is scheduled for delivery at Krishnapatnam and Kandla in mid-December, sources said.
- BigMint’s India pellet export index fell by $3.5/t w-o-w to $95.5/t FOB East Coast on 7 October 2026, a seven-month low, amid weak export sentiment and limited buying interest. High iron ore costs and high domestic pellet prices kept producers at bay for exports. However, Chinese holiday further subdued market activity.
Ferrous Scrap
- Imported scrap market remained subdued to firm through the week, as weak finished-steel demand and cautious buying kept negotiations under pressure. UK HMS 80:20 with 3% impurities was bid at $340/t against offers of $360-365/t, while quality HMS was indicated at $390/t CFR India or above, though these levels remained largely unachieved.
- Trading included UK-origin turnings at $340/t CNF Nhava Sheva, Senegal- and Mozambique-origin HMS 80:20 at $380/t CFR Mundra, and US-origin HMS 80:20 at $390/t CFR Mundra. UK shredded offers stood at $410-415/t, while US shredded was offered at $415-420/t. Buyers favoured prompt-arrival cargoes from Southeast Asia and nearby origins. Australia-origin HMS in Chennai was heard at $360-365/t and shredded at $375-380/t. A weaker rupee and subdued steel demand continued to limit import activity.
- In the last seven days, 2,500-3,500 t of scrap was booked, including 1,500-2,000 t of HMS 80:20 at $372-380/t CFR, alongside 1,000-1,500 t of turning boring at $340/t.
Ferro alloys
- Silico Manganese:Silico manganese prices continue to move higher by INR 1,450/t ($15/t) to INR 84,400-85,000/t ($881-887/t) across key regions, while export offers for 65-16 grades rose by $20/t to $1,010/t FOB Vizag/Haldia.
- Domestic silico manganese demand improved as buyers increasingly looked to secure material amid concerns over further price increases and limited spot availability. The combination of tighter availability and firm seller indications has provided support to domestic prices.
- Ferro Manganese:Ferro manganese prices increased by INR 800/t ($8/t) w-o-w to INR 90,300/t ($943/t) exw Durgapur, while Raipur prices also rose by INR 800/t ($8/t) to INR 90,600/t ($946/t).Prices increased amid higher manganese ore costs following MOIL’s 5% October hike and elevated coke costs, raising production expenses and supporting producer offers despite cautious buying.
- Ferro Silicon:Ferro silicon prices increased by INR 600/t ($6/t) w-o-w to INR 95,000/t ($991/t) in Guwahati, while Bhutan prices stayed unchanged at 94,000/t ($981/t). Prices increased amid plant closures in Meghalaya, which tightened domestic ferro silicon availability and reduced spot supply, supporting higher offers despite otherwise cautious market activity.
- Ferro Chrome:Ferro chrome prices inched up by INR 700/t ($7/t) to INR 119,500/t ($1,248/t).Firm reductant costs, improved domestic buying, and stable export offers kept domestic prices supported.
- Additionally, At Vedanta-FACOR’s ferro chrome auction held yesterday, all the offered quantity was sold out. The bigger lot (Cr:57% min, 10-50 mm and 10-70 mm) opened at INR 118,500/t ($1,225/t) and fetched an H1 price of INR 120,000/t ($1,240/t), up INR 1,500/t ($16/t) from the opening price. Meanwhile, bids for the smaller lot of the same grade and size rose by INR 1,200/t ($12/t) from the base price of INR 119,000/t ($1,230/t) to INR 120,200/t ($1,242/t).
- For these 2 lots, an additional sizing charge of INR 1,500/t ($16/t) was applicable. Meanwhile, the chips and fines lots fetched INR 117,100/t ($1,210/t) and INR 112,975/t ($1,168/t), respectively.
Semi finished
- Billet
India’s semi-finished steel prices declined this week as weak demand and subdued finished steel offtake pressured the market. Limited downstream consumption weighed on buying interest, while sellers faced increasing pressure to adjust spot offers. As per BigMint’s assessment, domestic billet prices fell by INR 500-1,300/t ($5-13/t) w-o-w. Gujarat recorded the sharpest decline of INR 1,300/t ($13/t), amid weak demand. Goa was an exception, with billet prices increasing by INR 500/t ($5/t) during the week. - Sponge iron
Indian sponge iron prices declined by INR 500-1,500/t ($5-15/t) w-o-w across major regions, driven by weak end-user demand and surplus spot availability. Durgapur, Mandi Gobindgarh and Bellary regions recorded notable declines as subdued demand weighed on seller offers. Buying interest remained under pressure, with buyers anticipating further price corrections amid continued weakness in downstream demand.
Indian sponge iron export offers also softened by $1-8/t w-o-w, as weak buying interest and fewer enquiries amid subdued domestic sponge iron market conditions. Pellet-based DRI offers to Nepal fell by $8/t to $315/t CPT Raxaul, while CDRI mix offers declined by $1/t to $348/t. Export offers to Bangladesh decreased by $4/t to $360/t CPT Benapole. - Pig iron
SAIL-Rourkela Steel Plant (RSP) conducted a pig iron auction on 7 October 2026, offering 5,000 tonnes, with the entire quantity booked at an average price of INR 41,400/t. The average auction price remained stable compared with the previous auction held on 28 September, where 5,000 t was offered and the entire quantity was booked at an average INR 41,400/t.
Finished long steel
- IF-rebar:IF-route rebar prices witnessed mixed trends this week. Price movements were primarily supported by rising raw material costs, particularly coal, which increased production costs and prompted mills to maintain finished steel offers at higher levels. However, buying activity remained low to moderate, with limited spot market transactions. Mill inventories were estimated at around 8-10 days, while order booking visibility remained limited to 3-5 days, varying across locations.
- The near-term outlook remains range-bound, as elevated prices continue to face resistance from buyers. Market participants are adopting a cautious wait-and-watch approach, with procurement largely restricted to immediate requirements. Further price movements will depend on raw material cost trends and any improvement in underlying steel demand.
- On a week-on-week basis, rebar prices showed mixed trends, with prices fluctuating in the range of INR 100-1,300/t across key regions, according to BigMint’s assessment.
- Trade reference prices of Fe 500-grade rebars manufactured via the IF route (10-25 mm size) were assessed at INR 48,200-48,600/t exw Raipur and INR 52,700-53,300/t exw Jalna.
- Trade reference prices of heavy structural steel for the base size 150 mm channel stood at INR 51,000-51,500/t exw Raipur.
- Trade reference prices of wire rod stood at INR 49,500-50,000/t exw Raipur.
- BF-route rebar: BF Rebar Multi-Year High: Trade-level prices rose INR 800/t w-o-w to INR 63,900/t ($660/t) ex-Mumbai (landed project sales: INR 64,000-66,000/t). Mills hiked list prices by ~INR 1,000/t amid tight prompt supply and active project buying.
- Widening Route Gap: The price spread between BF and IF route rebar in Mumbai expanded w-o-w to INR 10,400/t ($107/t). IF-route steel continues to account for 65–70% of the market.
Flat steel
- Indian HRC and CRC prices increased across key markets during the week, following mill price hikes of INR 750–1,500/t for HRC and INR 750–2,000/t for CRC. However, the hikes were only partially passed on to trade prices, as demand remained moderate and largely need-based. While southern India reported some improvement in enquiries and buying activity, demand in western and northern markets remained largely requirement-driven. Comfortable inventory levels also limited buying urgency, preventing the full absorption of mill price increases.
- BigMint’s bi-weekly benchmark assessment for Mumbai HRC (IS2062, Grade E250, 2.5–8 mm/CTL) rose by INR 600/t w-o-w to INR 64,700/t exy-Mumbai as on 9 October, compared with INR 64,100/t a week earlier. Meanwhile, Mumbai CRC (IS513, Grade O, 0.9 mm/CTL) increased by INR 500/t w-o-w to INR 74,600/t from INR 74,100/t on 1 October.
Import volumes: India’s bulk HRC imports stood at 136,802 tonnes (t) in September, with a further 80,451 t expected to arrive by the end of October. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.
Export volumes: India’s bulk HRC exports stood at 299,413 t in September. - Indian HRC export offers varied across key destinations during the assessment week ended 6 October 2026. EU-bound offers held steady at around $670/t FOB, supported by firm domestic realisations. However, no fresh bookings were reported during the week, as buyers remained reluctant to transact at elevated price levels. Meanwhile, offers to the Middle East and Vietnam remained on hold as mills continued to prioritise domestic sales, limiting volumes available for fresh export bookings.

Leave a Reply