- Chilean strike risks support copper prices amid concentrate shortages
- Indian prices rise as buying improves ahead of festive season
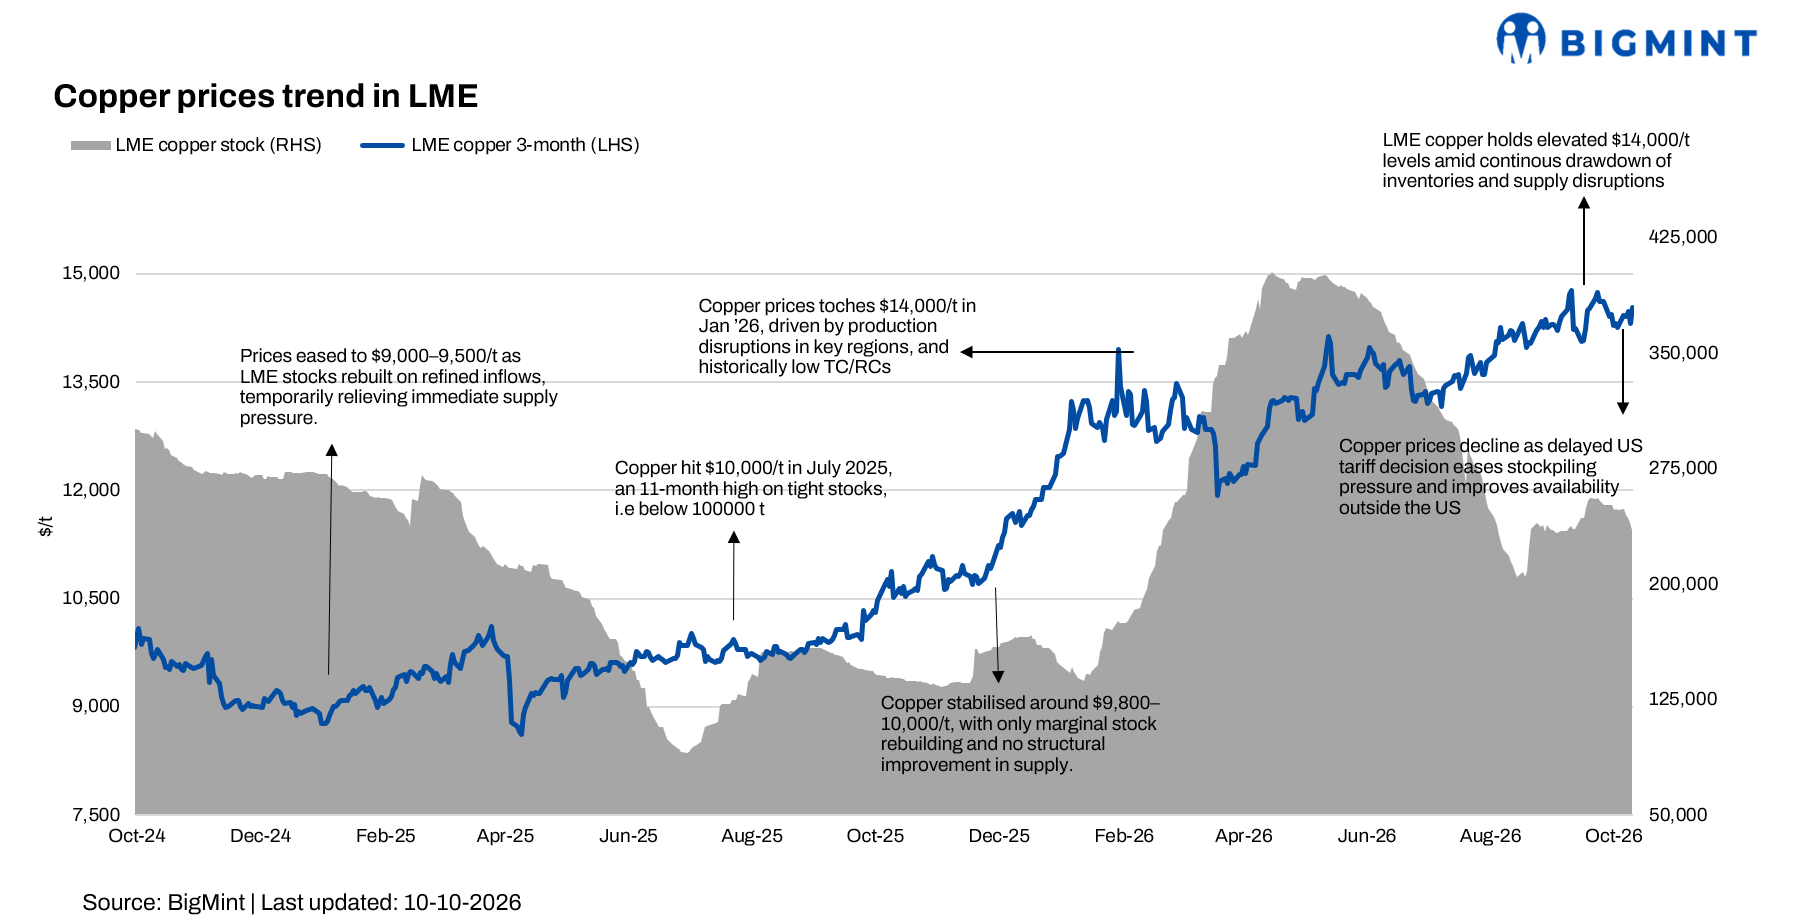
Copper prices strengthened during the week ended 9 October. London Metal Exchange (LME) three-month copper rose 2% w-o-w to $14,540/t from $14,258.50/t in the previous week. Meanwhile, LME copper inventories declined 5.2% to 235,225 t from 248,075 t, indicating tighter availability of exchange-registered metal.
Prices gained support from renewed Chinese buying after the Golden Week holiday (1-7 October), tightening concentrate availability, and labour disruptions at major Chilean mines. However, uncertainty over US trade policy continued to create volatility. In India, higher international benchmarks and pre-festive procurement lifted cathode prices, although elevated prices kept downstream buyers cautious about inventory building.
Falling LME inventories, Chilean strike risks tighten supply
Chinese buying resumed after the Golden Week holiday, adding demand support amid tightening supply. LME backwardation reached around $109/t on 8 October, signalling strong demand for nearby metal, while spot copper concentrate treatment charges in China fell to around negative $235-240/t as smelters competed for limited feedstock. Falling exchange inventories and worsening concentrate shortages reinforced the market’s bullish outlook.
Supply risks increased as workers at Chile’s Centinela mine began an indefinite strike on 7 October, involving 709 workers, or 22% of the mine’s direct workforce. Meanwhile, 95% of participating members of BHP’s 1,020-member Escondida supervisors’ union voted in favour of strike action. Government-mediated negotiations were underway at Escondida as of 9 October. Prolonged disruptions at either mine could further tighten concentrate availability and support copper prices.
US tariff uncertainty keeps price volatility elevated
Uncertainty over future US tariffs continued to influence global copper trade flows. Earlier tariff expectations encouraged inventory accumulation in the US, diverting supplies from other markets. The administration has yet to decide whether to impose additional duties on refined copper, with proposals including a 15% tariff from January 2027 and 30% from January 2028.
Refined copper cathodes remain exempt under the current framework, while covered semi-finished copper products face a 50% Section 232 tariff. Meanwhile, COMEX copper trading below LME prices has weakened the incentive for additional US-bound shipments. Consequently, market direction increasingly depends on physical supply conditions and mine disruptions, while any fresh tariff announcement could trigger renewed volatility.
Indian prices rise as pre-festive demand improves
According to BigMint’s assessment, ex-Ahmedabad and ex-Mumbai copper cathode prices rose by INR 19,000/t, or 1.35% w-o-w, to INR 1,427,000/t and INR 1,425,000/t, respectively. Higher international benchmarks, elevated import premiums and pre-Diwali procurement supported Indian domestic prices.
However, trading remained limited as high input costs constrained buyers. Cable, electrical equipment, and automotive wiring manufacturers prioritised immediate needs over stockbuilding. High-recovery scrap availability remained tight as material flowed through Pakistan to China, where buyers offered higher prices. Indian recyclers struggled to match these bids, limiting domestic supply and increasing procurement costs.
Kamoa-Kakula sulphuric acid output reaches record high
Ivanhoe Mines’ Kamoa-Kakula copper smelter in the Democratic Republic of Congo (DRC) produced a record 118,638 t of high-strength sulphuric acid in Q3CY’26. Output rose 5.6% from 112,307 t in the previous quarter.
The average realised price for sulphuric acid nearly doubled q-o-q to around $900/t. September sales averaged approximately $950/t. Ivanhoe expects prices to remain elevated in Q4.
Sulphuric acid is a by-product of copper smelting. Nearby copper and cobalt operations in the DRC Copperbelt use it to leach metals from oxide ores. Higher realised prices have increased the value of this by-product for Kamoa-Kakula. Prices will depend on regional demand, supply availability and operating conditions across the Copperbelt.
Outlook
Global copper prices are expected to remain firm next week, supported by tight concentrate availability, constrained supplies of refined-grade material and elevated exchange prices. In India, domestic cathode prices may gain further support after mid-October as festive demand strengthens. Higher consumer spending on automobiles, electrical appliances and other durables is expected to encourage downstream manufacturers to replenish inventories. However, profit-booking following recent gains and fluctuations in exchange inventories could temper further price increases.
Leave a Reply